 Have a question? +971 56 404 0503

Hospitality
A RELAXING POOLSIDE RETREAT AT PALACE DOWNTOWN

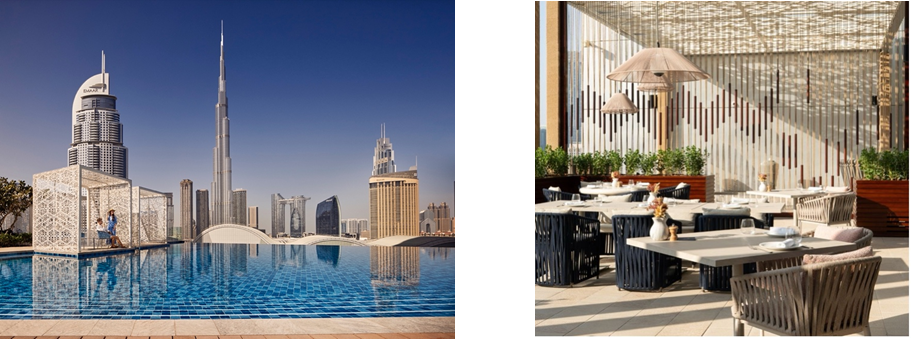
Enjoy a relaxing day under the Dubai sun with the Pool Pass at Palace Downtown, available on food and beverages. Perfect for a leisurely daytime escape, the offer allows guests to indulge in refreshing drinks and light bites while unwinding in a serene poolside setting in the heart of Downtown Dubai.
Surrounded by palm trees and the hotel’s elegant Arabian-inspired architecture, the pool at Palace Downtown offers a tranquil oasis with breathtaking views of the iconic Burj Khalifa. With its peaceful atmosphere, comfortable loungers, and attentive service, the pool creates the perfect setting for a sun-soaked retreat blending relaxation with refined hospitality.
Date & time: Monday & Sunday | 7am – 7pm
Price: AED 250 (fully redeemable on F&B credit) | Location: Ground Floor, Palace Downtown
Sun-Soaked Poolside Escape at Address Downtown
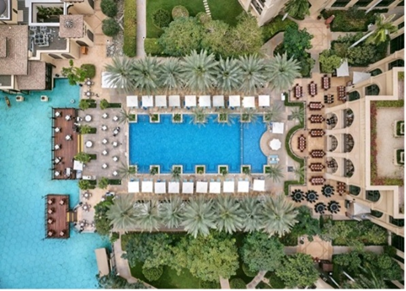
Enjoy a refreshing day in the heart of the city with the Pool Pass at Address Downtown, available daily at AED 350 per person, fully redeemable on food and beverages. Perfect for a leisurely daytime retreat, the offer allows guests to indulge in poolside dining while relaxing in a sophisticated setting overlooking Downtown Dubai.
Surrounded by elegant design and breathtaking views of the iconic Burj Khalifa skyline, the pool at Address Downtown offers a serene urban oasis. With its tranquil atmosphere, comfortable loungers, and attentive service, it provides the perfect setting to unwind, soak up the sunshine, and experience a relaxed yet refined poolside escape.
Date & time: Monday & Sunday | 7am – 7pm
Price: AED 350 (fully redeemable on F&B credit) | Location: LobbyLevel, Address Downtown
Contemporary Mediterranean Flavours at Solara, Address Dubai Mall
Set against the vibrant backdrop of Downtown Dubai, Solara at Address Dubai Mall invites guests to discover a contemporary Mediterranean dining experience infused with Middle Eastern flair. The stylish restaurant offers a relaxed yet sophisticated atmosphere with stunning views of the Burj Khalifa and Dubai Fountain, creating the perfect setting for an elegant evening.
Guests can enjoy a specially curated two-course set menu for AED 199 per person or a three-course set menu, available for dinner from 6:30 PM to 11:30 PM. Designed to highlight Solara’s vibrant flavours and refined culinary style, the experience promises a memorable night of exceptional cuisine in one of Downtown Dubai’s most scenic dining destinations.
Experience: The Luncheon
2 course set menu at AED 199 | 3 course set menu at AED 249 | Timing: From 6:30 PM – 11:30 PM | Location: Solara, Address Dubai Mall
Discover a Renewed Haven of Calm at The Spa at Address Dubai Mall
The Spa at Address Dubai Mall unveils a refined wellness experience designed to restore balance and elevate relaxation. Nestled within the iconic hotel, the serene setting enhanced by soft lighting, soothing textures, and graceful interiors offers a peaceful retreat from the energy of the city, inviting guests to unwind and reconnect in a tranquil atmosphere.
Guests can indulge in expertly delivered treatments tailored for deep rejuvenation, including the Signature Wellness Rebalance Massage, a 60-minute experience available at AED 450. Thoughtfully designed to restore harmony, the treatment provides the perfect opportunity to pause, recharge, and embrace a moment of calm within one of Downtown Dubai’s most elegant wellness destinations
Experience: 60-Minute selected Spa Treatment
Price: AED 450 | Timing: From 12:00 PM – 9:00 PM | Location: The Spa, Address Dubai Mall
Cool Off in Style with Pool Access & Dining Credit at Address Dubai Mall
Immerse yourself in pure indulgence at Address Dubai Mall’s breathtaking infinity pool, where shimmering waters meet the glamour of Downtown Dubai. Bask in the golden sun as you take in the spellbinding views of the iconic Burj Khalifa, creating picture-perfect moments of serenity and sophistication. Enhance your experience with an exclusive pool access pass that comes with a delightful dining credit to tantalize your taste buds.
Relax in the comfort of elegant poolside lounges, sip on refreshing beverages, and savor gourmet delights while basking in the most coveted views in the city. Float effortlessly in the infinity waters or unwind in breezy, sun-kissed lounges, where every moment is a scene of pure bliss waiting to be savored. No reservations required; simply stroll in and surrender to luxury. Pool access passes are available at the Pool Counter on Level 12.
Date & time: Daily | 10am – 7pm | Price: All 7 Days of the week- AED 200, fully redeemable on F&B credit | Location: Level 12, Address Dubai Mall
As some of the world’s leading figures in hospitality investment prepare to gather at Madinat Jumeirah in Dubai tomorrow for Future Hospitality Summit – FHS World 2026, investors have set out their views on the trends and strategies that are shaping the future of hospitality investment.
Widely regarded as the Middle East’s leading hospitality investment forum, FHS World will welcome more than 200 investors representing over USD$ 5 trillion in assets under management. Some 25 percent of those investors are attending for the first time, and 40 percent are travelling from outside the GCC.
Ahead of the event, top-tierinvestors have shared their views on the future of hospitality investment. With input from Mayra A Mueller, President, CGK Partners Private Wealth, Cipta Graha Group; Fahad M. Al-Alloush, CEO, Al Raya Real Estate; Mohammed Basiony, Group CEO M Hospitality FZ; Devendra Asher, Director Hospitality, Lordship Africa, and Yassine Moamah, CEO, Imperial Living.
Has investor sentiment shifted when it comes to hospitality investment over the past 12 months, and if so, in what way?
Mayra A Muller: “Yes. Investor sentiment has become more disciplined and selective rather than less optimistic. Over the past 12 months, investors have increasingly focused on resilient assets with strong operating fundamentals, experienced management teams, and destinations supported by government tourism strategies. There is also growing interest in mixed-use hospitality developments that integrate hotels, branded residences, wellness, lifestyle, and entertainment components to create diversified revenue streams.”
Fahad M. Al-Alloush: “What was a growth conversation twelve months ago is now a risk-pricing conversation, driven by the regional conflict and the subsequent supply-chain inflation. With Hormuz disrupted and shipping rerouted, construction materials and logistics have repriced sharply, so investors are underwriting delivery cost with far more caution than they were a year ago.”
Mohammed Basiony: “Sentiment hasn’t so much shifted as it’s been postponed – construction cost inflation and logistics-driven delivery delays have pushed a number of decisions further out. That said, what’s happening at the destination level, particularly in Ras Al Khaimah/Marjan Island, is giving the market a genuinely optimistic outlook again, with the Wynn Al Marjan Island resort acting as a real game-changer for the area.”
Devendra Asher: “Yes. I believe the conversation has moved from simply asking “Is hospitality attractive?” to asking “Where is the real value, and who can execute the business plan?”
Investors are becoming more selective. Strong locations and compelling demand fundamentals remain important, but they are no longer sufficient on their own. There is much greater focus on the quality of the operator, the positioning of the asset, the ability to drive sustainable operating performance and, increasingly, the flexibility to adapt the asset to changing customer and investor expectations. I also see growing interest in hospitality-led residential models, particularly branded residences, where the combination of real estate value, hospitality services and recurring income can create a compelling proposition when the model is properly structured and operated.”
Yassine Moamah: “Yes. I think the biggest change is that investors have moved from cautious interest to more selective conviction. At the same time, investors are not buying everything. They are much more disciplined about location, operator, brand, construction cost and the ability of the hotel to generate sustainable cash flow.”
From your perspective, what are the biggest challenges and opportunities in hospitality investment today?
Fahad M. Al-Alloush: “The honest answer is that the long-term consequences of the conflict for the Gulf are not yet clear, and that is the challenge. We have built our tourism ambitions on international visitors, and international confidence is the slowest thing to return. The opportunity lies in perspective: this region absorbed many challenges before (i.e. the first and second Gulf wars) and emerged stronger each time, and those who kept building through the uncertainty were the ones positioned when demand returned.”
Mohammed Basiony: “On the challenge side, capital deployment has become more constrained: construction cost inflation is compressing returns, and supply chain and logistics disruption continue to push out delivery timelines, which in turn raises financing costs and forces investors to recalibrate return expectations. On the opportunity side, though, destination-level catalysts are shifting sentiment back toward optimism — Ras Al Khaimah and Marjan Island in particular, where the Wynn Al Marjan Island resort is a genuine game-changer, are giving investors real confidence in emerging secondary destinations beyond the traditional Dubai/Abu Dhabi axis.”
Devendra Asher: “The biggest challenge is probably the gap between the cost of capital, construction and operations and the returns that investors expect. Hospitality is also a business where execution matters enormously. A good investment thesis can quickly lose value through poor design decisions, inefficient operations, weak distribution or the wrong brand positioning. At the same time, I see significant opportunities in markets where tourism, business travel, urbanisation and wealth creation are creating long-term demand while quality hospitality supply remains relatively limited. Africa is particularly interesting in this respect. The opportunity is not simply to build more hotels; it is to develop better-positioned, professionally operated and appropriately financed hospitality assets that respond to the needs of increasingly sophisticated local, regional and international customers. For me, the opportunity lies at the intersection of real estate, hospitality and capital and in creating operating platforms that can be replicated rather than developing one-off assets.”
Yassine Moamah: “Hotels can continue to increase revenue, but investors are dealing with higher construction and renovation costs, labour inflation, financing costs and geopolitical uncertainty.
And finally, markets where tourism demand is increasing faster than high-quality hotel supply. That last point is particularly relevant to Morocco. Morocco welcomed 19.8 million tourists in 2025, up 14% year-on-year, while tourism receipts reached approximately MAD 138 billion. Through August 2026, arrivals had already reached 14.1 million, 4.5% above the same period in 2025. The country’s official objective is 26 million visitors by 2030. For an investor, that combination of tourism growth, infrastructure development and international visibility creates an interesting long-term investment environment.”
Mayra A Muller: “The main challenges continue to be geopolitical uncertainty, rising financing costs, construction inflation, and the increasing complexity of delivering sustainable developments while maintaining attractive returns. At the same time, significant opportunities exist in markets where governments actively support tourism through long-term development strategies, infrastructure investment, transparent regulatory frameworks, and competitive tax and investment incentive programs. These policies play a critical role in attracting international capital and improving project viability. Another key opportunity lies in the growing demand for experiential travel, luxury hospitality, wellness tourism, and integrated mixed-use destinations. Investors are increasingly seeking projects that generate resilient cash flows while creating long-term economic and social value for the communities they serve.”
What asset classes, geographies, and projects are currently on your radar?
Mohammed Basiony: “On my own radar, we’re currently developing a new 5-star hotel on Marjan Island, a 400-key project slated to open in 2029, which reflects our own conviction in that destination’s trajectory. More broadly, Ras Al Khaimah and similar emerging coastal destinations anchored by major branded developments are where I see the strongest pipeline of investor interest right now.”
Devendra Asher: “My immediate focus is on branded residences, hospitality-led mixed-use developments and urban hospitality assets, particularly in Africa. Nairobi is an important market because of its role as a regional business and diplomatic hub, but I believe the broader opportunity extends to other major African cities where there is a growing affluent and internationally connected customer base, combined with limited institutional-quality hospitality and branded residential supply.
I am particularly interested in models that bring together residential ownership, hospitality services and professionally managed rental income, while maintaining a strong focus on the end-user experience. Beyond the individual asset, I am increasingly interested in platforms and concepts that can be scaled across multiple markets.”
Yassine Moamah: “Morocco is particularly important for us. We believe there is significant value in partnering with recognised international operators and brands. For the right property, a strong brand can improve international distribution, operating standards and ultimately the institutional attractiveness of the asset. Beyond Morocco, we are watching the GCC, particularly Saudi Arabia, while remaining highly selective. Saudi Arabia has one of the world’s largest hotel development pipelines. Demand in the holy cities continues to benefit from structural religious tourism, We will be interested if there is an opportunity to invest in such places especially Madinah. However, the region also demonstrates why investors need to differentiate between structural growth and short-term performance. UAE hospitality performance was affected materially by regional travel disruption during the first half of 2026. So our approach is not simply to follow growth markets. We look for the right city, the right micro-location, the right asset and the right operator.”
Mayra A Muller: “Current priorities include luxury hotels, ultra-luxury resorts, branded residences, serviced apartments, wellness and medical tourism resorts, integrated mixed-use developments, and hospitality assets with strong repositioning or value-add potential. There is also growing interest in destination developments that combine hospitality with luxury real estate, marinas, golf communities, cultural attractions, and sustainable tourism infrastructure. Geographically, the focus remains on the GCC, Southeast Asia, and selected high-growth markets in Latin America, particularly destinations with supportive tourism policies, expanding air connectivity, and strong long-term visitor demand.”
Fahad M. Al-Alloush: “Serviced apartments in Saudi Arabia, particularly product that blends genuine local character with international operating expertise — domestic demand for Saudi tourist destinations is extraordinary and has proved far more resilient than international demand. The discipline required is managing seasonality, which is what separates a good location from a good investment.”
What is your outlook for hospitality investment in 2027 and beyond?
Devendra Asher: “I remain positive, but selective. I believe the next phase of hospitality investment will be less about simply adding rooms and more about creating differentiated experiences, stronger brands and more resilient operating models. For Africa, I see a long-term structural opportunity. Demographics, urbanisation, improving connectivity, intra-African travel and the growth of the middle and affluent consumer segments should continue to support hospitality demand. However, capital will need to be disciplined, and projects will need to demonstrate a clear competitive advantage and credible execution strategy. I also expect the boundaries between hospitality, residential and real estate investment to continue to blur. Branded residences, hospitality-led mixed-use developments and rental-pool models can potentially create attractive opportunities where the commercial structure, governance and operating model are aligned from the outset. Ultimately, I believe the winners will be projects where the real estate proposition and the hospitality proposition are designed as one business not as two separate components.”
Yassine Moamah: “I expect more capital to move across borders and more partnerships between local developers, international hotel operators and institutional or family-office capital. For Morocco specifically, the period between now and 2030 is particularly interesting. The country is targeting 26 million tourists by 2030, compared with 19.8 million in 2025, while continuing to expand connectivity, tourism infrastructure and accommodation capacity.”
Mayra A Muller: “We believe the long-term outlook for hospitality investment remains exceptionally positive, supported by the continued expansion of global tourism, rising demand for premium travel experiences, and increasing cross-border capital flows. As international travel continues to grow, hospitality will remain one of the world’s most attractive real asset classes, offering both resilient income generation and long-term capital appreciation. Looking ahead, capital will increasingly be directed toward destinations with strong economic fundamentals, political and regulatory stability, transparent investment frameworks, modern infrastructure, and competitive investment incentives. These factors strengthen investor confidence and support the long-term sustainability of hospitality developments. We also see significant momentum behind integrated destination developments that combine hotels, branded residences, wellness, entertainment, retail, cultural experiences, and sustainable tourism infrastructure. These mixed-use ecosystems create diversified revenue streams, enhance asset resilience, and generate lasting value for investors, local communities, and national economies. Ultimately, we believe hospitality will continue to be a catalyst for economic growth, job creation, and international investment. Markets that successfully align public policy, private capital, sustainability, and tourism development will lead the next generation of global hospitality investment.”
Fahad M. Al-Alloush: “Develop what is within our control and stop trying to forecast what is not. The returns in this cycle will come from operational efficiency and disciplined execution rather than from market timing.”
Mohammed Basiony: “I expect a gradual normalization rather than a sharp rebound — as construction cost inflation eases and supply chains stabilize, previously postponed decisions should start moving forward again, with destination-led growth stories like Ras Al Khaimah leading that recovery.”
FHS World gives investors direct access to high-value deal-making in one of the fastest-growing hospitality markets, through dedicated event features such as the FHS Dealroom, a curated showcase of premier real estate investment opportunities and cutting-edge projects. Attending investors also have use of the Investors Lounge, an invite-only networking zone, and the Investor Breakfast, both designed to connect senior decision-makers with high-value opportunities and focused discussion.
Ali Shahid,CEO, The Bench, said: “Investors are more selective than they were a year ago, which makes the quality of the conversation matter more. FHS World puts owners, operators, investors and developers in the same room to test ideas, compare notes and do business. After 21 years in the UAE, Dubai remains the natural place for that conversation, and we are looking forward to hosting our community again.”
The FHS World 2026 agenda covers everything from investment to innovation, sustainability to staffing, and technology to tourism trends, all in line with this year’s event theme, Reinvest in our Future. Delegates will experience three days of keynote speeches, panel discussions, presentations, and roundtable debates, as well as a plethora of events, networking sessions and receptions. For full details of FHS World 2026, visit the website.
Hospitality
Oman to deliver 700 new hotel rooms by year end with winter season expected to boost tourism recovery – Cavendish Maxwell

The Sultanate of Oman is set to deliver 700 new hotel rooms between now and the end of 2026, taking total inventory to 40,800 keys, according to leading real estate advisory and hospitality property consultancy, Cavendish Maxwell.
Oman opened 400 new rooms in H1 2026 – all in Q1 – amid reduced hospitality sector activity as regional travel disruptions affected international connectivity and tourism trade.
The Khareef and winter travel seasons will be key drivers in the country’s H2 hospitality performance, the company said.
Oman welcomed 992,000 guests at 3-5 star hotels in H1, down 13% on the same period last year. Airport passenger traffic declined 9.3% to 6.3 million, according to Cavendish Maxwell’s latest research, released in the run up to the 2026 edition of Future Hospitality Summit World.
Khalil Al Zadjali, Head of Oman at Cavendish Maxwell, said: “Oman’s hospitality sector entered H2 in a challenging environment. While the outlook remains sensitive to prevailing travel conditions, the July to December period typically accounts for a significant share of tourism activity, contributing 52% in hotel revenue and guest volumes last year.
“The recent Khareef season – Salalah’s peak tourism period – coupled with the upcoming winter months will indicate how effectively seasonal demand supports the wider market following the H1 disruption, which was most pronounced in the second quarter. Government and tourism sector initiatives – such as international promotions and partnerships with airlines and travel trade partners – should also help strengthen demand.”
Revenues and room rates
Oman’s 3-5 star hotels generated OMR124.2 million (US$322.7 million) in total revenue in H1, down around 12% against H1 2025. Revenue growth was strong at the beginning of the year, increasing nearly 27% year-on-year in January and almost 9% in February, before declining from March. Following the sharpest contraction in April, when revenues fell 64.5% compared to the previous April, the pace of decline moderated in May and June, at around 28% and 15.5% respectively.
Room revenue was down 11% to OMR74 million (US$192 million), with other revenue declining by 13% to OMR50.2 million (US$130.4 million). The decline in ‘other’ revenue is partly because domestic and regional travellers typically spend less per stay than long-haul visitors, Cavendish Maxwell said.
Average room rates (ARR) followed a similar pattern, with a robust start to the year before weakening in Q2. ARR was up nearly 19% year-on-year in January at OMR58.3 (US$151.6), and more than 20% in February to almost OMR61 (US$158.4). March was on a par with March 2025.
The sharpest ARR decline (around 43%) came in April but, by May, it had partially recovered, increasing more than 8% year-on-year to OMR43.7 (US$113.6) as Eid Al Adha boosted travel demand.
Occupancy
Occupancy rates across Oman averaged 46.3% in H1, down more than half compared to the same period last year. Again, performance was impressive in January and February, with occupancy around 70%, before dropping from March. The decline was most acute in Q2 as regional tensions weighed in on international travel and, while domestic visitors provided some support, it was not enough to compensate for the overall decline in visitors.
Guest volumes and source markets
After a January year-on-year increase of 7.3% in guests, volumes declined monthly, reflecting air disruption across the Gulf. The steepest drop was in April (43%), but performance picked up again in May, when the decline narrowed to 2.6% as conditions normalised and Eid Al Adha supported travel demand.
Omani nationals represented the biggest source market in H1, with 396,000 guests accounting for almost 40% of all visitors – a rise of 3.1% on the same period last year. Europeans (247,000) took second place, at 25%, but their numbers were down 31% compared to last year. With 163,000 visitors, Asians made up 16%, with a marginal year-on-year increase of 0.6%.
Most other source markets saw lower year-on-year guest volumes, with the GCC down 17%, other Arab countries down 15%, the Americas down 22%, Africa 10% and Oceania 61%.
Employment
Hospitality sector employment among Omani citizens rose 3.4% in H1, while total employment in the industry declined 2.7% year-on-year. At the end of June, the sector had just under 10,500 employees.
New supply
After delivering 400 new rooms in H1 – all between January and March – Oman is set to bring another 700 to the market by December 2026. A further 1,500 are scheduled in 2027 and 1,600 in 2028, taking total Oman room inventory to 43,900 by end of 2028.
Khalil Al Zadjali added: “Total room supply will reach 40,800 by the end of 2026 – less than the 41,400 previously anticipated because some projects have been rescheduled to next year. The upcoming, phased pipeline should help manage near-term supply growth, but the pace of visitor recovery will be key to the absorption of new capacity. With a limited number of keys coming in the near future, supply growth is unlikely to be a major constraint in the short term. However, the larger pipeline from next year and into 2028 will be more dependent on the recovery in visitor demand.”
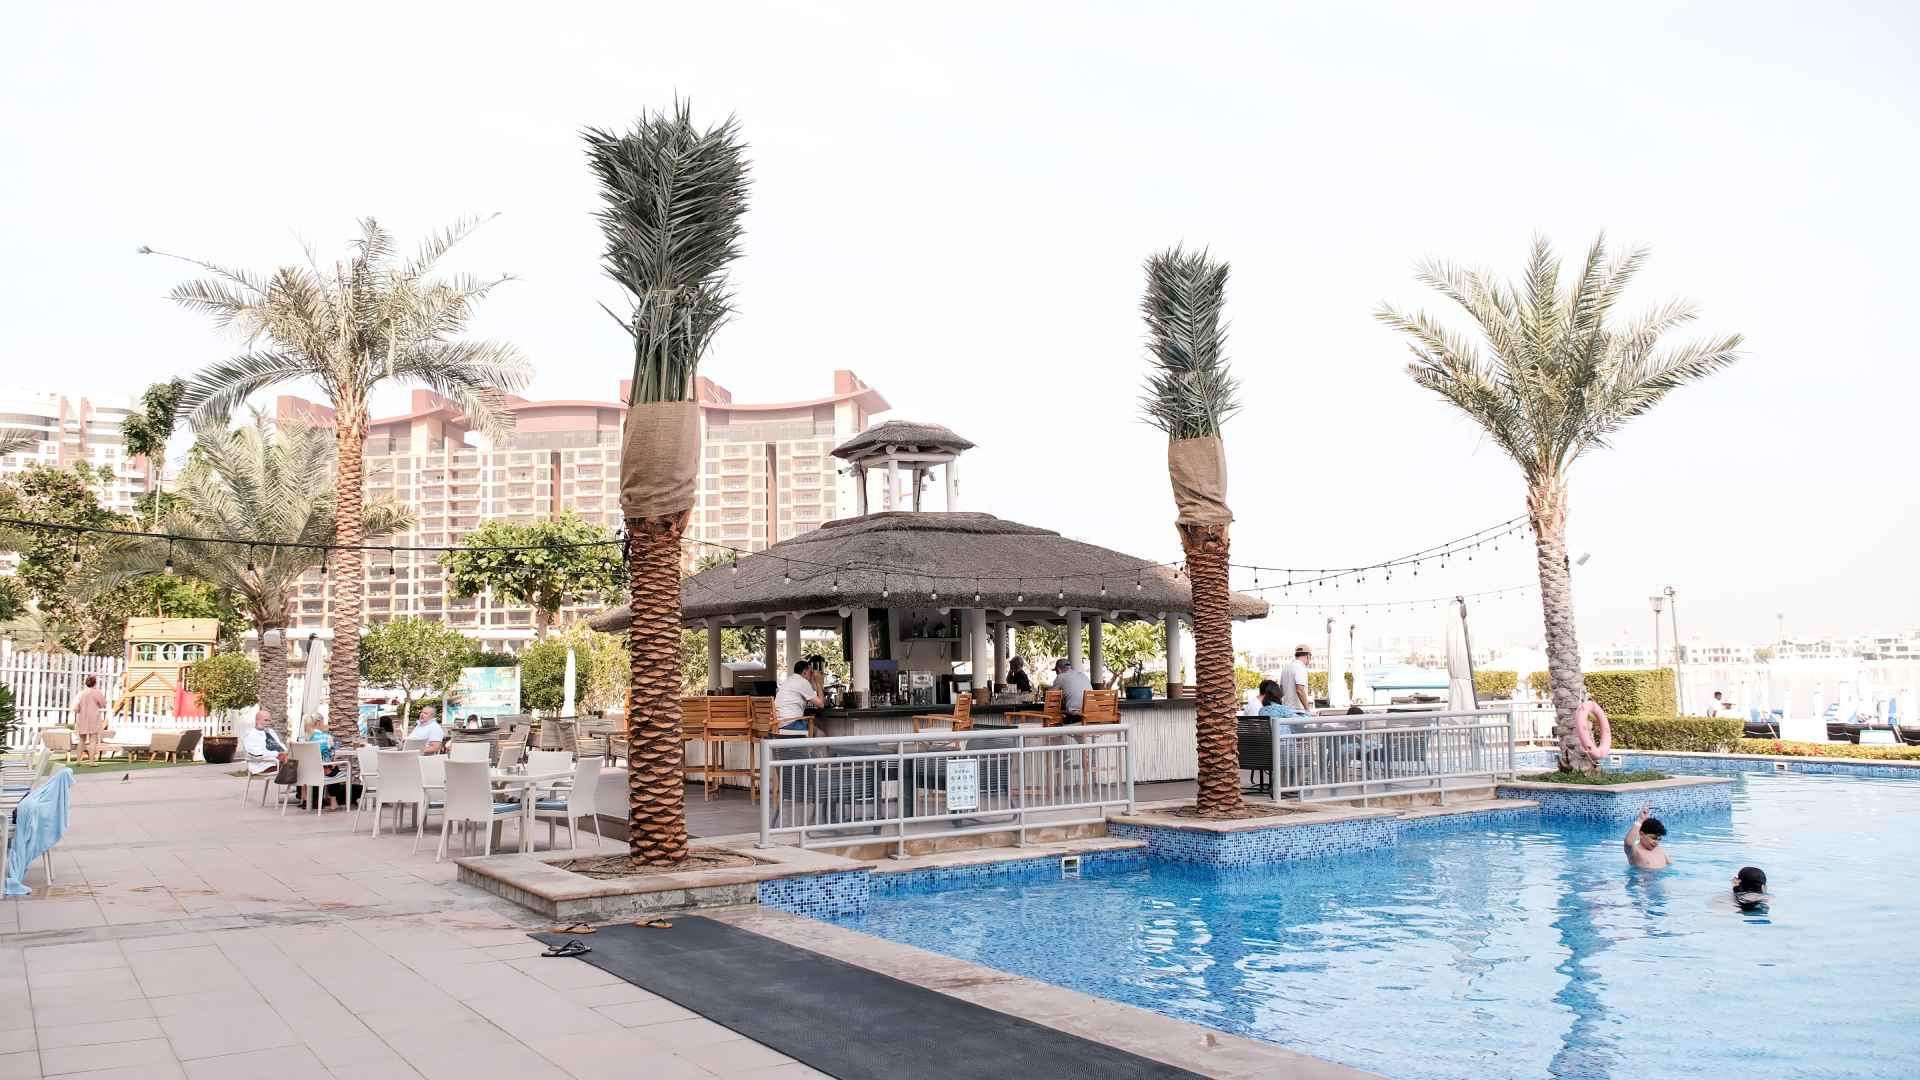
As the weather turns and Dubai settles into cooler days and fall evenings, Riva Beach Club is inviting guests to make the most of one of the most enjoyable stretches of the year by the water.
There is something special about this time of year at Riva. The air feels lighter, the evenings stretch out longer, and every part of the club, from the pool to the beach to the dining spaces, feels made for slowing down and staying a while.
The setting itself takes on a different character as the weather cools. Loungers stay comfortable well past midday, the pool becomes just as inviting in the late afternoon as it is in the morning, and the beach offers the kind of easy, unhurried backdrop that cooler weather is made for.
The season brings a refreshed line-up of offers to match. Weekday Vibes (Mon–Thu) offers adult entry at AED 99 (AED 89 F&B credit) with Happy Hour from 3pm to 9pm, while weekends bring the Weekend Treat at AED 175 (AED 150 F&B credit) and Sip & Splash’s unlimited house beverages on Fridays and Saturdays. The week also features Steak & Wine on Mondays, Ladies’ Day on Wednesdays, unlimited mimosas at The Sunday Social, and Friday Tacos from AED 49, with 40 percent off food through The Weekend Warm-Up.
Evenings, in particular, become the highlight of a visit during this part of the year. With After Dark by the Pool, guests can carry the day straight into night, settling into loungers with fresh towels and a beverage package as the temperature drops and the pool takes on a different mood after sunset. As temperatures ease after dark, the club’s outdoor spaces come into their own, offering a setting that feels just as good for a quiet evening as it does for a laid-back night with friends.
The dining experience takes on its own rhythm as the weather cools too. Meals feel more social, drinks are best enjoyed slowly, whether that’s a shared plate as the sun sets or a proper dinner once the evening settles in. Riva’s food and beverage offering is designed to match the mood of the season, easy, and best enjoyed at whatever pace suits the moment.
As the city’s outdoor social scene picks up with the cooler weather, Riva Beach Club is looking forward to welcoming guests back for exactly that, sunset swims, long dinners, and evenings spent exactly where they belong, by the water.
International Coffee Day Gets UAE-Made Twist with Rashtions’ Brazilian Coffee Truffle

Why Curation Matters More Than Ever in Fashion Retail

Keeta Marks First Anniversary in the UAE, Celebrating Nationwide Growth and Local Impact


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai