 Have a question? +971 56 404 0503

Tech Features
The Financial Sector Facing Its Black Swan: How AI Agents Are Redefining the Industry

By Julio de Salvo, Chief Solution Officer for MENA & APAC at Globant
For decades, the financial industry has managed to replace banknotes and coins with “invisible” assets through different technological implementations. However, innovation in the sector has generally moved at a slow pace when dealing with something as sensitive as people’s finances. In 2026, the black swan is beginning to emerge: the first steps of AI agents that will redefine the industry (as they will many others). The financial black swan is not a crisis: it is a huge change. Across the Middle East and Africa, where a convergence of government-backed modernization agendas, digitally native consumers, and institutional ambition is accelerating the timeline for transformation.
The first step has been the use of Gen AI without the customer perceiving it. Coding, fraud prevention, phishing detection, and credit assessment are some of its tasks. But it is now beginning to become a tool for managing users’ finances. In the MENA region, this shift is already visible at the institutional level. Across the 25 MEA banks benchmarked by the Evident AI Index (June 2026), the established leaders are no longer running pilots, they are directing investment toward high-friction processes where AI can materially reshape productivity, scalability, and competitiveness. UAE-based banks and fintechs are already validating agent-initiated transaction pipelines in production environments. These are some of the examples, but there are more.
In July 2026, the revealing Mills Review, published by the FCA (Financial Conduct Authority), the UK’s official financial regulator, pointed out that AI agents will become the new financial interface. Essentially, an AI assistant will manage budgets, answer queries, generate reports on demand, and move money between accounts. How much was spent on a vacation in total, how a stock portfolio performed over the past month, or canceling an annual subscription will be as easy as making a query to ChatGPT today. For MENA consumers, who have in many cases leapfrogged legacy banking behaviors entirely, this vision is the baseline expectation.
The Mills Review also argues that Open Banking will evolve toward a model in which AI agents will have access to a broader range of financial products to enable intelligent decisions across different areas, and highlighted that this will lead to an evolution in regulation. In the GCC, this evolution is being actively shaped by regulators and governments alike, with initiatives such as Dubai’s target of 90%+ digital transactions by 2026 signaling not just ambition, but structural commitment to a cashless, AI-enabled financial ecosystem.
The agentic AI opportunity in the region is real, but it remains underexploited. According to EY-Parthenon’s 2025 Generative AI in Banking Survey, 99% of respondents are familiar with agentic AI, yet only 31% have pursued implementation, with a further 46% expressing interest. Awareness, in other words, has raced ahead of execution. This gap between recognition and production-grade deployment is precisely where the competitive battle will be won or lost.
This represents a major shift in the industry, where historically the leading banks have, for the most part, remained the same. Differentiation can now change everything, and it would not be surprising if new players manage to break into the ranks of the world’s most important financial institutions. In the Middle East, the region’s financial landscape already includes a new generation of digital-first challengers sitting alongside heritage institutions, all of which are now actively exploring or deploying agentic capabilities. The reason sounds obvious when explained: if the experience with an AI assistant can manage customers’ money better, it will prevail. This is not an exaggeration: just four years ago, nobody knew ChatGPT, and now we have become so accustomed to it that we all ask ourselves: why shouldn’t I manage my assets with a chatbot that can provide reports and recommendations? A study by JPMorgan found that half of Gen Z wanted to use them to manage their finances.
The infrastructure for agentic commerce is also being built in real time across the GCC. Mastercard has conducted regional pilots in partnership with Majid Al Futtaim, enabling consumers to search, select, and purchase VOX Cinema tickets programmatically through an integrated AI assistant. In May 2026, Visa launched its global Agentic Ready program in the UAE, with early adopters including ADCB, ADIB, Emirates NBD, Mashreq, Tabby, Wio, and Ziina already validating agent-initiated transaction pipelines in production.
We are living in a time of change. In its 2026 report on the financial sector, the World Economic Forum urged organizations to move with “urgency” and “discipline”. The greatest benefits, it stated, will go to those working on a holistic redesign of workflows and technology architecture. In the MENA region, the conditions for genuine transformation are already in place: strong institutional will, government-aligned modernization agendas, and a consumer base that has leapfrogged legacy behaviors entirely.
One of the major questions is why, if the financial sector has such a strong technological tradition, the emergence of AI Agents represents a black swan. There are several reasons. First, historically, customers used banks to execute transactions; therefore, in the executive conversations avoiding risk was prioritized over innovation. This is changing with the emergence of digital banks, which are generally more inclined toward disruption, and shifts in consumer habits. In the GCC specifically, consumers who bypassed branch banking and moved directly to mobile-first financial services are now primed to embrace AI-managed financial experiences with little friction. The challenge of the future is not to provide a tool, but to redesign experiences to address this transition comprehensively. AI has the potential to resolve the technological debt involved in migrating traditional banks, which have historically struggled the most with this transition.
The second reason is the technical debt banks have demonstrated in dealing with change. This has also occurred in other industries, but the idea of paying for a premium license for every employee and expecting immediate returns only leads to frustration. There is significant resistance when it becomes clear that certain tasks and workflows will inevitably be different from what has been established. In the Middle East, where several national banks have invested heavily in core banking modernization programs over the past decade, the foundations are more favorable than in many Western markets, but the final leap from modernized infrastructure to genuinely agentic deployment still requires focused capability and deliberate execution.
The third reason is regulation. Technology companies, banks, and authorities will need to maintain an ongoing dialogue to ensure that innovation and integrations do not affect users’ personal data or security, while ensuring that restrictions do not become a barrier to progress. One of the most valuable lessons from the banking sector’s legacy is the importance of being extremely careful when dealing with something as sensitive as people’s money.
For many years, the impact of AI was often explained as something that belonged to a distant future. In the financial sector, it is already a reality: it is part of multiple tasks and is beginning to become an asset in the customer proposition. With AI Agents, innovation can no longer, and should no longer, go unnoticed. New habits require the redesign of customer journeys, and this could represent a revolution for the sector. For Middle East banks, the opportunity is particularly compelling: a region where government will, consumer readiness, regulatory pragmatism, and institutional investment have aligned at the same moment. What is required now is the execution capability to convert that alignment into production-grade deployment. What is at stake is no small matter: the management of millions of people’s money and a battle for the competitiveness of banks on a scale rarely seen before. For those that move with urgency and discipline, the financial black swan is a transformation to be led.
by Professor Hind Zantout, Programme Director, MSc Data Science, School of Mathematical and Computer Sciences, Heriot-Watt University Dubai
Women today have jobs across all sectors of the economy, and they are increasingly achieving breakthroughs as entrepreneurs, and progressing to running successful businesses in the UAE, the wider region and globally. The GEM 2025/2026 Women’s Entrepreneurship Report indicates that they represent 45% of founders of startups worldwide. Whilst this figure is promising, women still face obstacles and challenges down the line, as they face challenges in scaling their businesses. But the overall picture remains bright, from creative chocolate concepts, to beauty products to retail and cybersecurity, there are many stories of achievement and success to tell about women entrepreneurs.
The dominant theme that has been disrupting established organisations and providing opportunities for small organisations and start-ups for over 25 years has been computer and communication technology and software systems that deliver the needed functionality. The firstborn in that generation was the Internet, dramatically changing how and where buying and selling can happen, and e-commerce helped women, especially in developing countries, sell their goods.
Today this is further simplified, bypassing the need for a dedicated website that can be replaced by a much cheaper social media presence, hence the term social commerce. Traditional AI has been around for a very long time, but in that generation, it matured into a reliable technology capable of leveraging huge amounts of data. One example is using customer data to predict when an aeroplane engine is about to fail, so it can be serviced before the failure occurs, reducing the cost of time and money for maintenance. Models can also predict customer churn, for example in a telecom subscription environment, so companies can take action to prevent it. The Internet itself evolved into a huge and valuable source of information which then got exploited using large language models to deliver generative artificial intelligence (AI) again causing further disruption but opportunities as well.
Technology advances also facilitated innovations that impacted the monetary system for payments, with fintech and cryptocurrencies. So, the scene is one of increased complexity, evolving opportunities and challenges that need to be addressed. Looking at students enrolled in STEM programs for the region, female students have had a healthy participation for many years now, especially in computer science programs. Courses there often include data science and artificial intelligence, so when the next generation of entrepreneurs is considered that have a university degree, there is no shortage of women with strong relevant skills which are essential for an entrepreneur to appreciate the capabilities of technology but also the pitfalls.
For many businesses, the customer experience is an essential part of the business model and ensuring a positive one is critical. Up until recently, human agents, often supported by computer systems, were typically in charge of ensuring customer satisfaction that leads to customer loyalty. With recent technological advances such as generative AI, chatbots have seen a dramatic transformation in their ability, and they can now hold almost human-like conversations with the customer, but these still remain restricted to limited scenarios. Their implementation in customer-facing processes is not completely risk free and could lead to a frustrated customer who cannot have a query responded to or their problem resolved. An expanding landscape of technologies now features AI agents and the promise of offering the needed additional capability. And with such an accelerated pace of change, with the potential to continually proliferate and transform many business processes, it is essential that business leaders not only to have an understanding of what can be delivered, but also the risks that need to be mitigated.
Traditional customer relationship management puts the emphasis on tracking the customer lifecycle from marketing to sales through to customer service. But in an ecosystem offering a diversity of channels that a customer can engage with, it is essential to manage the whole customer experience (CX), tracking and measuring all interactions, not just the purchase of a product or service. For example, virtual fitting rooms are built on augmented reality / virtual reality platforms and can be one channel in retail, where the customer can superimpose the image of a piece of clothing over an image of themselves before making the purchase decision. A customer can also see how a sofa they are considering would appear in their living room. Such a personalised shopping experience can be valuable, as studies show a reduction in returns, around 25% – 40%. There is, however, a real danger that hyper-personalisation, where every interaction is logged, analysed and exploited, will lead to the customer feeling under surveillance.
For example, using a customer’s browsing history to make recommendations and offers will spook many, with the realisation that every online click was tracked. This sets off the so-called creep factor and customers then abruptly switch away from that product or service. A fine balance needs to be struck to bridge the personalisation-privacy paradox, not just to keep customers loyal, but also to avoid litigation. In the US, Neutrogena and Charlotte Tilbury faced separate class actions that were settled with a payout. The allegations were that the tools used processed user data that may include biometric data.
And any deployment of AI will have to give careful consideration to the risk of bias in the algorithms. As a result of using biased training data, some groups may be over-represented while other groups may be under-represented, leading to unfair treatment of customers. The impact can be wide-ranging, from missed revenue to developing flawed marketing strategies, to customers losing trust in a product or service.
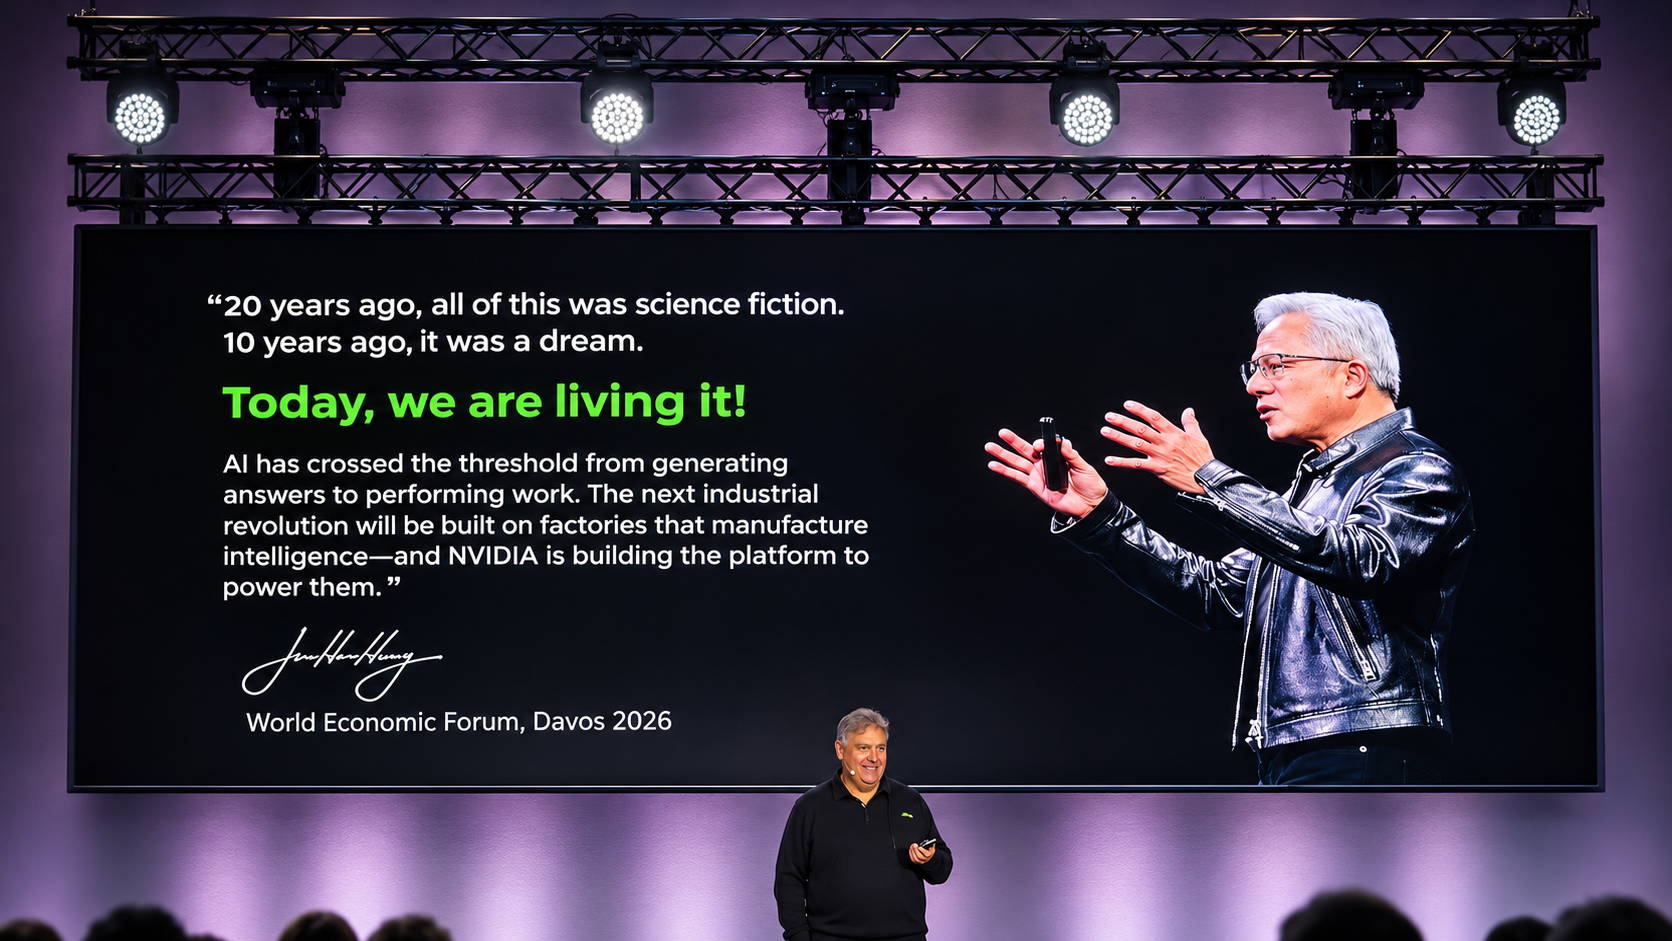
There is something almost ironic here. A company that helped persuade the world AI could reduce dependence on human judgment now faces one of its biggest uncertainties because of one human being.

By: Srijith KN, Technology Integrator
On November 12, Nvidia announced that Jensen Huang had resigned as CEO and director, with CFO Colette Kress assuming the role on an interim basis. His departure followed reports involving personal relationships and possible national security concerns. Allegations of foreign intelligence connections remain unproven. In a statement on November 8, Nvidia’s board said it had no reason to believe company secrets or national security were compromised and had initiated an independent investigation.
But the bigger story is what happens to the AI empire he built.
At a recent infrastructure conference in Croatia, an Nvidia executive jokingly introduced himself as the cheaper alternative to “my boss Jensen,” adding that he only needed the leather jacket. A funny remark, but also revealing. Huang had become more than a CEO. He was the personality behind Nvidia’s extraordinary rise.
Five issues now deserve attention.
Governance. Huang led Nvidia for 33 years as strategist, dealmaker and chief evangelist. Investors understood the value of Nvidia’s technology. What remains uncertain is how much of that value depended on the vision, relationships and influence of one individual. The question now is whether Nvidia has built the institutional strength to carry that legacy forward.
Strategy. Huang’s ambition extended far beyond GPUs. His five-layer AI framework, encompassing energy, chips, infrastructure, models and applications, envisioned an entire computing economy. The opportunity was never simply about selling processors. It was about shaping the foundations upon which the next generation of technology would operate. That vision now needs leadership capable of carrying it forward.
AI sovereignty. Perhaps Huang’s most consequential message was directed at governments. According to the Nvidia executive in Croatia, Huang routinely asks presidents and prime ministers whether their countries want to become AI “takers” or AI “makers.”
Every nation will consume AI. But those developing their own infrastructure, models and capabilities could exercise greater control over their digital futures. The executive described Huang’s support for open architectures, deployable under national laws and data requirements, as making this a geopolitical conversation, not merely a technology discussion.
Geopolitics. Huang advocated maintaining access to the Chinese market for advanced chips. His departure removes an influential voice from that debate, amid continued scrutiny of chip exports.
Economics. Nvidia’s investments in AI companies that also purchase its computing infrastructure have added another dimension to the debate over AI economics. The real question is whether the revenues generated across this ecosystem can ultimately justify the extraordinary capital flowing into it.
None of this means Nvidia’s technology advantage has disappeared. Its engineering talent, software ecosystem and customer relationships remain formidable. The board has also expressed confidence that its leadership team can continue executing the company’s technology roadmap without interruption.
But perhaps the AI industry is entering a different chapter, where governance matters more than charisma and profitability matters more than promises.
For enterprises, the lesson is simple. Never build an AI strategy around one vendor, one chip or one personality.
Technology is only as strong as the judgment guiding it.
The real test now is whether Nvidia can demonstrate that its future is bigger than the man who built it.
BY SRIJITH KN & SUBRATO BASU

As AI spending rises and experimentation gives way to accountability, the real challenge for business leaders is no longer access to technology, but proving value, controlling cost and redesigning how organisations work.
Every year, the technology industry promises a breakthrough that will change everything. New models arrive, computing capacity expands and investment reaches new highs. Then, somewhere between the product demonstration and the quarterly earnings call, someone asks the question that matters most:
What did all of this actually improve?
That question came into sharper focus in 2026.
Artificial intelligence moved deeper into everyday business. Companies deployed assistants, experimented with agents and embedded AI across customer service, software development, compliance, finance and operations.
Yet adoption turned out to be the easy part.
Installing an AI assistant is relatively straightforward. Redesigning an organisation around it is not.
Fragmented systems, poor-quality data, unclear ownership, weak governance and sceptical employees do not disappear because a company has purchased another software licence.
Businesses do not need another year of impressive demonstrations. They need to know whether AI is helping them make better decisions, serve customers more effectively and run their operations more reliably.
That shift is turning AI from primarily a technology question into a management one.
From experimentation to accountability
The adoption numbers appear impressive.
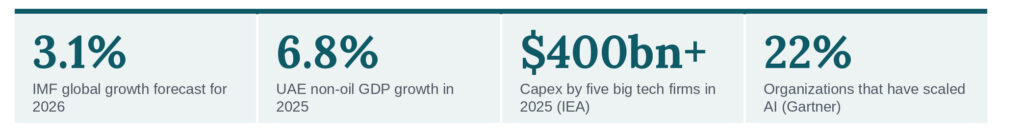
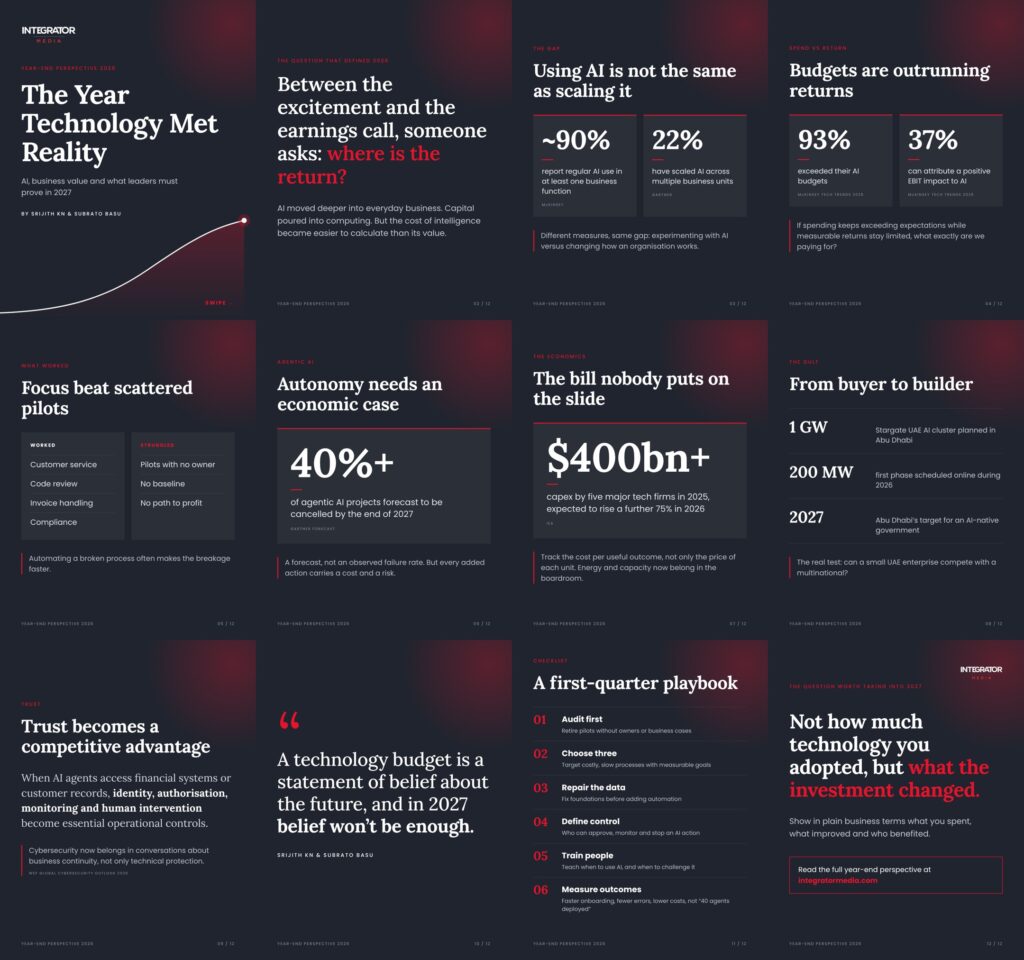
McKinsey found that nearly nine in ten survey respondents reported regular organisational use of AI in at least one business function. Gartner, using a different measure, found that only 22% of organisations had successfully scaled AI across multiple business units or adopted an AI-first approach.
The methodologies are different, but together they point to an important distinction: using AI is not the same as changing how a business operates.
The economics reinforce that concern.
In McKinsey’s Technology Trends Outlook 2026, one survey found that 93% of respondents had exceeded their AI budgets. Another found that only 37% of companies could attribute a positive EBIT impact to their AI programmes.
Those numbers create an uncomfortable boardroom question.
If spending continues to exceed expectations while measurable returns remain limited, what exactly are organisations paying for?
The clearest returns are likely to emerge where companies begin with a defined business problem: reducing customer-service resolution time, accelerating code review, simplifying invoice handling or strengthening compliance.
What becomes harder to justify is the proliferation of pilots with no accountable owner, no performance baseline and no clear route to economic value.
Automating a broken process can simply make the breakage happen faster.
Agentic AI raises the stakes
Agentic AI made this management challenge more significant in 2026.
Traditional generative AI largely responded to requests. Agents can increasingly perform multistep activities, interact with systems and execute actions.
That creates more opportunity, but it also introduces more cost, operational risk and responsibility.
Gartner has forecast that more than 40% of agentic AI projects will be cancelled by the end of 2027 because of escalating costs, unclear business value and inadequate risk controls.
It is a forecast rather than an observed failure rate, but the warning matters.
Giving software more autonomy only increases the need for organisations to define who owns the outcome, who monitors the process and who can intervene when something goes wrong.
The question for leaders is therefore becoming less about what an AI agent can do and more about what the organisation should allow it to do.
The economics nobody puts on the slide
AI is also forcing companies to think differently about technology costs.
The International Energy Agency reported that capital expenditure by five major technology companies exceeded $400 billion in 2025 and was expected to rise by another 75% in 2026.
The physical foundations of AI require enormous amounts of computing infrastructure, electricity, cooling, networking, land, semiconductors and highly specialised talent.
An individual AI task may become cheaper while the total technology bill continues to grow simply because usage expands.
That is not necessarily a problem if the additional activity creates measurable value.
But somebody needs to be able to explain what the extra expenditure produced.
Did it generate more revenue?
Did customers receive better service?
Did employees become more productive?
Did the organisation reduce risk?
Technology and finance leaders increasingly need to measure the cost per useful outcome, rather than concentrating only on the price of individual models, tokens or software licences.
Energy, computing capacity and infrastructure resilience now belong in the same boardroom conversation as digital transformation.
AI also creates a wider economic question
There is another issue that sits beyond corporate productivity.
A business may be able to reduce certain labour requirements through automation, but an economy still depends on people earning, consuming, creating businesses and paying taxes.
If productivity gains do not translate into new industries, new forms of employment or greater economic opportunity, the benefits become harder to sustain.
Reskilling cannot therefore be treated simply as a corporate social-responsibility programme.
It increasingly belongs at the centre of technology strategy.
The real measure of intelligent technology should not be how many jobs it eliminates or how many tasks it completes. It should be whether it creates durable value for enterprises while expanding economic opportunity around them.
The Gulf moves from technology buyer to builder
This is particularly relevant in the Gulf.
For years, the region was often described primarily as a major buyer of global technology. That description increasingly feels incomplete.
Across the UAE, Saudi Arabia and the wider Gulf, governments and businesses are investing in AI infrastructure, cloud capacity, digital government, data centres and technology ecosystems.
Stargate UAE, the planned one-gigawatt AI infrastructure cluster in Abu Dhabi, illustrates the scale of that ambition. Its first 200 megawatts were scheduled to come online during 2026.
Abu Dhabi’s ambition to build an AI-native government by 2027 and Dubai’s support for digital entrepreneurship point in the same direction.
But infrastructure alone does not create prosperity.
The more important question is whether that infrastructure lowers the cost of innovation and makes advanced technology accessible to the companies that drive the region’s everyday economy.
Can a UAE SME use AI to compete more effectively with a multinational?
Can a local healthcare provider deploy specialised intelligence without building an enormous internal technology operation?
Can a logistics company use automation to improve reliability rather than simply add another layer of software?
The Gulf has invested heavily in technological ambition. The next chapter will be about making that ambition useful.
That means moving from importing technology to developing capabilities, intellectual property, businesses and talent around it.
Innovation moves into the physical world
The technology conversation is also becoming broader than generative AI.
Physical AI is bringing intelligence into robotics, logistics, manufacturing, healthcare and mobility.
Digital twins, edge computing and intelligent energy systems are connecting digital decisions to physical operations. Smaller, specialised AI models may also offer better economics and governance than enormous general-purpose systems for narrowly defined industry tasks.
Quantum computing continues to advance, although business leaders should remain cautious about claims of immediate universal commercial impact.
The more urgent issue for many organisations is post-quantum cybersecurity.
Confidential information protected today could potentially become vulnerable as computing capabilities evolve, meaning organisations handling long-lived sensitive data need to begin thinking about cryptographic resilience well before large-scale quantum computing arrives.
Across these technologies, the competitive advantage is unlikely to come from collecting the greatest number of tools.
It will come from integrating the right technologies into an operation that works.
Trust becomes part of the business model
As AI systems gain access to more sensitive information and perform more consequential activities, cybersecurity becomes inseparable from business strategy.
The World Economic Forum’s Global Cybersecurity Outlook 2026 described an environment shaped by AI-enabled threats, geopolitical fragmentation and uneven cyber resilience.
AI agents interacting with financial systems, customer information or operational infrastructure raise the importance of identity controls, authorisation, monitoring and human intervention.
Cybersecurity can therefore no longer be treated simply as the responsibility of the security department.
It is increasingly about business continuity, reputation and customer trust.
The companies that can demonstrate that intelligent systems are secure, explainable and accountable may find that trust becomes a genuine competitive advantage.
2027: the numbers will have to add up
If 2026 was the year organisations experimented with how far AI could go, 2027 is likely to bring much tougher questions about whether those investments make economic sense.
A good demonstration will matter less than what a company can responsibly allow a system to do.
Agents will begin taking responsibility for defined activities, but each will require boundaries, monitoring and a human being who ultimately owns the consequences.
Boardroom conversations should shift from:
- How many AI tools have we deployed?
- to:
- What does this process cost now?
- How much faster is it?
- Has the error rate fallen?
- Are customers noticing the difference?
That scrutiny will extend beneath the software layer.
Energy availability, sovereign computing capacity, regulatory requirements and infrastructure resilience will increasingly influence where companies choose to invest.
The same scrutiny will reach the workforce.
Employees will need technical fluency, but they will also need business judgement: the ability to understand exceptions, question automated recommendations and take responsibility when systems get something wrong.
Access to another AI model will not be the defining advantage.
An organisation that operates better — at a cost that survives examination — will be.
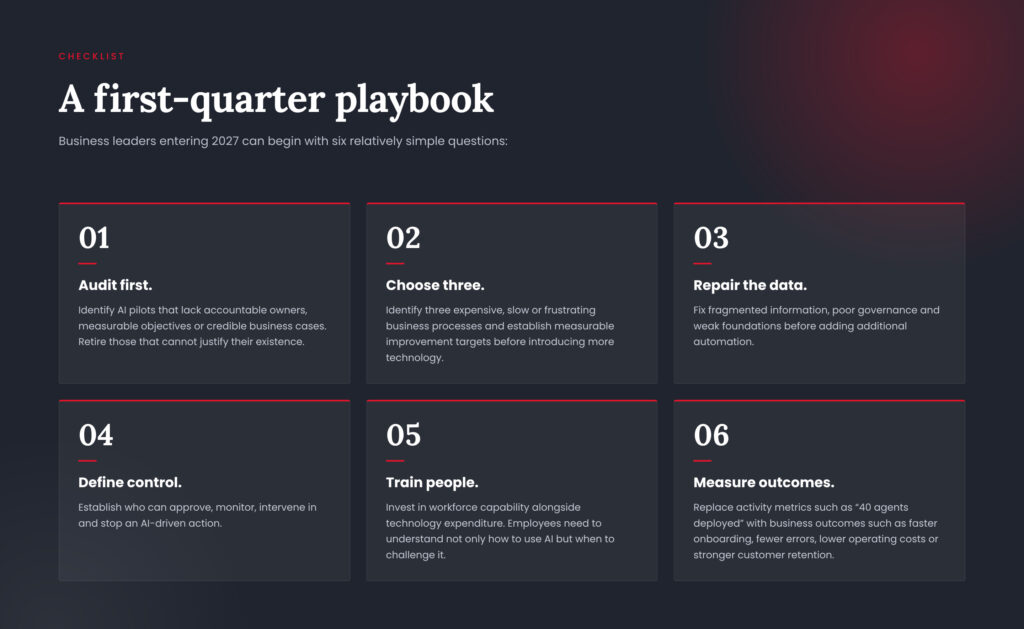
The question worth taking into 2027
As 2026 closes, business leaders should temporarily set aside the question of how much technology their organisations have adopted.
Instead, ask what the investment actually changed.
Did serving a customer become simpler?
Did an expensive process become more efficient without becoming less reliable?
Did employees gain the ability to spend more time on valuable work?
Can the improvement be seen in the numbers?
A technology budget is ultimately a statement of belief about the future.
In 2027, belief will not be enough.
AI adoption alone will no longer be impressive. The organisations that stand out will be those that can explain, in plain business terms, what they spent, what improved and who benefited.
And that may be the clearest indication yet that AI is becoming less of a technology problem — and much more of a management one.
Subrato Basu is an author, adviser and speaker on AI strategy and technology cost management. With nearly three decades of experience advising C-suite leaders, he helps organisations across North America, Asia Pacific and the Middle East turn technology investment into measurable business value.
Srijith KN is Senior Editor at Integrator Media, who is hands-on in covering enterprise technology, artificial intelligence, cybersecurity and the digital economy across the Middle East.

Quality First: Why Great Products Start With Better Ingredients
Your Ultimate #FestiveGiftGuide: Consider This Your Festive Cheat Sheet

Women Entrepreneurs in the Age of AI: Opportunities, Innovation and New Challenges

OPPO A6 Pro 5G Review: Reliable Daily Driver

Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer

Microsoft Launches New Surface Copilot+ PCs for Business

2026 in Review: Is AI Becoming More of a Management Problem Than a Technology Problem?

Inside XPENG Brand Night: AI Mobility Lands Centre Stage in Dubai

Chinese Cars Are Reshaping the GCC Market, but Resale Value Could Be the Next Battleground
-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-
 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
News4 years ago
BenQ ZOWIE : First TN 360Hz DyAc+ Gaming Monitor