 Have a question? +971 56 404 0503

Financial
Beyond the Funding Round: Building the Financial Foundations for MENA Startups to Scale

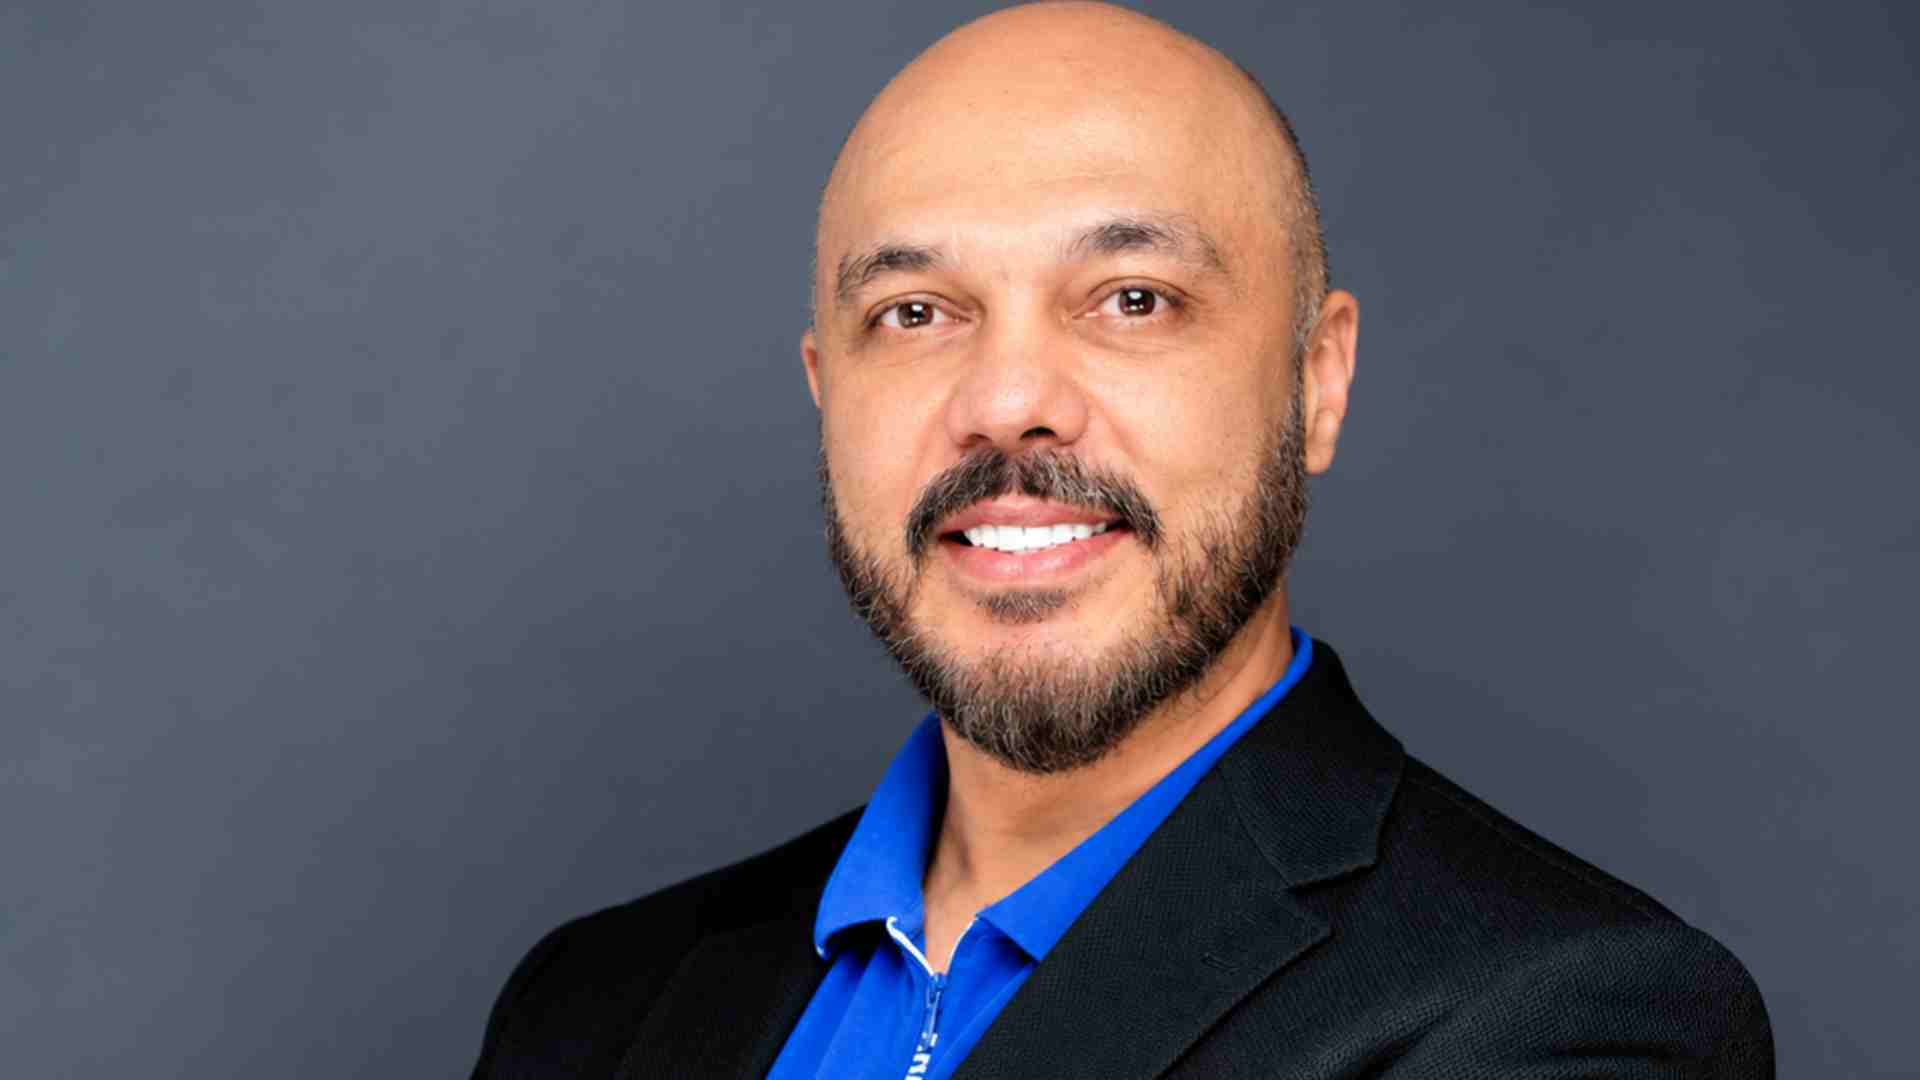
Exclusive Interview with Nasir Khan, Co-Founder, Synovo
The MENA startup ecosystem is shifting from growth at all costs to sustainable business models. What has changed, and what does it take to build a financially resilient startup from the outset?
I think the biggest change is that investors have become less willing to finance a business model indefinitely while founders work out the economics. A few years ago, a compelling growth story could carry a lot of weight. Today, people want to know what each additional customer costs, when that customer becomes profitable and how much cash the company needs to get there.
For me, resilience starts with knowing the difference between revenue, profit and cash. Having worked across telecom distribution, factoring and healthcare ventures, I’ve seen businesses look healthy on paper while working capital quietly becomes their biggest problem.
My advice is to start small enough to test your assumptions, know your margins well and build a business that can survive a slow month, not just celebrate a good one.
Raising capital is only one step towards building a successful business. What financial mistakes do startups commonly make after securing investment, and how can they avoid them?
The most common mistake is treating money in the bank as proof that the business has succeeded. Suddenly there is a bigger office, a larger team and three new markets on the roadmap, before the original model has really been proven. Fixed costs rise quickly, and reversing them is much harder.
I prefer to see founders tie each stage of spending to a milestone: demonstrating repeat purchases, shortening the sales cycle, improving gross margin or reaching a defined number of paying customers.
I’d also keep a fallback plan in case the next round takes twice as long as expected. Fundraising buys time, but what matters is what you prove during that time.
Drawing on your experience in structured finance, how should MENA founders choose between equity, debt and other financing options at different stages of growth?
I spent years in factoring and structured finance, and one lesson has stayed with me: match the type of financing to the risk you are financing.
Equity makes sense when the product, market or revenue model is still uncertain, because investors are sharing the risk of finding out whether the business works. Debt is better suited to predictable cash flows or identifiable assets. Once a business has reliable receivables, trade finance or factoring can fund working capital without giving away more ownership.
But debt is not a cure for an unprofitable business. It creates a payment obligation whether the next contract arrives or not. Founders should also watch for currency mismatches and personal guarantees. The cheapest-looking capital is not always the safest.
Access to capital varies across MENA markets. How should founders in emerging startup hubs approach financial planning differently from those in established ecosystems such as the UAE and Saudi Arabia?
First, I would resist treating MENA as a single market. Access to investors is only one difference. Collection cycles, currency exposure, regulation, customer purchasing power and the availability of experienced hires all change from country to country.
In a smaller funding ecosystem, I would plan for a longer fundraising process and keep costs as variable as possible. A local commercial partnership is often more useful early on than opening a fully staffed operation.
Even in the UAE or Saudi Arabia, access to capital does not mean every startup is fundable. Founders still have to show that they understand their own market. Expansion should follow customer evidence, not a regional map in a pitch deck.
Cash flow is critical to a startup’s survival. Which financial metrics should founders monitor, and how can they maintain cash flow discipline while pursuing growth?
I would start with five things: cash in the bank, monthly net burn, runway, gross margin and the time between invoicing a customer and actually collecting the money.
For subscription businesses, retention and customer acquisition cost matter enormously. For businesses selling to corporates or governments, receivables ageing can be just as important as revenue growth.
A simple weekly cash forecast looking 13 weeks ahead can prevent a lot of unpleasant surprises. I also like a monthly downside scenario: what happens if collections are delayed, or sales come in 25% below plan?
These are not glamorous exercises, but I’ve seen how quickly a growing business can run into trouble when sales rise faster than the cash needed to deliver them.
What makes a startup truly investor-ready today, particularly in terms of financial reporting, governance, unit economics and operational discipline?
Investor readiness is not a beautiful data room put together two weeks before a meeting. It is the discipline with which the business has been run over the previous year.
Can the founder explain the margin on a customer? Reconcile revenue to cash received? Show who owns the company, what obligations exist and which assumptions sit behind the forecast? Do they know how much of their revenue depends on a handful of customers?
In healthcare ventures such as Synovo, which I co-founded, financial planning also has to reflect clinical evidence, regulatory requirements and hospital procurement cycles. Ignore those realities and even an attractive forecast becomes meaningless.
Investors understand that early-stage businesses will not have perfect systems. What worries them is when founders cannot explain their numbers or become defensive when challenged. Being candid about risks usually strengthens investor confidence rather than weakening it.
How can MENA founders balance growth with profitability and reduce dependence on repeated funding rounds? When should they rethink their strategy if new investment fails to materialise?
Profitability does not need to arrive on day one, but the route to it should be visible. The test I use is whether growth improves the economics or simply increases the losses. If every new customer makes the funding gap bigger, scale is not solving the problem.
I would review the plan well before the runway becomes critical. If investment is uncertain, narrow the product range, protect the best customers, reduce fixed commitments and concentrate on revenue that turns into cash.
Sometimes a smaller, profitable core is the right foundation for a much larger company. Waiting until the last three months of cash to make those decisions usually leaves very few good options.
Through your involvement with the London Business School MENA Startup Competition, what distinguishes genuinely scalable startups from those with compelling pitches, and what will define the next generation of successful MENA businesses?
The competition reminded me that a polished pitch and a scalable business are two different things. The founders who caught my attention were not necessarily the ones with the grandest projections. They were the ones who could explain what customers had actually done, what they had learned from being wrong and what the next round of capital would achieve.
Our shortlisted teams were mentored by LBS alumni and volunteers, and it was encouraging to see founders willing to challenge their own assumptions rather than defend them.
I think the next generation of strong MENA businesses will combine regional ambition with local execution, sensible capital structures and the ability to earn customer trust.
Winning a competition can open doors. What founders build after the applause is what ultimately counts.
Dr. Nasir Khan is a medical doctor, entrepreneur and Sloan Fellow from London Business School. He has been building businesses since 2001 across telecom distribution, financial services, medtech and process manufacturing, and has co-founded ventures including Synovo, a UK-based digital health platform. He has also served as a judge for startup induction at the Punjab Information Technology Board’s incubation programme in Lahore and is Co-President of the LBS Entrepreneurship Club, MENA.
Financial
Connecting Industries and Trade: Malakut Business Forum 2026 Brings Together 750+ Delegates and 300+ Companies
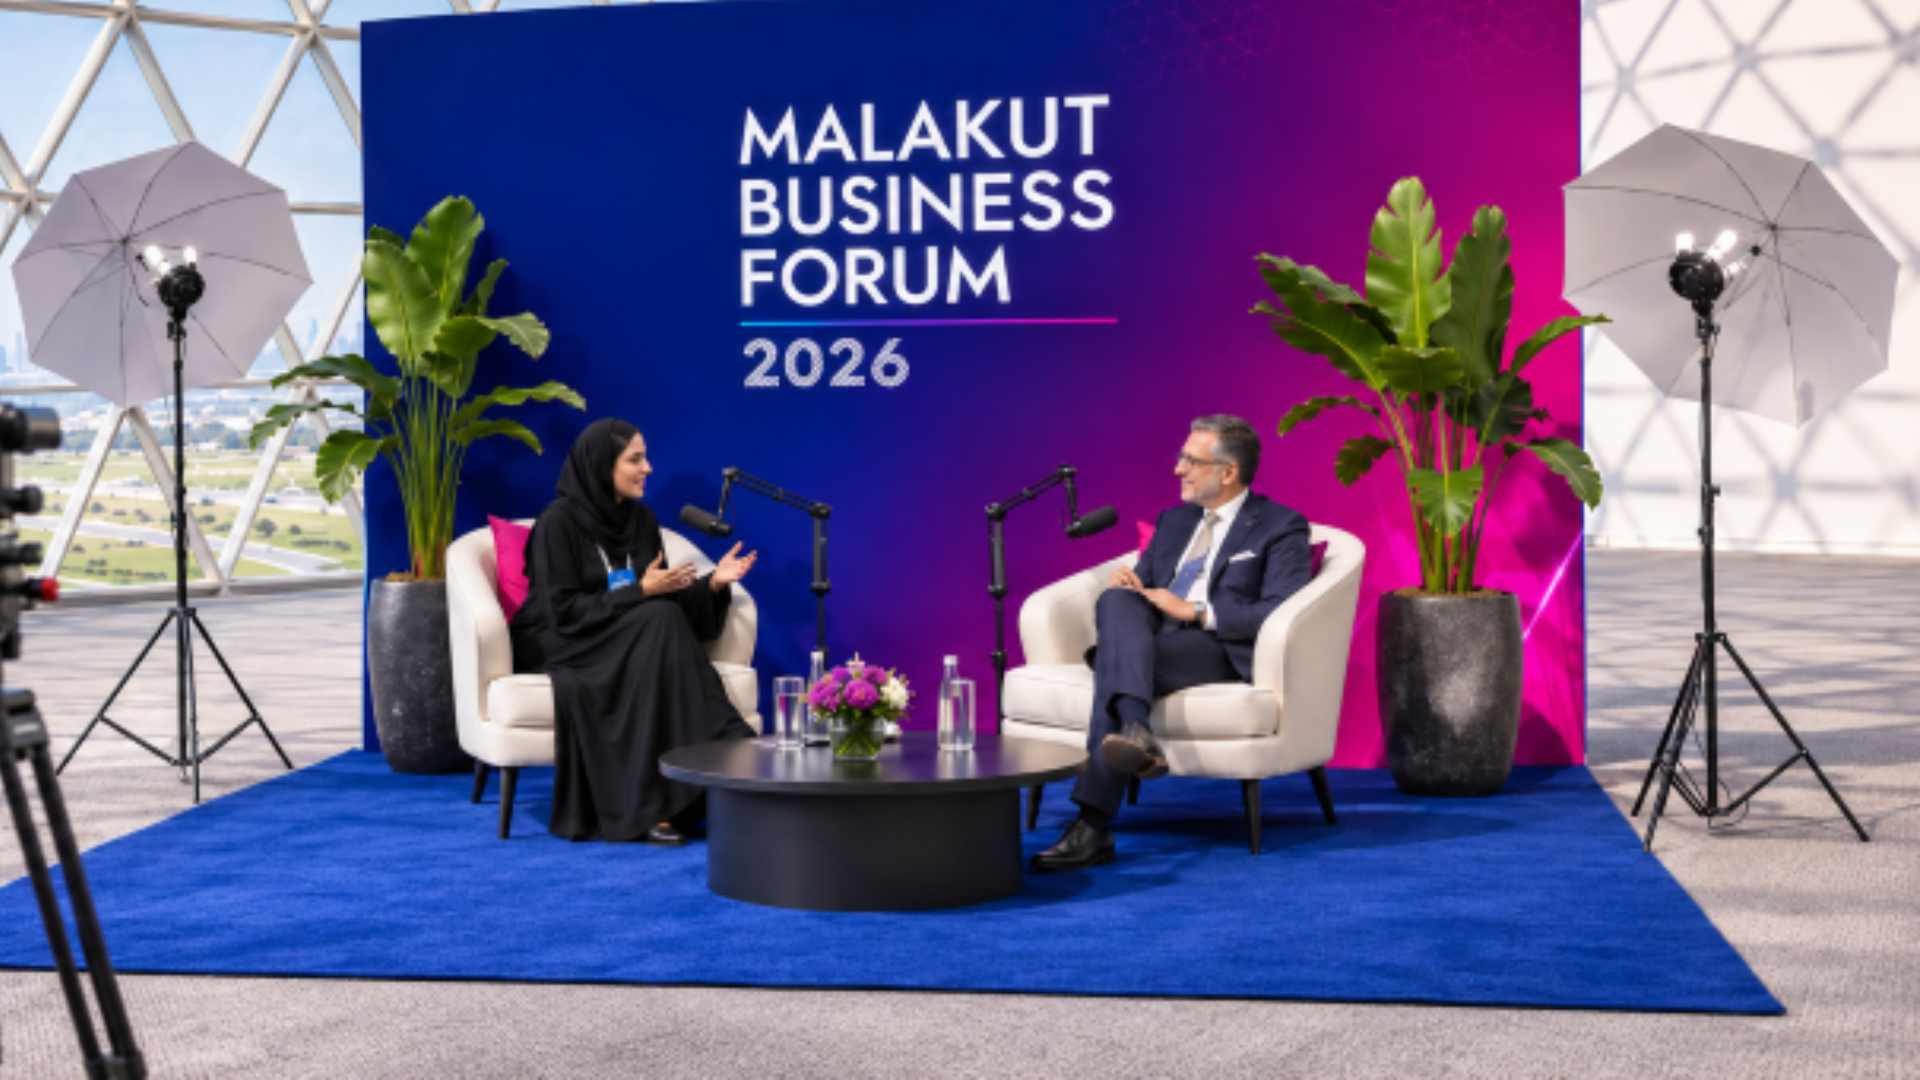
The Malakut Business Forum 2026 is set to bring more than 750 delegates and over 300 companies together at Sky Bubble, Meydan Hotel, Dubai, on 25 November 2026, with C-suite executives and directors accounting for 60 per cent of attendees.
The one-day forum will convene senior leaders from banking, trade, insurance, logistics and industry across five streams: Finance, Risk, Artificial Intelligence, Logistics and Technology.
The 2026 edition builds on the success of the inaugural forum with even greater scale and a more focused agenda. Organisers are lining up more than 25 industry speakers and over 20 partners, with a projected digital reach of 200,000+ online users, providing even more opportunities for partners to connect, engage and be seen. The key topics to be explored during this edition include business resilience, geopolitical challenges, innovation and the future of global trade.
“Business leaders are making critical decisions under pressure, across borders and with less certainty than ever. The Malakut Business Forum was created to bring the right people into the same room, so decisions are better informed and conversations turn into real opportunities. Our 2026 edition is bigger, bolder and built for impact, and we are proud to host it in Dubai, a global crossroads of trade,” said Alex Dolgopolov, CEO of Malakut, the Founding Partner of Malakut Business Forum 2026
The programme is built around real cases and candid discussion. Finance sessions will examine how companies protect liquidity under pressure and turn high-risk projects into bankable ones. The Risk stream will address securing political violence and war risk cover during active conflict, and what businesses can do when the insurance market will not take the risk. Artificial Intelligence sessions will look at AI savings that reached the P&L, the move from copilots to agents and what leaders refuse to automate. Logistics will tackle rerouting during conflicts and the question of who pays for resilience, while Technology will cover scaling across fragmented markets and modernising core systems without disrupting daily operations.
Beyond the main stage, delegates can expect a networking reception, a partner showcase, a live podcast studio, VIP hospitality and an evening cocktail and dinner experience. Private Skyboxes overlooking the Meydan race track will offer partners an exclusive setting for high-value meetings with clients, prospects and partners.
Imagine a business that pays an overseas supplier in stablecoins. The transfer is confirmed within minutes, but the supplier cannot access the funds in the currency needed to fulfil the order. A bank review holds up the conversion, the delivery date approaches, and neither party knows how long the delay will last.
The payment has worked as a blockchain transaction. As a business transaction, however, it has fallen short.
This distinction matters as stablecoins gain attention as a more efficient way to move money internationally. They offer genuine advantages, including faster settlement and the potential to reduce transfer costs. But businesses do not adopt payment methods simply because the technology works. They need to know that money will arrive when expected, that recipients can use it, and that problems can be resolved without leaving both parties in limbo.
For stablecoins to become a practical part of global commerce, the industry must address the parts of a payment journey that technology alone cannot fix.
The Real Cost Is More Than the Transfer Fee
Sending money across borders remains expensive, despite years of investment in digital payments. World Bank data puts the global average cost of remittances at approximately 6.36% per US$100, down from 8.89% in 2010. Progress has been uneven, with established corridors such as the UAE–India and US–Mexico benefiting from more developed financial networks, while some routes serving Africa, Latin America and Southeast Asia continue to face higher costs.
The UAE illustrates why this matters. With expatriates accounting for around 88% of its population, the country is a major centre for international remittances, particularly to South Asia. Improvements in payment infrastructure have implications not only for individuals sending money home but also for companies paying suppliers, contractors and employees abroad.
Stablecoins could help reduce some of the friction involved. Yet headline transaction volumes can obscure how much progress has actually been made in everyday payments. The $8.82 trillion in stablecoin transaction volume cited for the first half of 2026 includes activity that is not necessarily linked to purchasing goods, paying suppliers or settling commercial invoices. Estimates of real-world stablecoin payment activity, at approximately $390 billion, offer a different perspective on adoption.
The distinction is important. Moving a digital asset between wallets is not the same as completing a payment that meets a business’s commercial needs. The latter requires the entire process, from funding and settlement to conversion, reconciliation and confirmation, to work reliably.
Businesses Need Someone to Turn to When Payments Fail
Conventional payment systems have plenty of shortcomings, but businesses generally operate within established arrangements for investigating failed transfers, handling refunds and determining who is responsible for a loss. Stablecoin payments introduce a different set of participants and processes, and responsibility can become less clear when something goes wrong.
A cross-border transaction might involve a stablecoin issuer, a payment provider, an exchange and one or more banks. Each may have its own compliance obligations, operating procedures and timelines. A transaction can settle on-chain while remaining inaccessible to its intended recipient because a bank review, liquidity issue or other operational problem interrupts the next stage.
For a business, the consequences are tangible. A supplier may delay an order, a shipment may miss its window, or a contractual payment deadline may be breached. The savings achieved through faster settlement can quickly lose their value if the business cannot predict when the recipient will actually receive usable funds.
This is why dispute handling, refunds, transaction restrictions and clear escalation procedures need to be considered from the outset. A system designed for commercial use cannot rely on the assumption that every transaction will proceed as intended.
There is room for infrastructure that brings together blockchain-based payments and familiar financial risk controls. Such systems could help coordinate transaction monitoring, counterparty checks and the handling of disputed or interrupted payments.
The objective is not to recreate every layer of traditional banking, but to give businesses a clear process and an accountable party when a payment requires intervention.
International Payments Need International Coordination
The same issue arises at the regulatory level. A business making payments across several markets should not have to navigate a completely different set of operational expectations at every border.
Europe’s Markets in Crypto-Assets Regulation (MiCA), the US GENIUS Act, and frameworks developed by the UAE’s Virtual Assets Regulatory Authority (VARA) and Central Bank of the UAE (CBUAE) represent important efforts to establish rules for digital assets. However, they differ in their treatment of issuers, reserves, disclosures and permitted activities. Approval in one jurisdiction does not automatically establish acceptance in another.
Information-sharing requirements create another challenge. Where Travel Rule protocols are implemented differently, payment providers may struggle to exchange information about transaction participants consistently. This can introduce friction even when the underlying transfer is technically straightforward.
The answer is not necessarily a single global rulebook.
Countries have different legal systems and regulatory priorities. What the industry needs is greater compatibility between those systems: clearer expectations for cross-border transactions, more consistent information-sharing arrangements and practical ways for compliant providers to operate across jurisdictions.
For businesses, regulatory predictability is part of payment reliability. Companies need to understand the conditions under which funds can be transferred, held or released before committing to a payment method.
The Banking Relationship Still Matters
Stablecoins may change how value moves, but they do not eliminate the need to connect digital assets with conventional money. Businesses still need access to fiat currencies, dependable liquidity and banking services that support their operations.
That connection remains a weakness in parts of the market.
Liquidity can be spread across different issuers and blockchain networks, while some banks have chosen to reduce their exposure to digital asset companies rather than develop services for them.
The broader lesson is that blockchain infrastructure cannot operate in isolation. Its commercial usefulness depends partly on the strength of the institutions and services that connect it to the wider financial system.
Reliability Is What Will Make the Difference
None of this means that compliance controls should be weakened. Stablecoin issuers and payment providers must be able to respond to sanctions requirements, suspicious activity and other legitimate reasons to restrict transactions. But businesses also need transparency about why a payment has been held, what steps are required to resolve the issue and who is responsible for communicating the outcome.
Smart contracts can automate agreed payment conditions, but they cannot independently settle every legal dispute or reconcile conflicting requirements across jurisdictions. Those responsibilities must be addressed through contracts, institutions and operating procedures designed around the realities of cross-border commerce.
The next stage of stablecoin adoption will depend on how well the industry deals with these less visible parts of the payment experience. Better settlement technology is valuable, but it must be matched by dependable banking access, compatible regulatory arrangements and clear responsibility when transactions do not go to plan.
For businesses, the question is not simply whether stablecoins can move money faster. It is whether they can make international payments more predictable, easier to manage and less costly in practice.
That is the standard the industry must meet if stablecoins are to become more than an alternative way to transfer digital value.
(Author Info: Jack Tang is an accomplished fintech entrepreneur, at the intersection of payments infrastructure and digital assets. As Co-founder & CEO of London-based BoomFi, Jack leads the platform’s work in crypto payment infrastructure. He has over ten years of experience in entrepreneurship, building and scaling businesses across consumer and enterprise markets.)Financial
Pay10 Announces Strategic Partnerships at Dubai FinTech Summit 2026, Advancing the UAE’s Digital Payments Ecosystem
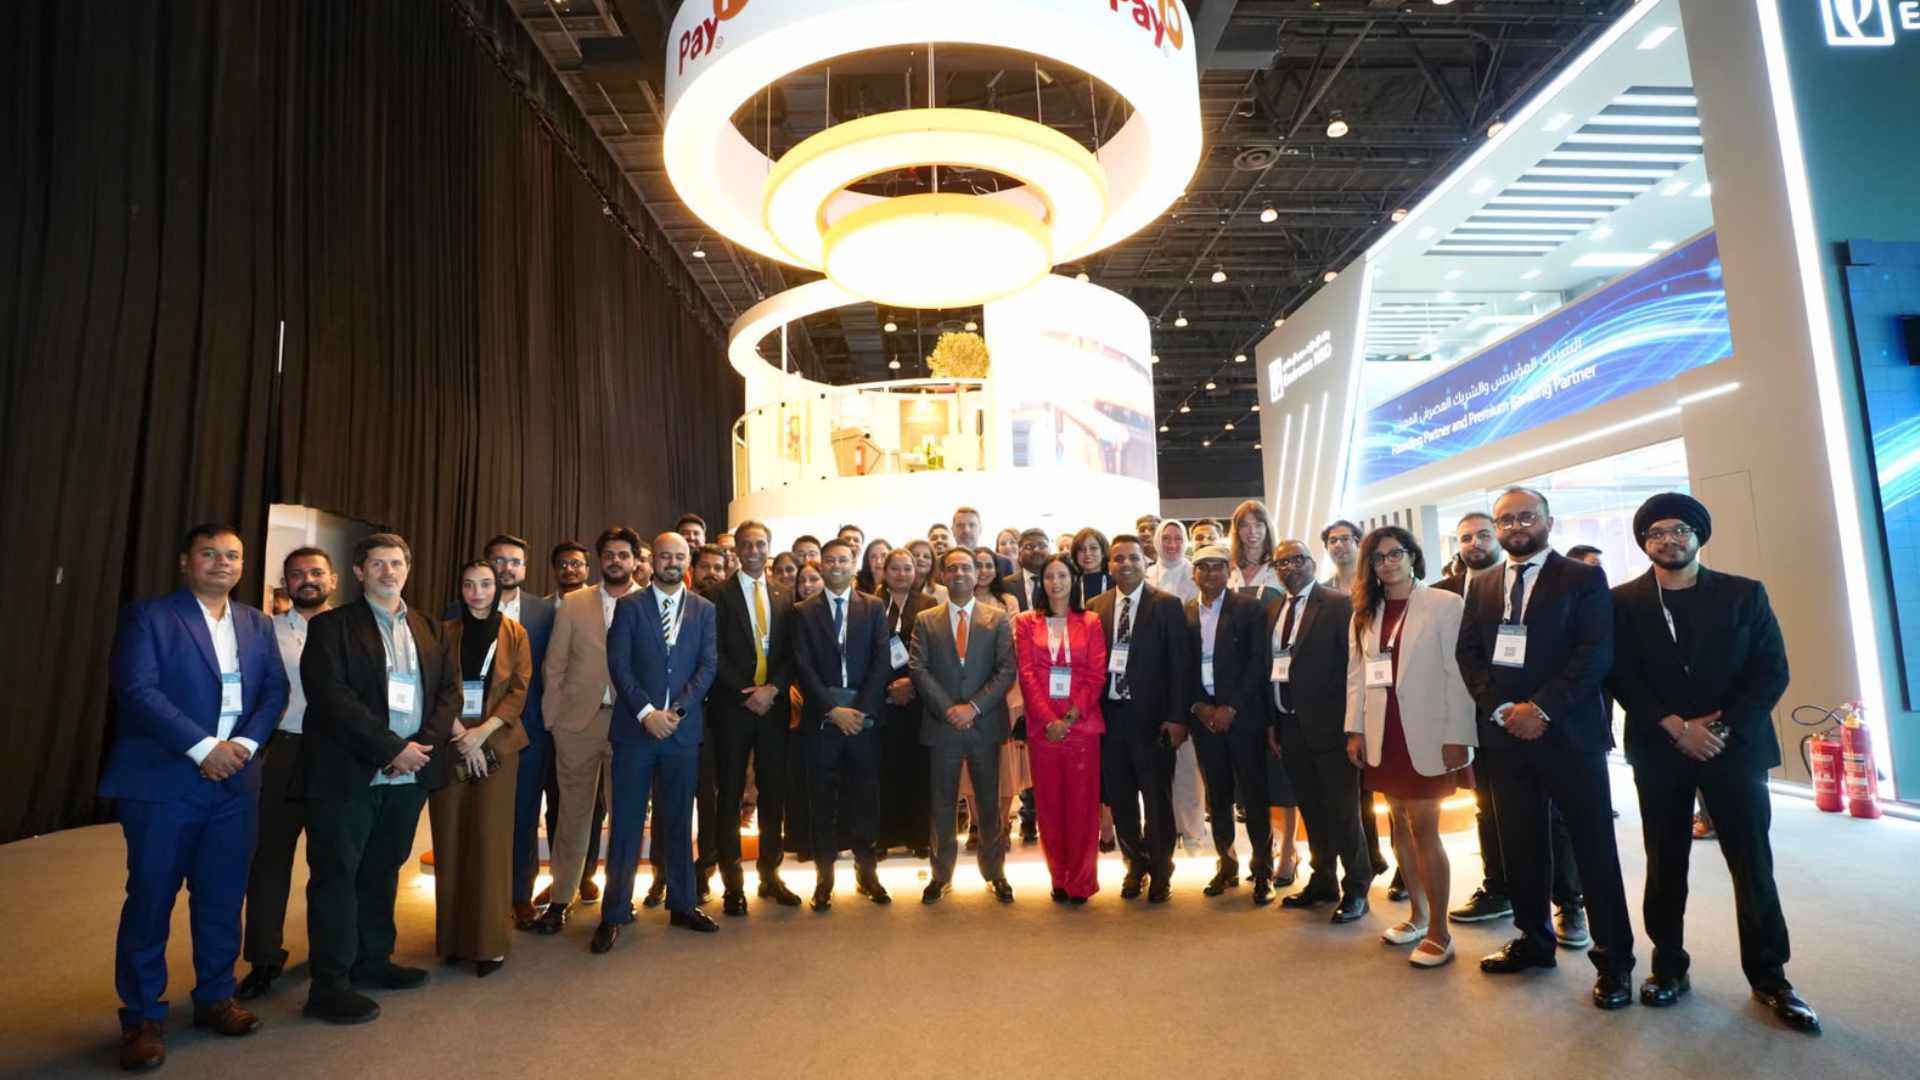
Pay10, a UAE-regulated financial technology company, today announced a series of strategic partnerships, commercial agreements and Memoranda of Understanding (MoUs) at Dubai FinTech Summit 2026. The announcements mark a step towards expanding digital payment choices and supporting the UAE’s transition towards real-time, interoperable and account-based payments, in alignment with the Central Bank of the UAE’s Financial Infrastructure Transformation (FIT) Programme.
Pay10’s partnerships with leading brands, including GEMS, Jumbo Electronics, Bikanervala, Allday, Just Gold and Save In Gold, span education, retail, food and beverage and specialised commerce. With live deployments already in place at GEMS, Bikanervala, Allday and Just Gold, Pay10 is extending its payment ecosystem across everyday consumer and business transactions.
Building a Connected Payments Ecosystem
Pay10 brings together instant payments, Open Finance, digital accounts, domestic card infrastructure and merchant payment acceptance through an integrated platform.
Directly integrated with Aani, Pay10 enables instant payments and supports account-based payment experiences. Its Open Finance capabilities allow consumers to securely connect supported bank accounts, access consolidated financial information and monitor spending through one application. Its Jaywan issuance capabilities also enable eligible wallet customers to access domestic card payments across POS terminals, ATMs and e-commerce channels.
For merchants, the platform offers multiple payment acceptance options, including Pay by Pay10, Pay by Bank, card acceptance, interoperable QR payments, payment links and digital payouts. Its proprietary POS application, QR and soundbox solutions are supported by an in-house Terminal Management System.
Through supported account-based payment methods, merchants can access funds in real time, helping improve cash flow and reduce payment acceptance costs, with potential savings of up to 70% in applicable use cases. Pay10 also reports transaction success rates of over 90% across its integrated technology infrastructure.
Strategic Partnerships and Collaborations
The partnerships with GEMS and Jumbo Electronics aim to expand digital payment choices and improve collection efficiency across education and consumer retail. Existing deployments with GEMS, Bikanervala, Allday and Just Gold demonstrate the application of Pay10’s payment solutions across different commercial environments.
Allday, a leading convenience chain in the region, presents an opportunity to explore the impact of digital payment solutions across high-frequency, small-value transactions.
Pay10 also announced several MoUs to explore emerging financial use cases. Its partnership with Yalla Financial Solutions, part of Fintra Holding, will explore bank-account-based wallet funding through Open Finance.
Additionally, our collaboration with TotalPay will enable TotalPay to access Pay10’s merchant payment acceptance capabilities through its technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
Dr. Waleed Sadek, Founder & CEO of Yalla Financial Solutions, said: “We are pleased to explore this strategic collaboration with Pay10, reflecting our shared vision of building a more connected and accessible financial ecosystem. Through Open Finance and account-based wallet funding, we aim to unlock new opportunities for seamless digital payments and enhance the financial experience for businesses and consumers across the region.”
Supporting the UAE’s Financial Infrastructure
Pay10’s strategy aligns with the Central Bank of the UAE’s FIT Programme through the adoption of domestic payment infrastructure, including Aani, Jaywan and Open Finance. By investing in direct infrastructure connectivity and proprietary technology, the company aims to support greater interoperability, financial inclusion and more efficient payment experiences.
Harry Gill, Founder & Chairman, Pay10, said: “The UAE has laid the foundations for the future of finance, and our goal is to make it accessible to everyone. Pay10 is building a UAE-based alternative payment ecosystem that brings together domestic payment infrastructure, Open Finance, accounts, cards and merchant solutions. Our partnerships with GEMS, Jumbo Electronics, Bikanervala, Allday and Just Gold reflect growing confidence in this vision. We remain committed to advancing the UAE’s financial ambitions through a connected, interoperable ecosystem built to scale globally.”
Our collaboration with TotalPay will enable it to access Pay10’s payment acceptance capabilities for merchants through TotalPay’s technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
With further agreements, product launches and integrations in development, Pay10 aims to expand its consumer and merchant capabilities across the UAE and international markets.

H&H’s AED 30 Billion Dubai Peninsula Development Takes Shape, Home to Five World-Renowned Hospitality Brands

The Best Festive Turkey Takeaways in Abu Dhabi This Christmas

Qatar Airways Connects Doha to Caracas, Venezuela, and Bogotá, Colombia with First Flight


-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai