 Have a question? +971 56 404 0503

Financial
Fed’s Bold 50-Point Rate Cut Addresses Growing Economic Risks


A bold response to mounting economic risks
The Federal Reserve’s decision to implement a larger-than-expected 50 basis point rate cut is a powerful demonstration of the central bank’s resolve to proactively address the mounting risks to the U.S. economic outlook. This aggressive move, which caught many market participants by surprise, reflects the Fed’s growing concerns about the impact of slowing global growth, trade tensions, and persistently low inflation on the domestic economy.
The 50bp reduction in interest rates, the first cut of this magnitude since the global financial crisis, underscores the Fed’s willingness to use all the tools at its disposal to support the ongoing expansion and prevent a more pronounced slowdown. By providing a substantial dose of monetary stimulus, the Fed is signaling its determination to get ahead of the curve and cushion the economy against potential shocks.
The Fed’s bold action comes against the backdrop of an economy that, while still expanding, has shown signs of cooling in recent months. The moderation in retail sales growth, coupled with the stagnation in industrial production, highlights the challenges faced by businesses and consumers alike as they navigate an increasingly uncertain economic environment.
However, the larger-than-expected rate cut also carries potential risks and unintended consequences. Some market participants may interpret the aggressive easing as a sign of panic, potentially fueling volatility and uncertainty in financial markets. Moreover, the 50bp reduction may limit the Fed’s ability to respond to future challenges if economic conditions continue to deteriorate.
As investors and analysts parse the Fed’s accompanying statement and economic projections, the central bank’s forward guidance will be crucial in shaping expectations about the future path of monetary policy. The possibility of additional rate cuts cannot be discounted, particularly if the global economic outlook continues to darken or if domestic growth shows further signs of weakening.
While the 50bp rate cut is a significant step in the Fed’s efforts to sustain the economic expansion, it is important to recognize that monetary policy alone cannot address all the structural challenges faced by the U.S. economy. Policymakers must also focus on implementing fiscal measures and structural reforms that promote long-term growth, productivity, and competitiveness.
The Fed’s bold move, while not without its risks, demonstrates the central bank’s unwavering commitment to its dual mandate of promoting maximum employment and price stability. As the U.S. economy navigates an increasingly complex and uncertain global environment, the Fed’s decisive leadership and proactive approach will be essential in guiding the nation towards a path of continued growth and prosperity.
Key points of this outcome to note
- The. Fed have cuts interest rates by 50 bps for first time since 2020, in the pandemic.
- Bringing its target range to 4.75% to 5%
- Powell said the Fed has gained greater confidence that inflation is moving sustainably towards moving to 2%
- Fed sees 100 bps of rate cuts in 2025 and 50 bps of cuts in 2026
- Outside of the emergency rate cuts during Covid, the last time the FOMC cut rates by half a point was in 2008.
- Fed sees 2 more 25 bps rate cuts in 2024.
- The decision to lower interest rates marks a turning point for the Fed, which as seen this year to keep rates high to subdue inflation, with todays outcome presenting confidence of inflation deducting.






Financial
Fimple adds five GCC financial institutions in first year, targets doubling regional customer base
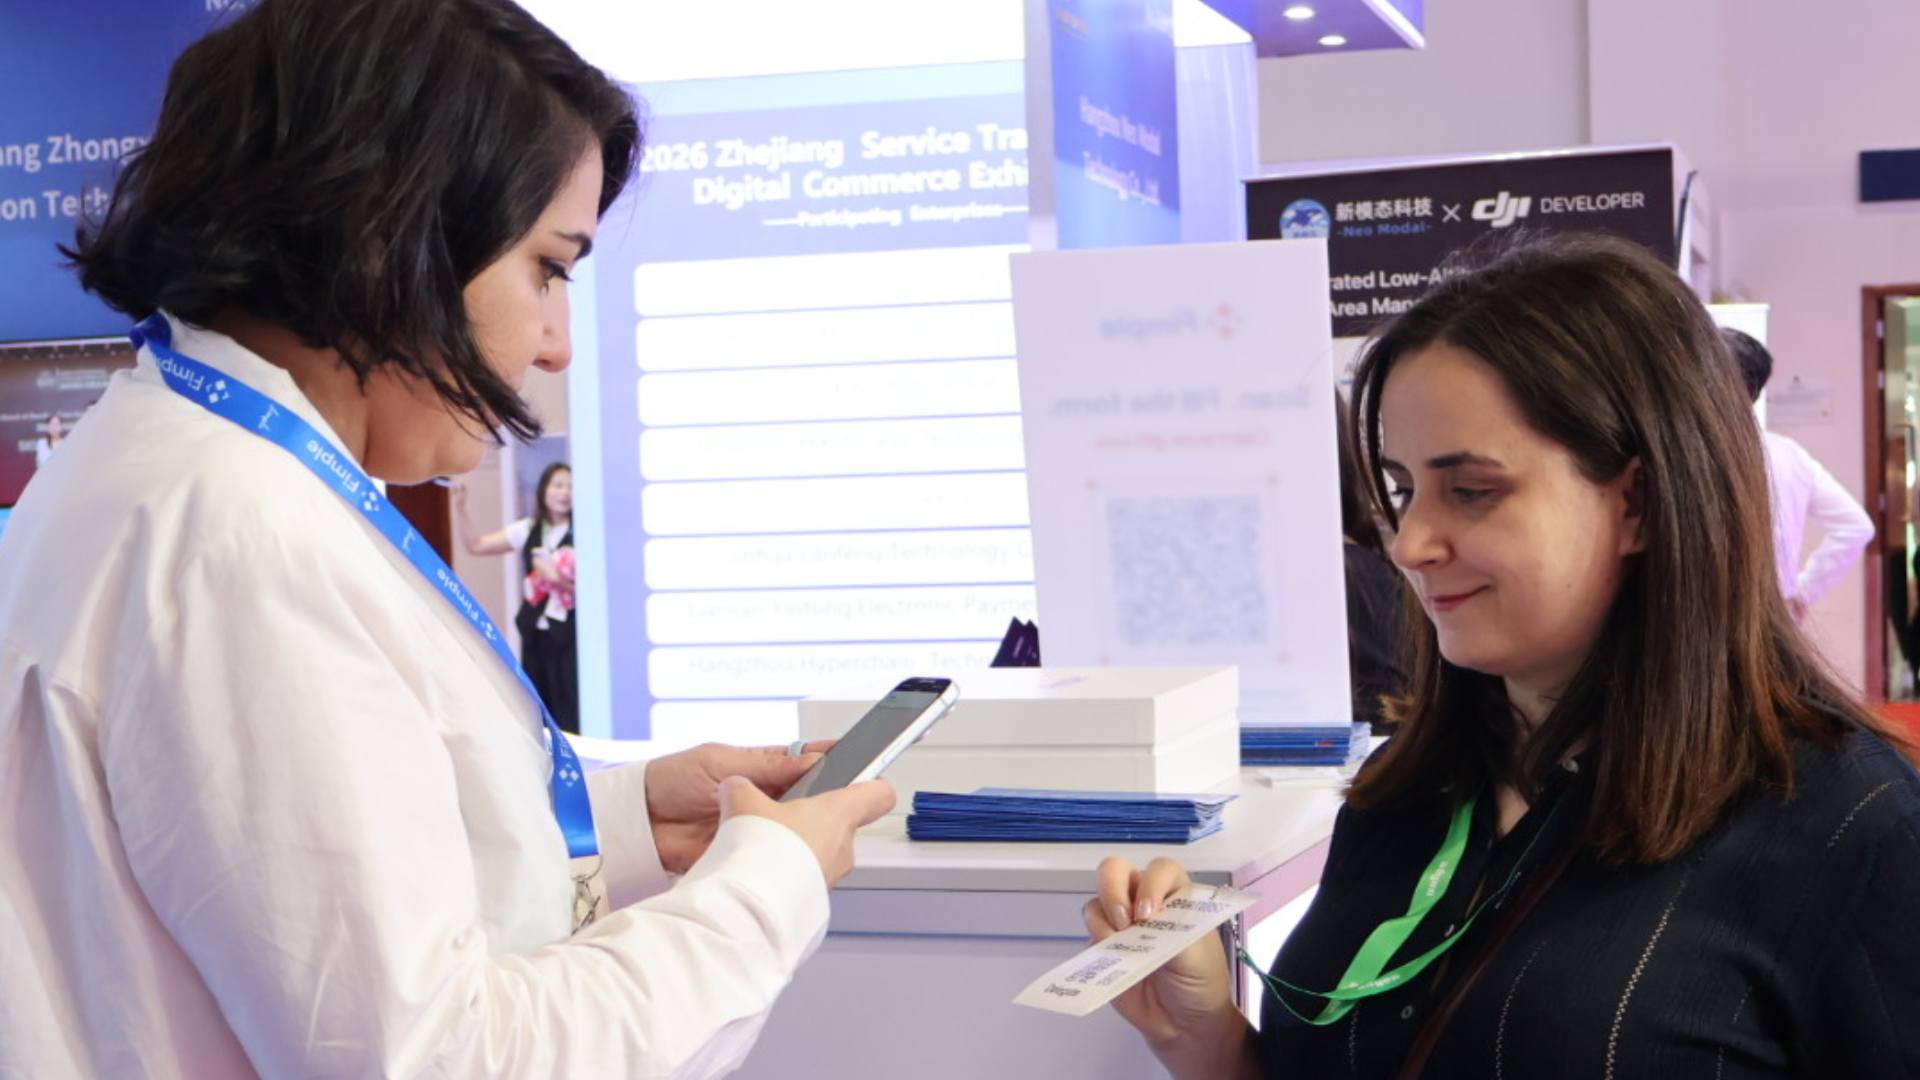
Fimple, an AI-native, API-first, composable financial platform, has signed five financial institutions across the GCC within its first year in the region and plans to double its regional customer base.
Fimple established its Dubai presence in October 2025 and has grown from zero to five GCC customers in 12 months. The region now accounts for close to a fifth of its global customer base of more than 35 financial institutions across 10 countries, making it the company’s fastest-growing region.
The company has also opened an office in Riyadh and plans to expand its customer and delivery presence across the GCC, serving institutions with teams based within the region.
Fimple’s regional growth comes as the UAE continues to advance its ambitions across Islamic finance and financial technology. Under the UAE Strategy for Islamic Finance and Halal Industry, the country aims to increase local Islamic bank assets from AED 986 billion to AED 2.56 trillion by 2031. (Source: UAECabinet.ae)
Dubai is also advancing its ambitions in AI-enabled financial services, with the Dubai International Financial Centre (DIFC) announcing plans in 2026 to become the world’s first AI-native financial centre. (Source: Dubai Media Office/DIFC)
“The UAE is an important market for Fimple because financial institutions here are moving quickly on both Islamic finance and new technology,” said Amr Kandel, GCC Country Manager and Product Director at Fimple. “Banks want to launch products faster, respond to local market needs and modernise without having to change everything at once. The growth we’ve seen in our first year shows there is real appetite for that.”
Islamic finance is a key driver of Fimple’s growth in the GCC. The platform enables financial institutions to run conventional and Islamic finance within the same system, with a range of Sharia-compliant financing and investment structures built into its product engine.
Fimple’s regional customers include Mawarid Finance, a UAE Islamic finance provider that entered into a strategic agreement with Fimple in June 2026.
As banks look to move AI from pilot projects into wider use, Fimple says the underlying core banking infrastructure is becoming increasingly important.
“Banks are already experimenting with AI, but the systems underneath need to be ready for it,” Kandel said. “If the core can’t provide the right data or connect easily with new technology, AI can get stuck at the pilot stage. That’s why the core matters.”
Fimple has built three banking AI agents covering independent audit report processing, customer intelligence from official notices and risk screening across official sources. The agents operate on the Fimple platform with human approval required for each action and full traceability. Further agents are planned as part of the company’s 2026–2027 roadmap.
According to Fimple, it implements a full working core in three to six months on average. Its composable architecture also enables financial institutions to connect selected modules to existing systems rather than replacing their entire core infrastructure at once.
“The GCC has become our fastest-growing region in just one year, and we expect to double our customer base here,” said Mücahit Gündebahar, CEO and Co-founder of Fimple. “We are growing our team and presence in the region so we can support customers locally as we expand across the GCC.”
Fimple will participate as a Gold Sponsor of Seamless Middle East 2026, taking place from Sept. 22–24 at Dubai World Trade Centre. The company will exhibit at stand G64, with Kandel delivering the session “Beyond the AI Hype: Why the Future of Banking Depends on an AI-Ready Core” on Sept. 23 at Stage 1, Fintech Forum.
Financial
Al Masraf and Moody’s Sign Strategic Agreement to Strengthen Risk Intelligence and Credit Capabilities
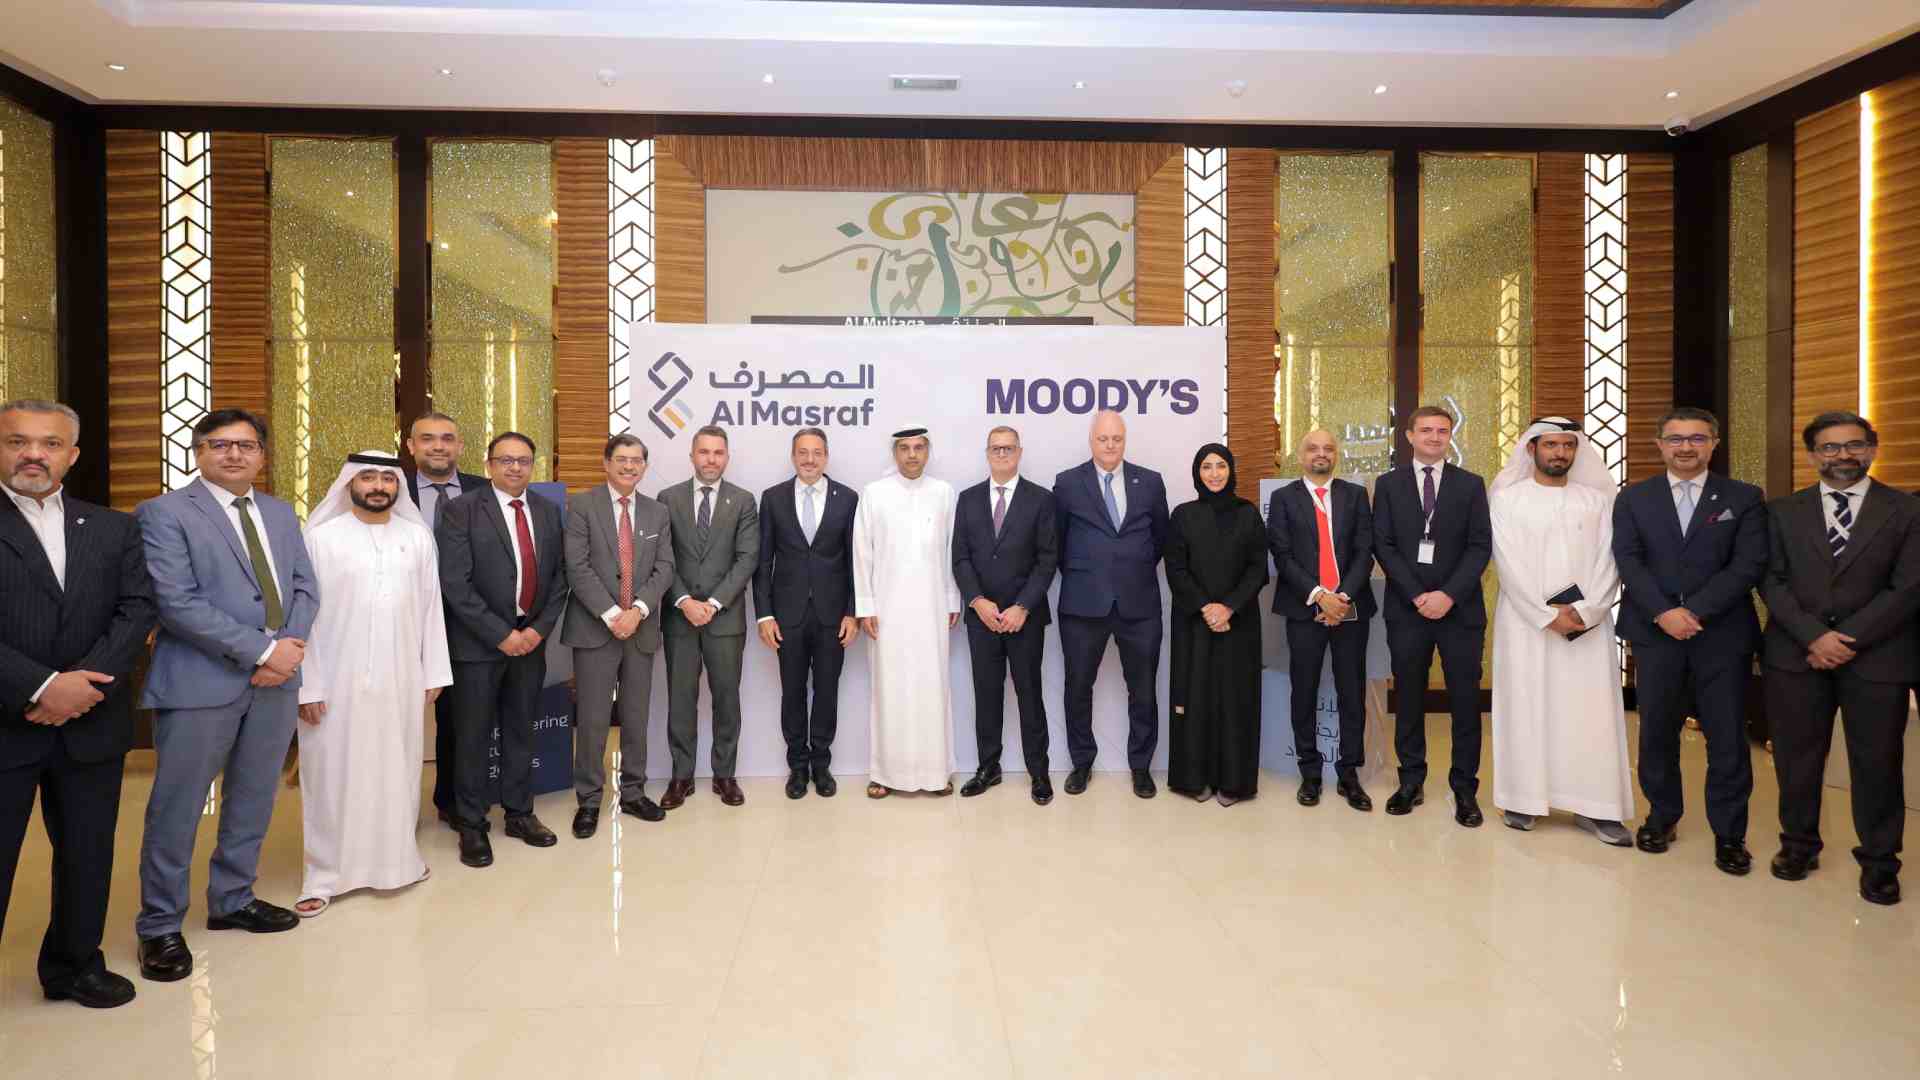
Al Masraf has signed a strategic agreement with Moody’s, a global provider of financial intelligence and risk assessment, marking an important step in strengthening the Bank’s risk management and credit capabilities through enhanced data, insights and technology.
The agreement was formalized during a signing ceremony held in Abu Dhabi, bringing together senior leadership from Al Masraf and Moody’s. The collaboration reflects both organizations’ commitment to leveraging advanced intelligence and risk expertise to support informed, data-driven decision-making in an increasingly complex financial environment.
As risks become increasingly interconnected and the financial landscape continues to evolve, access to timely, reliable and actionable intelligence is becoming essential for financial institutions. Through its combination of data, intelligence, risk expertise and technology, Moody’s helps organizations better understand interconnected risks.
The partnership will further support Al Masraf’s continued focus on strengthening its risk management framework, enhancing credit decision-making and building resilient, forward-looking capabilities that support sustainable growth.
Commenting on the occasion, Fuad Mohamed, CEO of Al Masraf, said: “At Al Masraf, we believe that sustainable growth is built on the strength of our ability to understand risk, anticipate change and make informed decisions. Our collaboration with Moody’s represents an important step in advancing our risk and credit capabilities through deeper intelligence, data and technology.”
He continued: “As the financial landscape continues to evolve, partnerships of this nature enable us to strengthen our resilience, enhance decision-making and create greater value for our customers and stakeholders. We look forward to building on this collaboration as we continue to shape a more agile, intelligent and future-ready Al Masraf.”
“We are delighted to partner with Al Masraf on an important step in modernizing its corporate lending operations. By bringing greater automation, efficiency, and insight to the credit journey, Moody’s is helping the bank build a future-ready operating model that enables faster, better-informed lending decisions, strengthens governance, and enhances risk management.” said Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East at Moody’s.
Senior representatives from both organizations attended the signing ceremony.
Representing Al Masraf were Fuad Mohamed, Chief Executive Officer; Moataz Khalil, Chief Wholesale Banking Officer; Safeya Almarzooqi, Chief Credit Officer; Mirel Baila, Acting Chief Operating Officer; Rohit Kumar, Chief Risk Officer; and senior representatives from the Bank’s Wholesale Banking, Credit, Risk, Information Technology, Islamic Banking, Corporate Banking, Project Management and Business Management functions.
Representing Moody’s were Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East; Brendan Gavaghan, Senior Director, Middle East; Raghavendra Katagade, Director, UAE; Blaine Connan, Director, UAE; Ali Abdullah, Director, UAE; and Anand Thirunellai Radhakrishnan, Senior Director, Middle East & Europe.
The agreement underscores Al Masraf’s commitment to continuous innovation and adopting advanced capabilities that strengthen its ability to navigate an evolving risk environment, while supporting the Bank’s broader ambition to deliver sustainable growth and enhanced value to its customers and stakeholders.
With the dirham pegged to the US dollar and UAE investors exposed to global markets, decisions made by the Federal Reserve and the US government can influence local borrowing costs, liquidity, and investment
sentiment. Michael Smirnow, Chief Investment Officer, Arabian Capital Gulf
After the global financial crisis, U.S. authorities tried to stimulate the economy primarily through monetary measures: the Federal Reserve cut interest rates to zero and launched quantitative easing (QE) for the first time, purchasing assets to provide market participants with liquidity. As a result, the Fed’s balance sheet grew to USD 8 trillion by 2021. However, between 2008 and 2020, the U.S. economy did
not experience rapid growth, and inflation regularly remained below the target level. Everything changed in 2020, when the government entered the stimulus fray for the first time in many years. While the Fed’s accommodative monetary policy primarily helped large banks and market participants, at the onset of
the pandemic the U.S. government began distributing money to households and increasing budget expenditure across nearly all areas. Compared with monetary measures, these fiscal stimulus measures proved to be a significantly more powerful tool for stimulating the economy; however, they increased
government debt by the aforementioned 61%. Against this backdrop, we expect the next few years to be shaped primarily by fiscal stimulus, with
government action, rather than the Federal Reserve, becoming the key factor for investors. Indeed, while the private sector ran large deficits before 2008, the deficit now lies with the government, while private-sector indebtedness is declining. In the years following the pandemic, the largest government deficits coincided with the strongest growth in financial markets. This is unsurprising, since a public-sector deficit becomes private-sector income. This dynamic enabled the U.S. economy to remain resilient in 2023-2024 despite the Fed’s record pace of interest-rate increases. Whichever U.S. political party is in power will continue along this path;
Trump is also doing the same through legislation known as the “Big Beautiful Bill.” As long as inflation in the United States remains under control, this race will continue.
The current balance between monetary and fiscal stimulus vividly illustrates this argument. On the one hand, the U.S. Federal Reserve is adopting an increasingly neutral stance and is clearly in no hurry to cut interest rates or introduce new stimulus programmes. On the other hand, the Treasury is entering the fray: as yields on long-term U.S. bonds confidently exceed 5%, the Treasury has launched a program to buy back its long-term debt. In effect, this gives the bond market the same kind of stimulus the Fed previously delivered.
Thus, the balance of power is changing, but the direction remains the same: the United States still needs accommodative monetary conditions. If these are not achieved through monetary measures, they will be achieved through fiscal ones.
(Arabian Gulf Capital (AGC) holds a Category-1 Investment Firm license issued by the Central Bank of Bahrain and provides tailored investment solutions to individual, corporate, and institutional clients.)

Europe’s Data Centres Are Evolving From Power Consumers to Energy Partner

Fimple adds five GCC financial institutions in first year, targets doubling regional customer base

New Initiative ‘Longevity Starts From Childhood’ Connects the Early Years With Lifelong Wellbeing


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
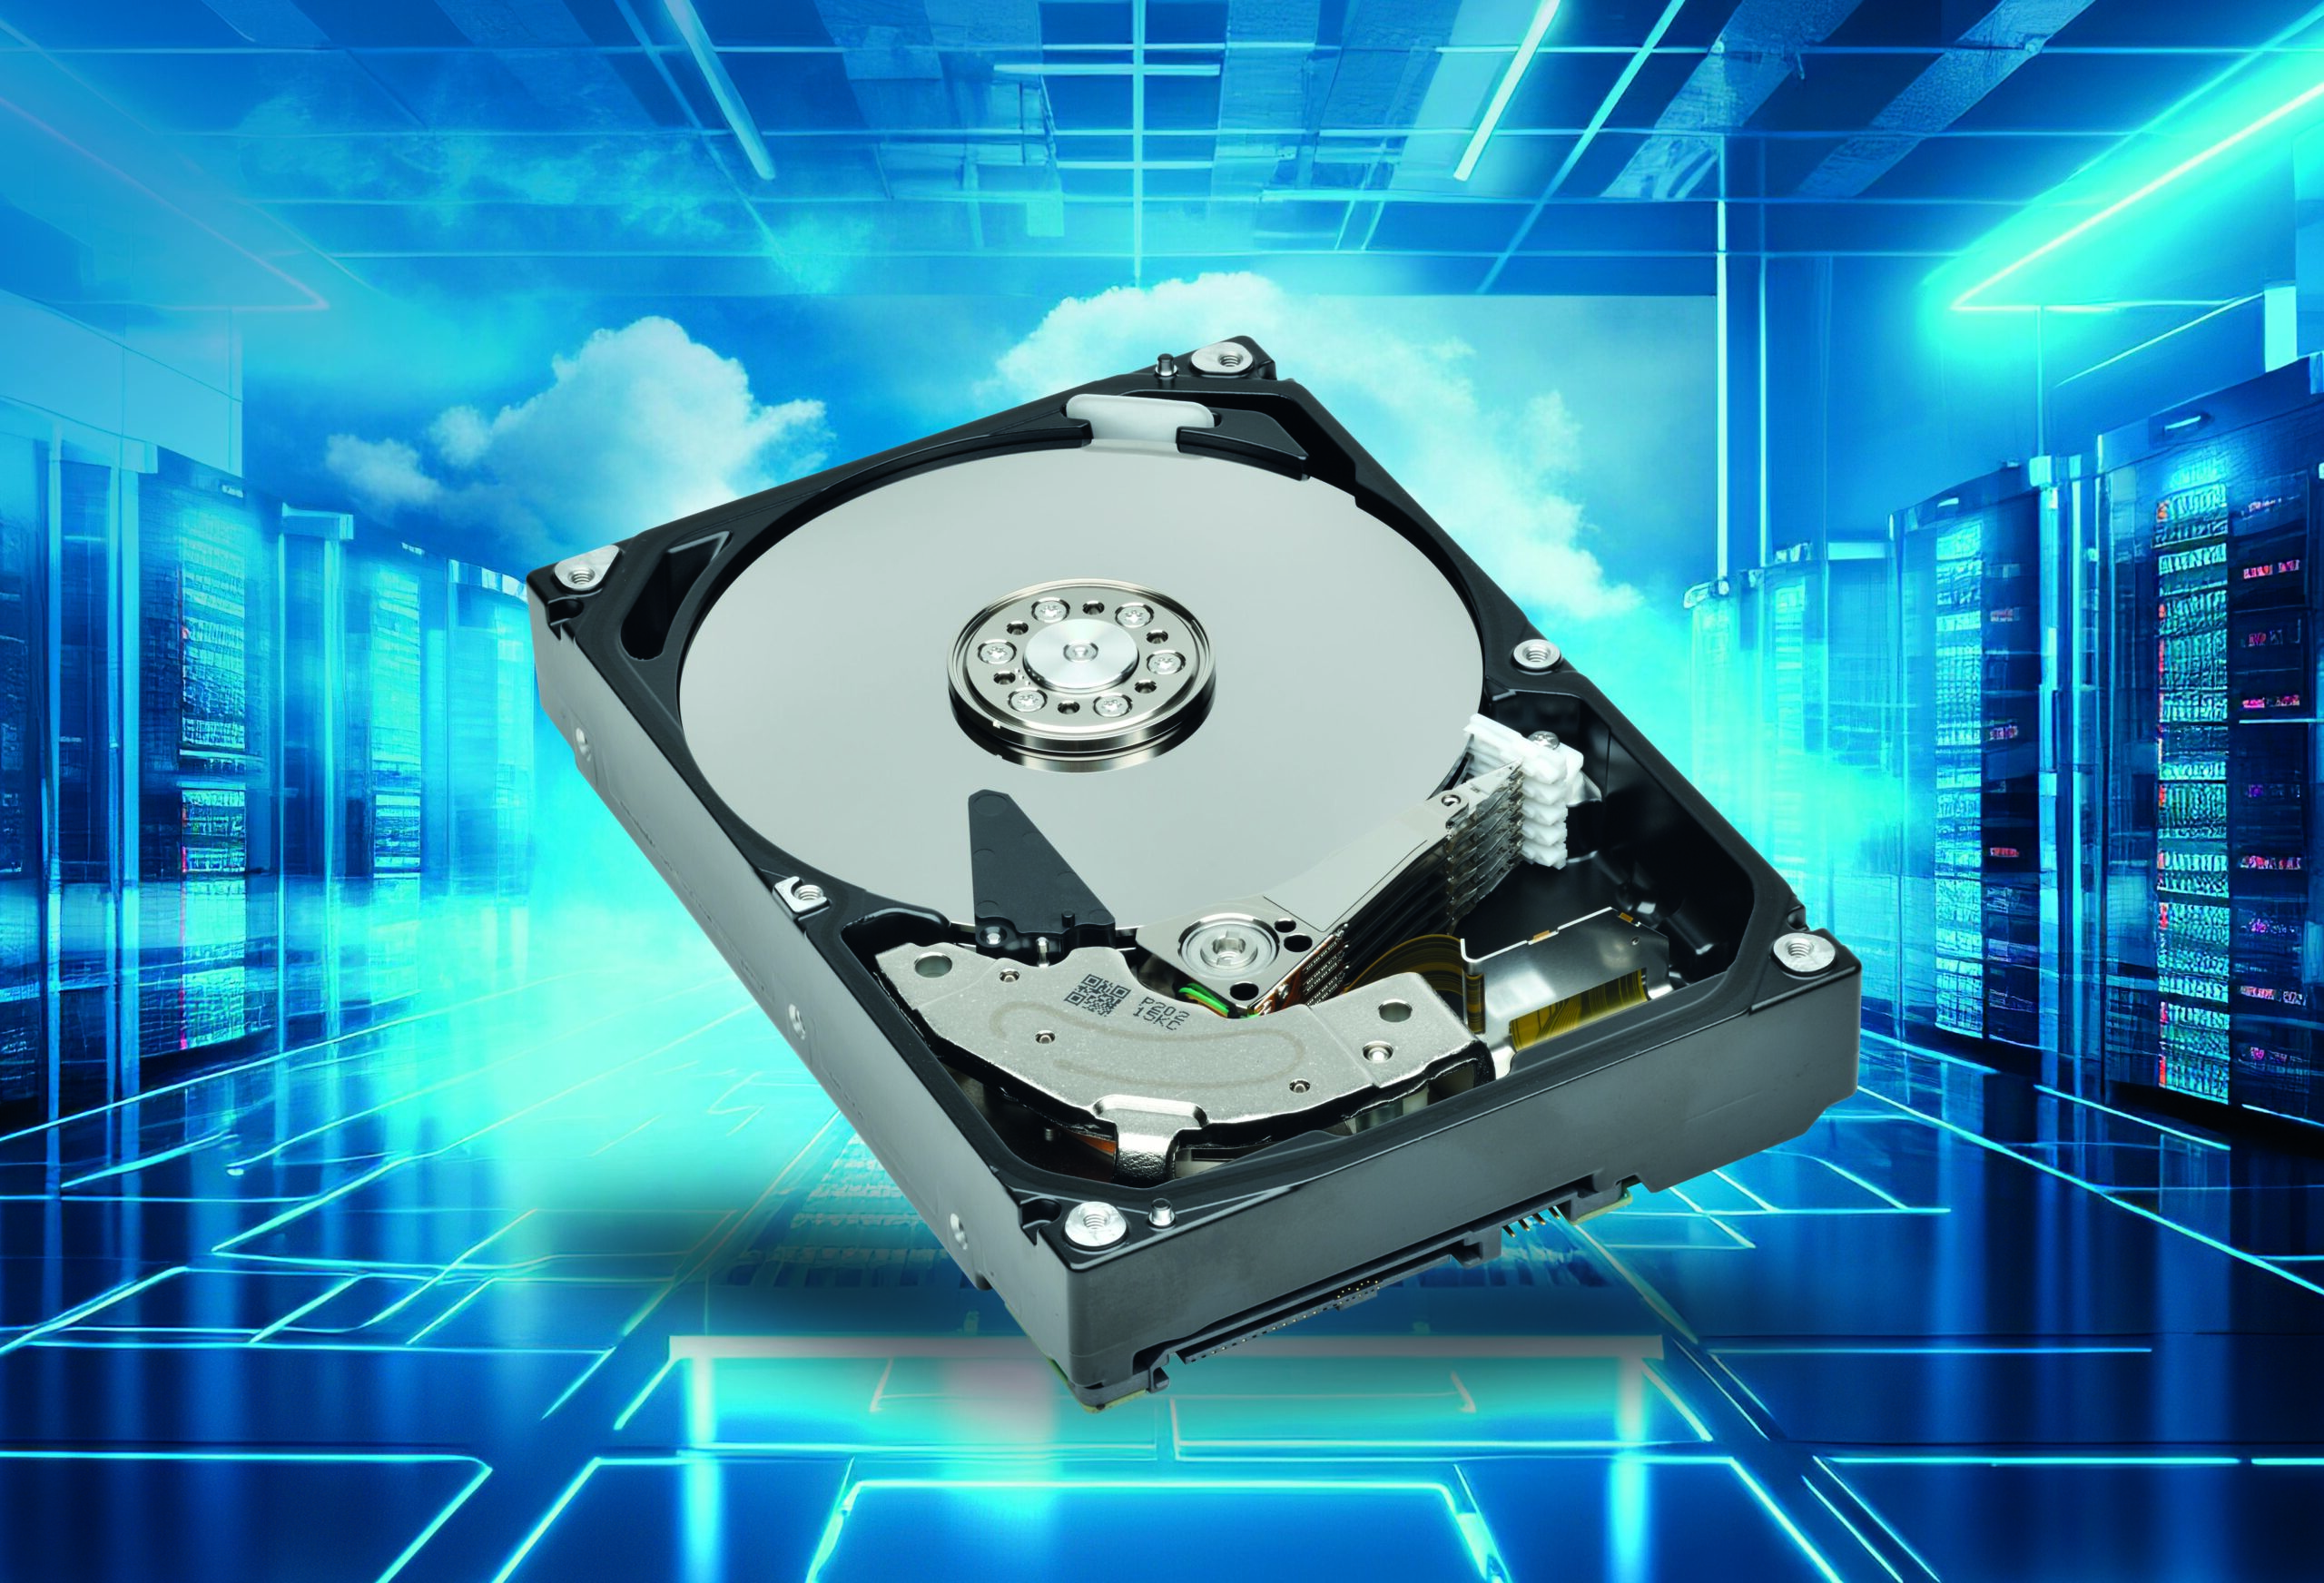
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai