 Have a question? +971 56 404 0503

Financial
5 SMART WAYS UAE TRAVELERS CAN PROTECT THEIR FINANCES THIS FESTIVE SEASON

By Hennie du Plessis, Senior Vice President, Payment Services, Middle East and Africa at IDEMIA Secure Transactions (IST)
The festive season is one of the busiest periods of the year for UAE travelers. From year end getaways and family visits, to overseas shopping and digital gifting, consumers increasingly rely on contactless cards and mobile wallets to make payments quickly and conveniently.
Beyond higher spending, the festive season also acts as a real stress test for digital payment ecosystems. Transaction volumes peak, payment environments become less familiar, and consumers move rapidly across borders. This combination of factors increases exposure to fraud if the right safeguards are not in place. As digital payments scale, security becomes a critical enabler of trust.
According to IDEMIA Secure Transactions’ latest Global Consumer Payment Survey, which included UAE respondents aged 18 to 71, more than 8 in ten consumers have already adopted digital cards with biometric features, while 92 percent express interest in numberless cards. These figures reflect a growing expectation for payment experiences that combine speed, simplicity, and security.
With contactless payments now accounting for 84 percent of face-to-face transactions in the UAE and mobile wallet usage surpassing 50 percent, the festive season is a critical moment for travelers to reassess how they protect their finances while on the move.
1. Avoid Public Wi-Fi for Payment Activity
Festive travel often means relying on airport or hotel Wi-Fi, but unsecured networks remain a common entry point for cybercriminals. Accessing banking apps or making purchases over public Wi-Fi can expose sensitive information at interception. Travelers should use mobile data or a trusted VPN when handling financial transactions. A few moments of convenience are never worth the risk of compromised financial data, especially during peak travel periods.
2. Use Secure Digital Payment Solutions
Not all payment tools offer the same level of protection. Today, tokenization has become a global industry standard for securing digital transactions, replacing sensitive card details with unique digital tokens that are useless if intercepted. Mobile wallets such as Apple Pay, Google Pay, and Samsung Pay already rely on this technology.
Beyond protecting data in transit, tokenization also limits exposure in the event of merchant-side data breaches, as real card numbers are never stored or shared. Tokens are typically device-specific and transaction-bound, adding an additional layer of protection even if credentials are compromised elsewhere.
IDEMIA Secure Transactions plays a key role in enabling tokenized payments at scale, supporting secure transactions across in-store, online and in-app environments through its EMVCo-certified Token Platform. Digital co-badged cards offer global compatibility without sacrificing local functionality. By ensuring that real card numbers are never shared, tokenization significantly reduces fraud risk while preserving a smooth user experience. In addition, digital wallets can be remotely suspended if a device is lost or stolen, offering travelers greater control and peace of mind while abroad.
3. Decline Dynamic Currency Conversion
While shopping abroad during the festive season, merchants often offer travelers the option to pay in AED. This practice, known as dynamic currency conversion, typically includes hidden markups and unfavorable exchange rates. Paying in the local currency allows banks to apply more transparent conversion rates, helping consumers avoid unnecessary costs. This simple choice can make a meaningful difference for frequent travelers and international shoppers alike.
Another possibility for travelers is to use the Tap to Phone technology provided by some banks and supported by IST. Instead of having to switch cards across borders, it enables the travelers to modify their card features, such as credit/debit options and the currency used for transactions, with a simple tap on a smartphone via their banking app. This simple habit can save money and ensure better financial clarity while greatly facilitating international card usage.
4. Enable Real Time Alerts and Card Controls
With spending increasing during the festive period, real time monitoring is essential. Many UAE banks and fintech platforms offer instant transaction alerts, spending limits and location-based restrictions that allow consumers to monitor activity as it happens.
Crucially, modern security no longer has to come at the expense of convenience. These tools enhance protection while maintaining the fast, frictionless payment experiences that consumers expect, particularly in a market where one-click and contactless payments are widely adopted. This aligns with consumer expectations, as 96 percent of UAE users prefer simplified one click payment experiences. Real time controls enhance security without adding friction.
5. Secure Devices Before You Travel
Smartphones now function as wallets, boarding passes and identity tools. Before travelling, users should update device software, enable biometric authentication and avoid storing sensitive information in unsecured apps. Travelers should also activate remote lock and wipe functionality, ensure cloud backups are enabled, and avoid carrying all payment methods on a single device. Keeping at least one physical card separate from the phone provides an important fallback. While digital wallets rely on encrypted token technology, 29 percent of surveyed users still express concerns about digital card security, and 43 percent do not fully understand how these tools work. Basic preparation can significantly reduce risk and soothe concerns.
As UAE card payments are expected to reach USD 150 billion this year, the festive season highlights the need for secure and user-friendly payment infrastructure. By adopting the right tools and habits, travelers can focus on celebrating rather than dealing with fraud.
For the payments industry, the challenge is clear: security must be built into every transaction in a way that protects users without disrupting their experience. When trust is embedded seamlessly, travelers are free to enjoy the moments that matter most, wherever their journey takes them.
MidChains FZE, a digital asset platform licensed by the Virtual Assets Regulatory Authority (VARA) to provide broker-dealer services to retail, institutional and qualified investors, today announced a strategic banking partnership with Standard Chartered.
Under the partnership, Standard Chartered will support MidChains with a range of banking services, including fiat settlement capabilities, segregated client money accounts, and correspondent banking. These services will power MidChains’ day-to-day operations and enable efficient settlement.
Rola Abu Manneh, Chief Executive Officer, UAE, Middle East and Pakistan, Standard Chartered, said: “The UAE has established itself as one of the world’s leading regulatory environments for digital assets and a global centre for financial activity. That creates a strong setting for regulated digital asset firms and established financial institutions to work together. Our partnership with MidChains puts that opportunity into practice, with Standard Chartered providing the banking services that support its institutional activity, including fiat settlement, segregated client money accounts and correspondent banking.”
Basil Al Askari, Chief Executive Officer, MidChains, added: “Institutional capital moves continuously between traditional and digital markets, and the infrastructure supporting that activity must keep pace. For institutional investors, digital asset services need to connect with the banking system that supports their wider activity. Our partnership with Standard Chartered brings that connection to MidChains’ institutional services, supporting clients as capital moves between traditional and digital markets.”
By bringing a VARA-licensed digital asset platform together with an established international bank, the partnership connects institutional digital asset activity with the banking infrastructure behind fiat settlement. It is a practical example of how the UAE’s regulated financial ecosystem can link innovation with established banking capabilities to support international business.
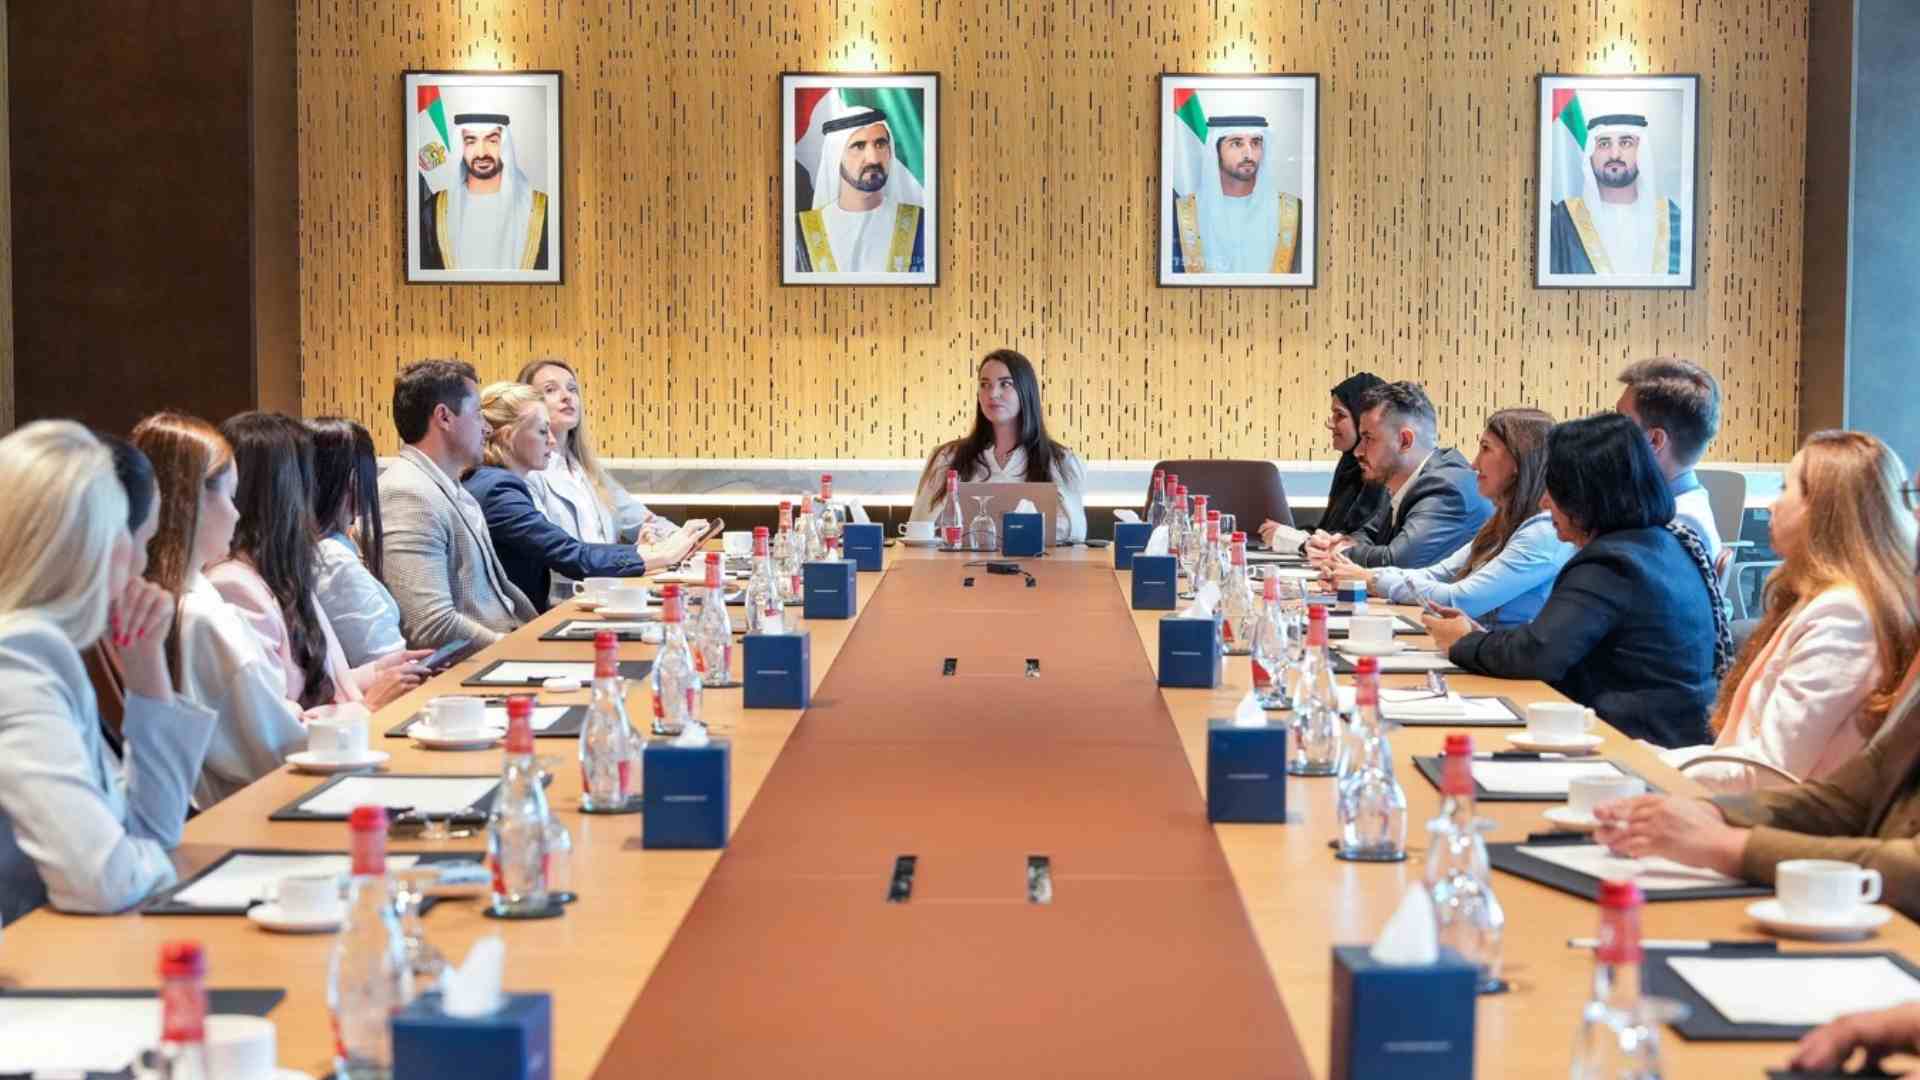
The Ukrainian Business Council in the UAE (UBC) elected a new Board at its General Assembly at Dubai Chamber, where members also approved a 2026–2028 strategy to strengthen trade and investment between the two countries.
Over the next three years, the Council plans to extend its trade delegation programme to new markets, deepen ties with international business councils and launch structured investment dialogues to connect UAE investors with opportunities in Ukraine. The UAE–Ukraine Comprehensive Economic Partnership Agreement (CEPA), Ukraine’s first agreement of its kind with a Gulf state, came into force in July 2026 and removes or reduces customs duties on most goods traded between the two countries.
“Ukrainian companies are achieving real results in the UAE, and we see significant untapped potential for Emirati business and investment in Ukraine. Our role is to build on this momentum: to connect the right partners, support companies at every stage of their growth and help investment flow with confidence in both directions.” commented Olena Shyrokova, President, Ukrainian Business Council in the UAE.
In 2025 and 2026, UBC led business delegations to Vienna, Qatar, Ras Al Khaimah, Fujairah, Oman and the Seychelles. It also ran webinars on UAE market entry for Ukrainian companies and business associations and supported the Ukrainian IT delegation at GITEX. Since its founding in 2016, the Council has established a dialogue with the Federation of UAE Chambers and chambers of commerce across the Emirates.
Under the new strategy, UBC will work with international business councils to give Ukrainian companies access to wider business networks in the Emirates and use the UAE as a base for trade missions to the Gulf, Asia and Africa. The Council will help Ukrainian companies in the UAE with registration, investment and expansion. It also plans to help Ukrainian investors find opportunities in the Emirates, attract Emirati investment to support Ukraine’s recovery and develop arbitration and investor protection mechanisms to build confidence in cross-border agreements.
The Council sees the strongest potential in sectors where Ukrainian strengths meet Emirati priorities: agri-food and food security, IT and digital services, renewable energy, logistics and port infrastructure, and post-war reconstruction. These are also the areas both governments have highlighted for future cooperation.
UBC works closely with the Embassy of Ukraine in the UAE and with H.E. Dr Oleksandr Balanutsa, Ambassador Extraordinary and Plenipotentiary of Ukraine to the UAE. The Council took part in the Cities Unite: Cultural and Business Exchange between the UAE and Ukraine dialogue at Expo City Dubai, initiated by H.E. Reem bint Ebrahim Al Hashimy, UAE Minister of State for International Cooperation, and the Embassy of Ukraine.
The Council will continue to support Ukrainian businesses and the wider community, helping companies expand into the UAE and encouraging UAE investment in Ukraine. Businesses, investors and potential partners interested in working with the Council can get in touch by reaching out to info@ukrainianbc.org.
The UAE has built one of the world’s most successful models for attracting foreign direct investment (FDI) and is now positioned to convert that capital into lasting innovation and skill development, according to a white paper from White Paper Media Consulting (WPM), a UAE-based strategic research house that is shaping business and policy conversations in the region using credible datasets and analytical tools.
Beyond the Numbers: The Transformative Intangible Impact of FDI argues that the real returns on FDI now lie in the intangible value it embeds within host economies, with the UAE a defining case study. The paper contends that the next phase will go beyond investment volumes, number of projects, and job creation and be measured also in patents generated, skills transferred, data ecosystems built, and clean technologies commercialized, among other things.
Official data shows that the UAE attracted more than $48.3 billion in FDI inflows in 2025, capturing 3.1% of global flows. Greenfield FDI reflected both volume and capital depth, with 1,562 projects announced for a combined $34.1 billion in capex, or 1.8% of the global total.
The country’s ability to attract investment reflects its competitiveness as a hub for operational efficiency, supply chain integration, and regional headquarters functions. The UAE has deliberately repositioned its FDI strategy toward knowledge-intensive and future-oriented sectors, recognizing that long-term competitiveness is increasingly driven by innovation, digital capabilities, and human capital. This approach aligns closely with the OECD FDI Qualities framework, with tangible examples across each dimension: including the innovation and competitiveness, digitalization and technology adoption, sustainability and clean energy investments for climate targets, and human capital and local expertise.
Drawing on the OECD framework and benchmarks from Ireland, Singapore, Israel, Costa Rica, and Malaysia, the report documents how leading economies have shifted focus from the volume of capital they attract to the long-term value it creates. In the context of UAE, this is visible in the shift in the country’s policies across phases that begin with the Foundation Phase from 1985 to 2005 of Market Liberalization and Infrastructure Creation, culminating in the current positioning as Global Capital and Technology Hub.
The shift to value in the UAE has made a huge difference to the job-creation intensity of FDI. Approximately 2,816 jobs were created in the UAE for every billion dollars received in greenfield FDI in the five years from 2019 to 2023, compared to 2,265 in the previous five years. This is higher than the OECD average of 2,318 and 1,880 respectively.
The paper identifies seven ongoing policy shifts that deepen the qualitative impact of FDI in the UAE, including extending spillovers from free zones into the mainland economy, prioritizing R&D-intensive investment, embedding skills transfer requirements in major projects, and positioning the country as a global leader in IP creation and data governance.
Yazad Darasha, co-founder and director, WPM, said: “As trusted partners of public and private sector clients, we have tracked the UAE’s investment story for years, and the pattern is unmistakable. The country has positioned itself at the front of the race for capital. What we set out to map in this paper is the harder, more valuable contest: converting investment into skills, technology, and economic velocity. It reflects what we do at White Paper Media, turning complex evidence into decisions leaders can act on.”
Dr. Joachim Arnold, CEO of OCO Global, which advises governments and businesses on attracting FDI, building competitiveness, and strengthening economic resilience, and contributed to the study, said: “The UAE’s infrastructure, free zones, and business-friendly environment helped attract companies and drive growth. The National Investment Strategy 2031 signals a more deliberate focus on investment that raises productivity and embeds benefits into the wider economy. The question is no longer only how to attract capital, but how investment creates lasting value, strengthens existing companies, and helps domestic businesses upgrade their capabilities.”
The paper highlights live examples of this transition already underway, among them the Space42 and ICEYE joint venture building satellites on UAE soil, Microsoft’s $15.2 billion investment plan with a commitment to skill one million people, and the UAE’s $30 billion pledge to the Alterra climate fund.

DOERS Summit Dubai 2026 to Bring Together 5,000 Participants for Technology and Investment Discussions

Beyond the 30×30: EVIRON Encourages Everyday Wellness This Dubai Fitness Challenge
UBK Turns Up the Festive Season with Weekly Quiz Nights, a Saturday Mic Drop and Festive Turkey to Go

OPPO A6 Pro 5G Review: Reliable Daily Driver

Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer

Microsoft Launches New Surface Copilot+ PCs for Business

2026 in Review: Is AI Becoming More of a Management Problem Than a Technology Problem?

Inside XPENG Brand Night: AI Mobility Lands Centre Stage in Dubai

Chinese Cars Are Reshaping the GCC Market, but Resale Value Could Be the Next Battleground
-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-
 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
News4 years ago
BenQ ZOWIE : First TN 360Hz DyAc+ Gaming Monitor