 Have a question? +971 56 404 0503

Trending
Ecologically Balanced World is a Shared Responsibility


“Sustainable and ecologically balanced world is a shared responsibility,” Amadou Diallo, CEO – MEA, DHL Global Forwarding, firmly points out as the most pressing need of the hour. The statement underpins the vision defined for The Integrator’s August issue.
Notably, it is a collective success of modern thinking and universal acknowledgment, based on the “UN Paris Accord (2015),” that we got over 190 countries to agree on the framework to battle against global climate change and increasing emissions. Gulf Corporation Council (GCC) countries are enthusiastically committed to science-based target initiatives and strive to succeed with good results. Arthur D. Little’s recent report highlights GCC’s top performance across telecom, logistics, real estate, and financial industries in conducting sustainable initiatives and reducing carbon footprint.
Construction & architecture, energy & natural resources, packaging & consumer goods, and industrial manufacturing are highly responsible industries for sustainability. Focusing on ecological balance, each of their efforts creates a big impact.
In addition to a cover story on “sustainable logistics,” The Integrator brings in several perspectives from construction, financials, and IT on the subject. Check it out here: https://issuu.com/varmea/docs/the_integrator_-_august_2022
We are happy to announce the launch of the “LEADER” segment that features high-profile personalities on the magazine’s cover with an exclusive interview on the inside pages. The publication is open to influential figures across the diverse arena of IT, ICT, BFSI, logistics, and hospitality industries.
Similarly, the ICT Champion Awards 2022, our prestigious awards event, is scheduled to conduct on October 10, 2022 – on the sidelines of GITEX. It will recognize MEA’s leading ICT Vendors, Distributors, Resellers, and eminent personalities in 30+ categories and we seek your full support to make it a huge success!
Subscribe to us on LinkedIn.
Read, engage, and motivate!
Thank you!
Murali Margassery
Assistant Editor


Automotive
Anticipating the Automotive Aftermarket: Preparing the GCC Aftermarket for a Software-Led Future

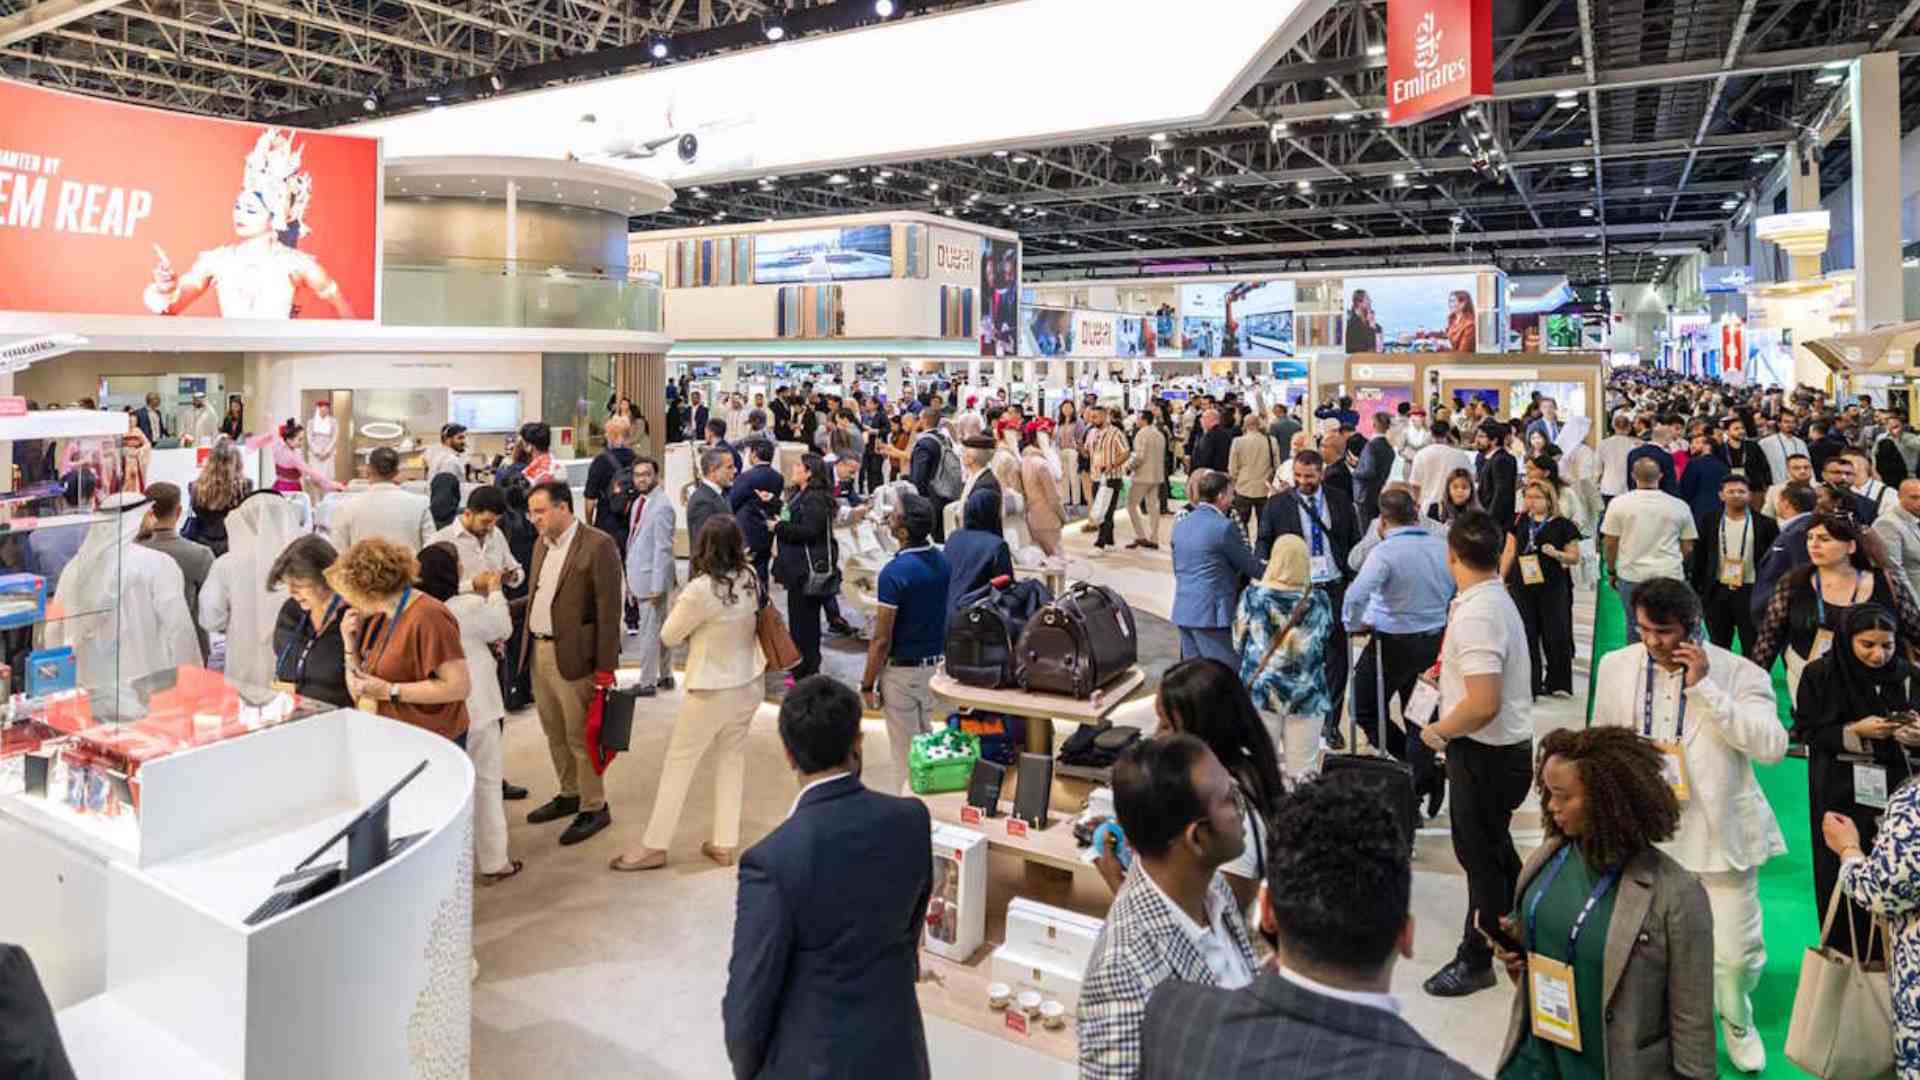
The GCC aftermarket is preparing to support a more diverse vehicle mix as electrification, connected systems and software-led technologies develop at different speeds across regional markets.
In this exclusive, Tommy Le, Show Manager of Automechanika Dubai, explains how aftermarket businesses can remain relevant as vehicle technologies and customer expectations change, why workshop and workforce readiness must advance together, and how industry platforms can support long-term collaboration across the region.
From your conversations with manufacturers, distributors and industry associations, what is the most significant transformation currently reshaping the regional aftermarket?
From our conversations with manufacturers, distributors and industry associations, the most significant change is the diversification of demand. It is not happening uniformly across the GCC, but businesses increasingly need to support conventional vehicles alongside hybrids, EVs, connected systems and a growing mix of brands. Dubai offers one indication of the direction: according to the Dubai Electricity and Water Authority, registered EVs increased from 37,486 at the end of 2024 to 47,944 at the end of 2025, a rise of nearly 28%. Each technology and brand brings different parts, software, diagnostics and servicing needs. Companies therefore need stronger market intelligence, flexible supply chains and closer collaboration. The businesses that remain relevant will respond quickly without compromising quality, safety or trust.
How are electrification, connected vehicles, advanced diagnostics and software-led technologies changing the requirements of aftermarket businesses?
They are changing both what businesses sell and the capabilities they require. A repair may now involve electronic diagnosis, sensor calibration, battery and thermal-system assessment, or access to vehicle-specific technical information. The complexity is already visible: a study by the Insurance Institute for Highway Safety found that about half of owners whose crash-avoidance systems were calibrated following vehicle damage reported continuing problems after the repair. That reinforces the need for correct tools, current procedures and trained technicians. Looking ahead, software-led servicing and predictive maintenance could create faster and more transparent customer experiences, but only where workshops have authorised data access, compatible systems and appropriate diagnostic infrastructure. Internationally, software governance is becoming more formalised through measures such as United Nations Economic Commission for Europe Regulation No. 156 on software updates and software update management systems. The opportunity is significant, but capability cannot be assumed to be universal.
As the vehicle mix becomes more diverse, how must parts supply chains and service networks support conventional, hybrid and electric vehicles simultaneously?
Conventional vehicles will remain central to the regional fleet even as hybrid and electric adoption grows at different rates. According to the Dubai Electricity and Water Authority, the number of registered EVs in Dubai increased by nearly 28% during 2025, showing why the aftermarket must prepare for several technology cycles at once. Distributors need visibility of vehicle populations and demand to balance availability against excess stock, backed by traceable sourcing. Service networks must decide which capabilities belong in every workshop and which can sit in specialist centres. Horizontal collaboration could let independent businesses share high-cost diagnostic or calibration resources, technical knowledge and regional support without duplicating investment.
Where are the most urgent workshop-readiness gaps, and what roles should manufacturers, training institutions and industry platforms play in closing them?
Skills are the most urgent gap because equipment creates value only when people can use it safely and accurately. Workshops need technicians who understand high-voltage systems, advanced diagnostics, software-led repair and ADAS calibration, supported by current technical data, safe working areas and clear procedures. The consequences of incomplete capability are tangible: according to the Insurance Institute for Highway Safety, around half of respondents whose crash-avoidance systems were calibrated after vehicle damage reported continuing issues. The US National Highway Traffic Safety Administration also advises that high-voltage work requires vehicle-specific guidance and properly trained personnel. Manufacturers can provide recognised training pathways, vocational institutions can build foundations, and industry platforms can connect them. We also need to show young people that the aftermarket now combines engineering, data and software, offering credible technology-led careers rather than only traditional mechanical roles.
How has your commercial experience shaped your strategy, and what is your long-term ambition for Automechanika Dubai as it moves to Dubai Exhibition Centre in November 2026?
Working across commercial and exhibitor roles has shown me that different parts of the industry experience change in very practical ways. Manufacturers may focus on market access, distributors on dependable supply, and workshops on tools, training and technical support. My role is to find where those needs meet and build useful connections. The move to Dubai Exhibition Centre opens a new phase for the show, with opportunities to improve the visitor experience, connectivity and the way knowledge is shared. I want Automechanika Dubai, taking place from 10–12 November 2026, to develop as a year-round industry platform where businesses exchange insight, understand emerging technologies and form partnerships. It must remain a commercial marketplace while helping the aftermarket anticipate change rather than react to it.
Note:Historical 2025 figures: Automechanika Dubai welcomed visitors from 161 countries and exhibitors from 63 countries at its 2025 edition. Following 22 editions at Dubai World Trade Centre, the exhibition will take place at Dubai Exhibition Centre (DEC) for the first time in 2026. These figures describe the 2025 edition and are not projections for 2026.
As GCC businesses expand into new markets and increasingly complex supply chains, traditional credit assessment is giving way to a more predictive approach. In this interview with Mohamad Jomaa, CEO and Country Manager for GCC and Egypt at Coface, we explore how real-time data, AI and early-warning intelligence are helping CFOs anticipate payment risk, protect working capital and make more confident decisions across customers, suppliers and markets.
What is driving the shift from relationship-based credit decisions to predictive credit intelligence among CFOs in the GCC?
Relationships remain fundamental to business in the GCC and will continue to be. What has changed is the speed at which companies are expanding into new sectors, markets, and supply chains. As organizations grow beyond their traditional networks, finance leaders need additional tools to assess customers, suppliers, and partners they may not know well.
Today’s CFOs are increasingly complementing business relationships with data-driven insights. They need greater visibility not only into credit risk, but also into supply chain dependencies, corporate ownership structures, payment behavior, and potential vulnerabilities across their ecosystem.
Predictive intelligence provides that forward-looking perspective. It helps businesses make faster and more informed decisions, strengthen due diligence processes, identify opportunities, and anticipate risks before they impact cash flow, operations, or growth plans.
What trends are you currently seeing in payment delays and corporate defaults across the UAE and Saudi Arabia?
The overall economic outlook in both the UAE and Saudi Arabia remains positive, supported by ambitious investment programs and continued economic diversification. At the same time, businesses continue to face uneven market conditions across sectors.
Drawing on Coface’s unique experience as a global trade credit insurer, we monitor payment behavior, claims activity, and credit events across millions of companies worldwide. What we are seeing today is not necessarily a significant increase in corporate failures, but rather signs of pressure on working capital in specific industries.
Payment delays have become more common in sectors exposed to longer project cycles, margin pressure, or supply chain disruptions. For finance leaders, the challenge is distinguishing between temporary liquidity constraints and deteriorating credit quality. This is where access to real-time payment data and early warning indicators becomes particularly valuable.
How can better credit intelligence improve cash flow, working capital, and overall financial resilience?
Better intelligence enables businesses to make more informed decisions across the entire customer and supplier lifecycle. By combining financial information, payment behavior, sector analysis, ownership data, Country Risk Assessments, Sector Risk Assessments, and ongoing monitoring, organizations gain a much clearer view of both risk and opportunity.
This has a direct impact on cash flow and working capital. Businesses can identify signs of financial stress earlier, reduce exposure to overdue accounts, prioritize collections efforts, and allocate credit more effectively. Access to real-time information and early warning indicators allows companies to act before issues translate into cash flow challenges.
Increasingly, however, financial resilience is not only about customer risk. It is also about understanding vulnerabilities across the supply chain. A disruption involving a key supplier, contractor, or logistics partner can have a significant impact on operations, costs, and liquidity. Better intelligence provides greater visibility into these critical dependencies, helping organizations identify concentration risks, assess the financial health of strategic partners, and strengthen business continuity planning.
As companies expand into new markets and engage with new customers, suppliers, and partners, they need confidence in who they are doing business with. Access to reliable data on ownership structures, financial health, payment behavior, sector outlooks, and country risk helps organizations make better-informed decisions and reduce uncertainty when entering new commercial relationships.
. What warning signs should finance leaders monitor before extending credit to new customers or entering unfamiliar markets?
Financial statements remain important, but they only tell part of the story. Finance leaders should also evaluate payment behavior, ownership structures, management stability, sector outlooks, supplier concentration, and exposure to geopolitical or regulatory risks.
One of the most valuable early warning indicators is a deterioration in payment behavior. In many cases, companies begin showing signs of financial stress long before it becomes visible in published financial statements.
Similarly, supply chain concentration risks should not be overlooked. A business may appear financially sound while remaining highly dependent on a small number of customers, suppliers, or projects. Understanding these dependencies is an increasingly important component of due diligence.
Effective credit decisions require a broader assessment of the business ecosystem rather than focusing solely on traditional financial metrics.
This is why a combination of company information, payment behavior, Country Risk Assessments, Sector Risk Assessments, and supply chain intelligence is increasingly becoming an essential part of the decision-making process.
How are AI and predictive analytics changing the way organizations assess credit risk and make financing decisions?
Financial statements remain important, but they only tell part of the story. Finance leaders should also evaluate payment behavior, ownership structures, management stability, sector outlooks, supplier concentration, and exposure to geopolitical or regulatory risks.
One of the most valuable early warning indicators is a deterioration in payment behavior. In many cases, companies begin showing signs of financial stress long before it becomes visible in published financial statements.
Similarly, supply chain concentration risks should not be overlooked. A business may appear financially sound while remaining highly dependent on a small number of customers, suppliers, or projects. Understanding these dependencies is an increasingly important component of due diligence.
Effective credit decisions require a broader assessment of the business ecosystem rather than focusing solely on traditional financial metrics.
This is why a combination of company information, payment behavior, Country Risk Assessments, Sector Risk Assessments, and supply chain intelligence is increasingly becoming an essential part of the decision-making process.
What sectors in the GCC are showing the strongest opportunities, and where are the highest risks based on your data?
Our outlook combines insights from Coface’s payment experience data, claims observations, Country Risk Assessments and Sector Risk Assessments. Together, these provide a comprehensive view of the opportunities and vulnerabilities shaping the business environment across the GCC.
We continue to see attractive opportunities in sectors supported by economic diversification strategies, digital transformation, infrastructure investment, logistics development and the energy transition. These areas are benefiting from sustained investment, strong policy support and growing regional demand.
At the same time, businesses operating in sectors facing tighter margins, elevated input costs, project execution challenges or longer payment cycles require closer monitoring. What is important to remember is that risk is rarely uniform across an entire sector. Performance can vary significantly from one company to another depending on its financial strength, competitive positioning, customer base and exposure to broader supply chain dynamics.
Looking ahead, how do you see the role of predictive intelligence evolving within corporate finance over the next three to five years?
Over the next three to five years, predictive intelligence will become an integral component of decision-making across finance, procurement, sales, treasury, compliance, and risk management functions.
We expect companies to move beyond using intelligence solely for credit assessments and begin embedding it throughout the business. This includes supplier selection, customer onboarding, supply chain management, compliance checks, investment decisions, and strategic planning.
The organizations that will be most successful are those that can combine technology, data, and human expertise to obtain a holistic understanding of their business ecosystem.
In an increasingly interconnected world, success will depend not only on knowing who you do business with, but also on understanding the risks and opportunities across the entire value chain. Access to reliable, forward-looking intelligence will therefore become a key competitive advantage, helping companies grow confidently while remaining resilient in a rapidly changing environment.
BY: Owais Mohammed, Regional Lead & Sales Director at WD for the Middle East, Africa, Turkey, and the Indian Subcontinent
The UAE’s ambition to become a global AI powerhouse is well established. Government investment is flowing, infrastructure is scaling, and organisations across every sector are accelerating their AI programs. But beneath the strategic announcements and the technology deployments, a fundamental question goes unanswered: is the data storage infrastructure underpinning all this built for what comes next?
For many organisations, the honest answer is: not yet. Storage is rarely the first conversation in an AI strategy discussion. It tends to be treated as a commodity decision made late in the planning cycle, long after the headline architecture choices like GPUs/CPUs have been made. That approach made sense in simpler times, but not in today’s data-driven AI economy.
The scale of what is coming
To understand why, organisations need to understand the sheer data volume that is coming their way. Global data creation is forecast to rise to 718.5 Zettabytes (ZB) through 2030 (IDC source: Market Forecast: IDC Global DataSphere Forecast, 2026-2030, June 2026, Doc #US53425426), more than tripling in five years.
AI is both a driver and a consumer of this growth. Every model trained, every inference run, every data pipeline operating continuously across a distributed architecture is generating and demanding access to data at a scale that earlier generations of infrastructure were not designed to support.
Businesses that will absorb this growth successfully are not those with the fastest individual components. They are those with architectures designed to handle volume, variety, and velocity simultaneously, at a cost that remains economically sustainable as scale increases. That is the storage strategy challenge that needs to be addressed upfront and not as an afterthought.
Why a single technology cannot solve it
A common mistake is to frame the storage decision as a technology choice: SSDs versus HDDs, flash versus spinning disk, performance versus capacity. The world’s most sophisticated storage operators, including hyperscalers and major cloud service providers, have already moved past this framing. They do not choose one technology. They deploy multiple of them, in a tiered architecture that places data on the medium best suited to its requirements.
The logic is straightforward. SSDs deliver the high IOPS and low latency that real-time, performance-critical applications demand. HDDs provide the massive capacity and cost efficiency required for the vast middle tier of active and warm data, and currently continue to represent approximately 63% of worldwide installed storage capacity through 2030. Tape generally handles archival, regulatory, and compliance workloads where retrieval times of hours or days are acceptable, representing just under 8% of worldwide installed cloud storage capacity in 2025.
These are not competing technologies. They are complementary ones, each serving a distinct purpose within a coherent architecture. The question is how each is deployed where it delivers the greatest value.
Making tiered architectures work in practice
Knowing that tiered storage is the right model and implementing it effectively are two different things. At the scale hyperscalers operate, where storage volumes are measured in hundreds of exabytes, manual allocation of data across tiers is neither practical nor efficient. Nor can all data live on cost prohibitive flash. The mechanism that makes tiered architecture manageable is software-defined storage (SDS), which pools resources centrally and provisions capacity dynamically based on demand. Rather than pre-allocating fixed capacity to individual applications, SDS responds to where data needs to be, improving overall utilisation and reducing waste.
Together, tiered architecture and SDS provide the flexibility and economic efficiency that hyperscale environments depend on. But this model is not the exclusive preserve of the world’s largest operators. For emerging infrastructure providers, including Neoclouds that are expanding rapidly across the region, the same principles apply. Architecture decisions made today will determine whether future growth is economically sustainable or structurally constrained. The window to get this right is earlier than many organisations assume.
Innovation at the storage level
Architectural thinking also changes how storage technology itself must evolve. An organisation that understands its workloads, plans for data growth, and builds tiered infrastructure will eventually reach the limits of what current storage innovations can deliver. That is why, manufacturers like WD are approaching HDDs not only as a mature, reliable product but as a technology with significant headroom remaining to help increase capacity, lower power and cost effectively scale AI data. They are advancing recording technologies, exploring novel materials, and embedding intelligence at the drive level. The aim is not incremental improvement. It is expanding the boundary of what high-capacity storage can deliver for the architectures customers are building today and the workloads they will run tomorrow.
The leadership dimension
The organisations that navigate the AI era most effectively will not be those that simply procure the latest hardware. It will be those that understand the architectural decisions that determine long-term performance, cost and scale, ask better questions earlier in the planning process, and treat storage infrastructure strategy as a source of competitive advantage rather than a procurement exercise.
Storage sits at the foundation of every AI workload, every data pipeline, and every digital service an organisation delivers. Getting the architecture right is not a technical detail. It is a leadership decision. And in a market moving as quickly as the UAE’s, it is one that deserves to be made with the same rigour and strategic intent as any other.

Al Bustan Centre & Residence concludes successful participation at Arabian Travel Market 2026

From 350+ Applications to One Champion: School of Cyber Defense Final Stage at GISEC GLOBAL 2026

Half a billion people live with arthritis: MEAF puts early action at the heart of World Arthritis Day 2026


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
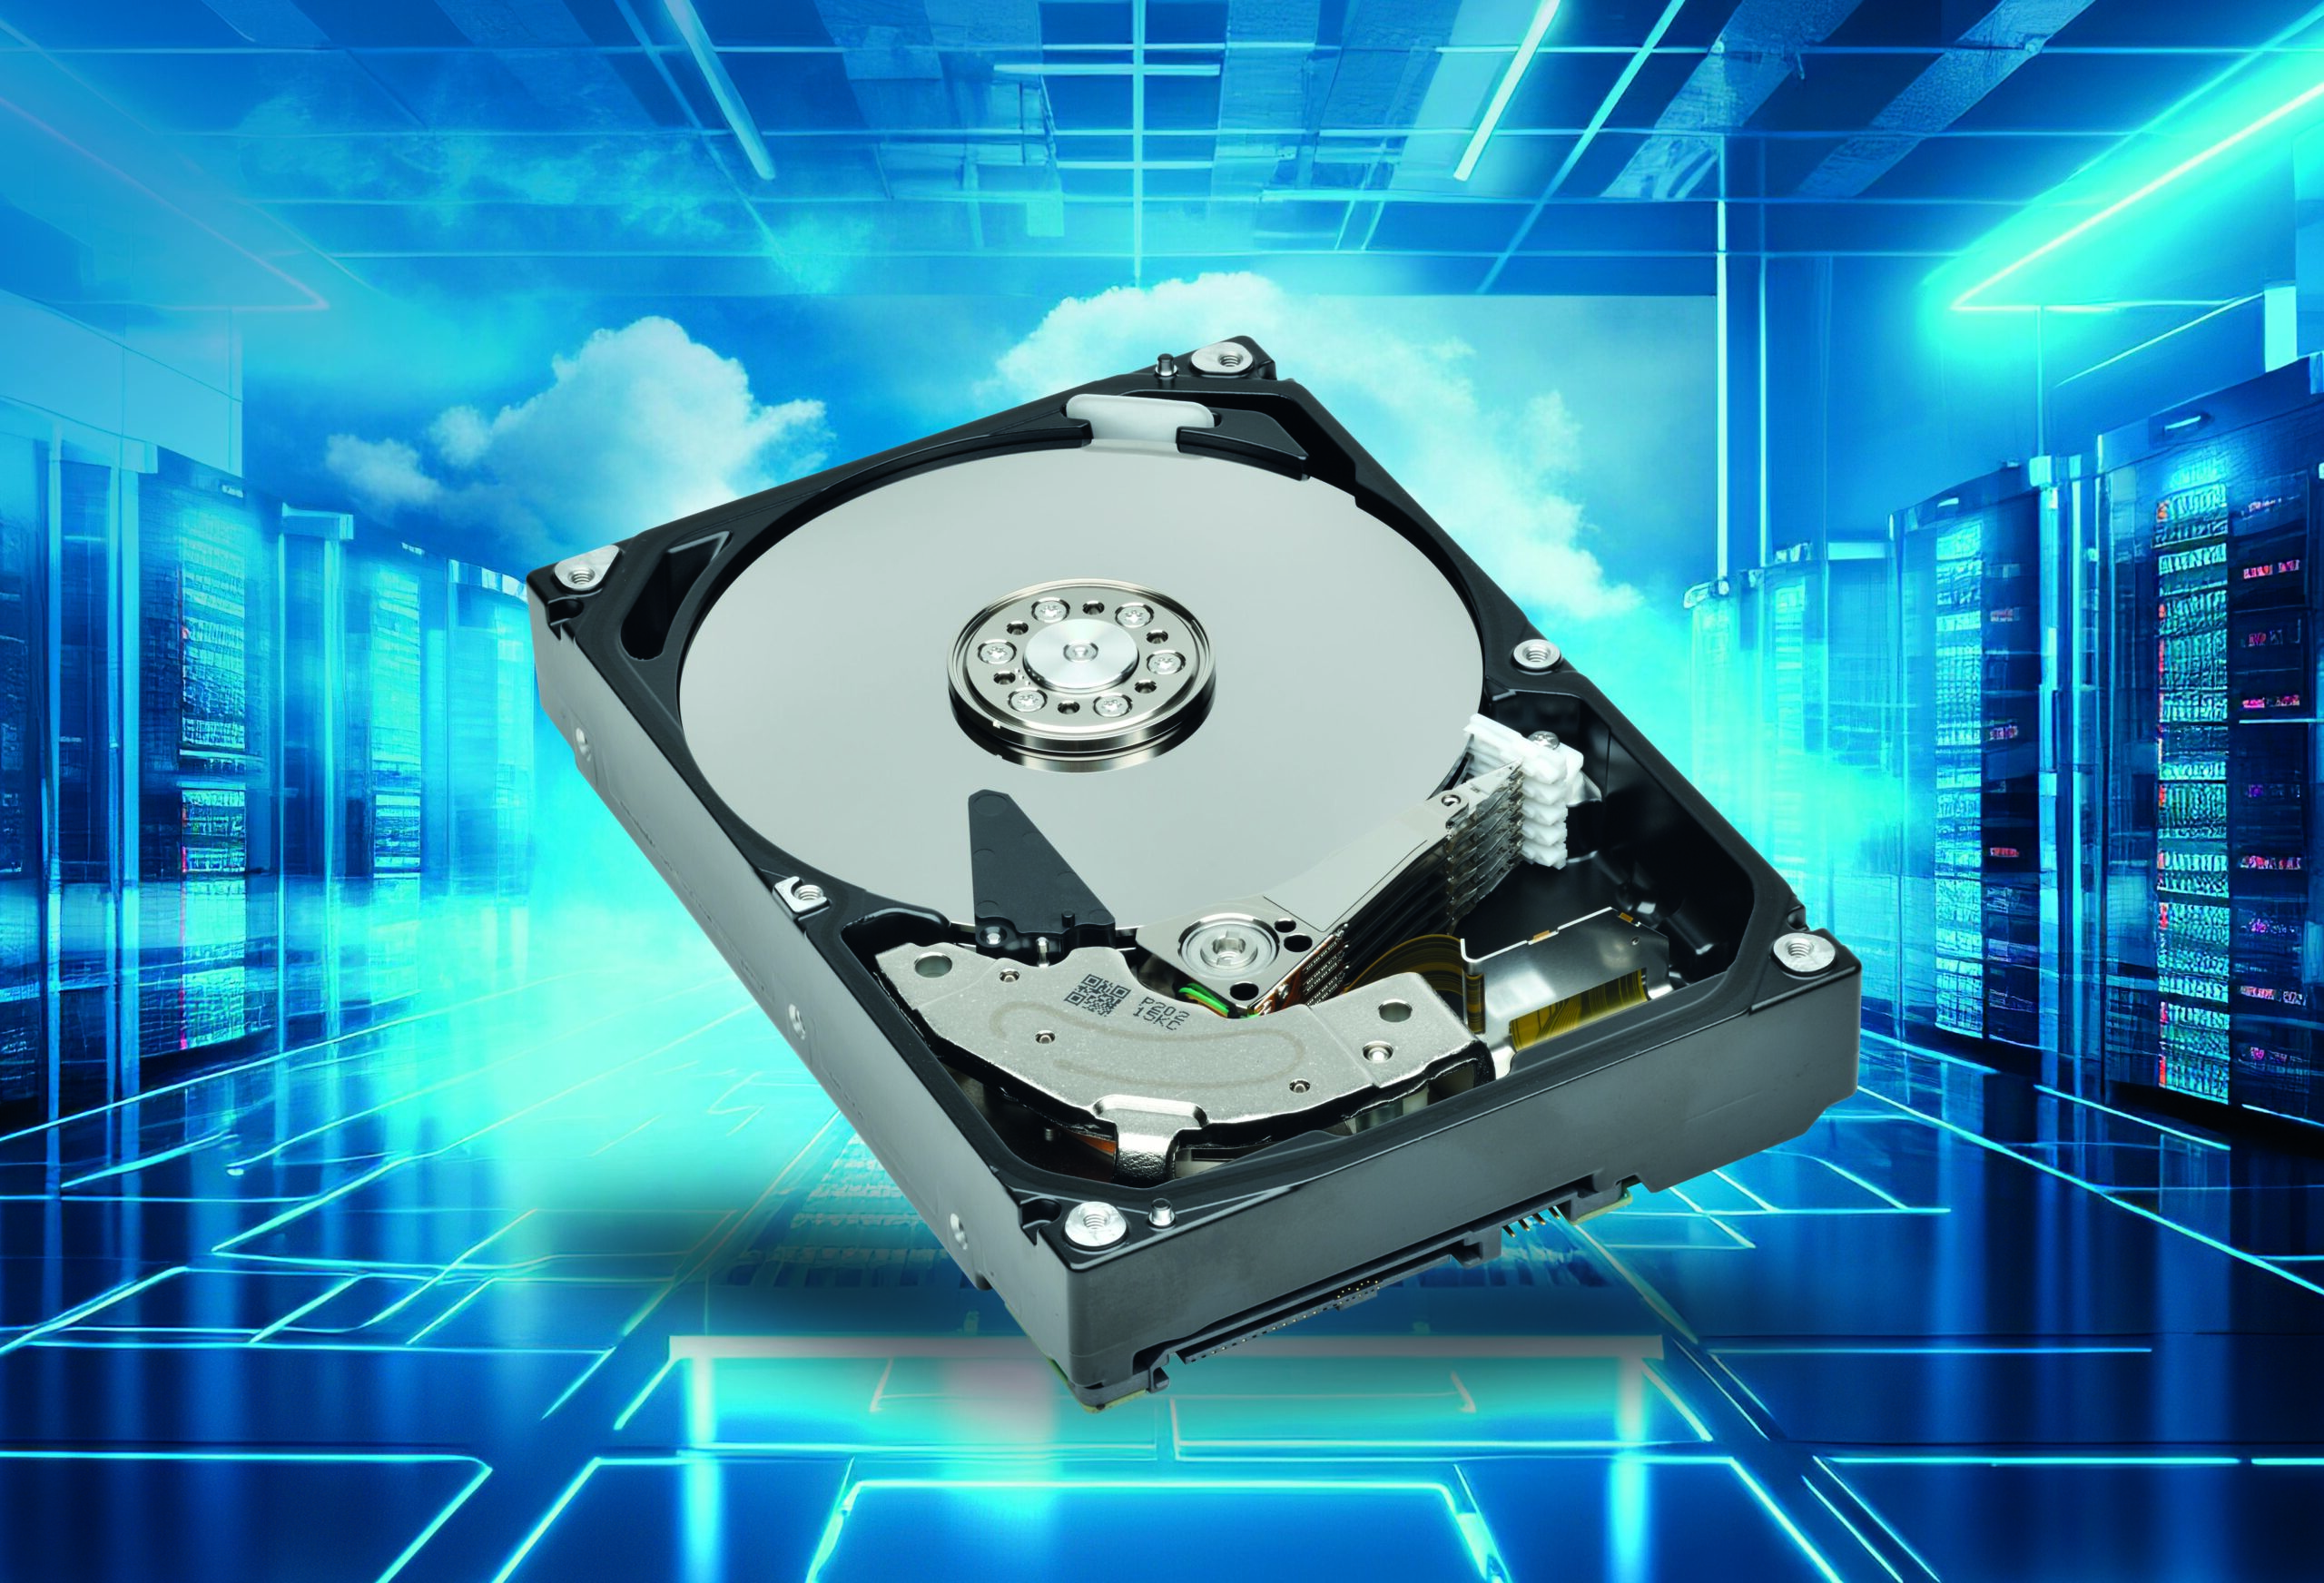
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai