 Have a question? +971 56 404 0503

Financial News
RAKBANK more than doubles its quarterly Net Profit at AED 450M for Q1’23

RAKBANK delivered a Net Profit increase of 105% for Q1 2023 driven by a robust and diversified growth on both sides of the balance sheet. This was underpinned by strong sales momentum and lower cost of funds.

Raheel Ahmed – CEO of RAKBANK
- Total Income performance was supported by a strong net interest income of AED 788.8M, up 46.0% YoY. Net interest margins increased to 4.9% against 3.8% (Q1’22) and continues to be among the highest in the Industry. Q1’23 non-interest income of AED 284.4M, up 52.5% YoY. The growth in non-interest income was driven by higher forex and derivative income.
- Gross loans & advances at AED 38.7B, reflecting a 1.4% increase compared to 31 December 2022 on the back of a changing balance sheet mix in line with the strategic direction of the bank.
- Customer deposits stood at AED 46.4B, an increase of 3.3% compared to 31 December 2022. The Bank has a strong Current & Saving Account (CASA) franchise with the CASA ratio of 70.5%.
- Cost of Risk remained low due to the Bank’s diverse business mix and resilient UAE economic environment, leading to a 30.9% reduction in impairments as against Q4’22. Impaired Loan provision coverage ratio increased to 192.1% against 137.8% in Q1’22, remaining one of the strongest in the industry.
The Bank achieved balanced growth across all Business Segments:
Personal Banking:
- Gross loans & advances at AED 19.1B are up 1% YoY and +2% against FY’22 driven by the sales momentum across products with balance sheet for Auto loans +6%, Mortgages +5% and Personal loans +0.3%.
- Customer deposits of AED 16.7B, are up 22% YoY and +6% during the quarter driven by higher Term deposits +30% & CASA +0.3%.
- Q1’23 income supported by net interest income of AED 229M, +19.0% YoY and non-interest income of AED 123M, +1% YoY.
Business Banking:
- Gross loans & advances of AED 9.3B, are up 12% YoY and +3% against FY’22 mainly through higher volumes for Rak business loans +5%.
- Customer deposits of AED 19.7B, are up 14% YoY and +7% during the quarter driven by higher CASA deposits +7% & Term deposits +2.7%.
- Q1’23 income supported by net interest income of AED 337M, +57.0% YoY and non-interest income of AED 77M +6% YoY.
Wholesale Banking & Others:
- Gross assets (including lending to banks) of AED 19.8B, are up 13% YoY and +1% against FY’22 mainly driven by higher FI bank lending +2%.
- Customer deposits of AED 9.9B, are up 13% YoY and +7% during the quarter.
- Q1’23 income supported by net interest income of AED 224M, +68.0% YoY and non-interest income of AED 84M against a loss of 8Mn in Q1’22.
RAKBANK delivered strong shareholder returns with ROE of 19.4% and ROA of 2.8%, and remained highly liquid and well capitalized.
- The Bank’s Capital Adequacy Ratio (CAR) was at 16.8%.
- The regulatory eligible liquid asset ratio at 14.8%, compared to 12.8% as at 31 December 2022, and the advances to stable resources ratio stood comfortably at 81.8% compared to 79.7% at the end of 2022.
- Cost-income ratio improved to 36.2% driven by strong cost discipline, automation and digitization.
- The Bank’s non-performing loans ratio improved to 3.0% against 3.6% in Q1’22.
Raheel Ahmed, CEO of RAKBANK said, “Delivering on our multi-year strategy, we accelerated our growth and achieved a record net profit of AED 450M and a record total income of AED 1,073M for the quarter. In addition to this impressive growth, I am very pleased with the progress we are making in laying the foundation for sustainable growth.
In diversifying our income sources, we achieved robust growth on both sides of the balance sheet, across interest and fee incomes, and in all our segments. In terms of building deeper customer relationships, we achieved strong growth in digitally active customers with digital transactions growing by 12% YoY. Our high CASA ratio in our deposit base of 70.5% despite the high interest rate environment is a testament of the strong relationships we built with our customers and clients. We enhanced our operational leverage and improved our cost-income ratio through our strong cost discipline, and our cost of risk reduced via diversifying our business mix. The Bank remains well capitalized and liquid with a Capital Adequacy Ratio of 16.8% and an Eligible Liquid Asset Ratio of 14.8%. As a result of our progress, we achieved an ROE of 19.4% and ROA of 2.8%.
Being one of the largest SME banks in the UAE, we continue to back entrepreneurs and start-ups by opening more than 4,000 business accounts in Q1 2023, of which 1,600 accounts were opened for start-ups. Similarly, we disbursed AED 571M in business loans, out of which AED 394M were disbursed for new business loan customers.
As we grow, we are investing heavily in technology while maintaining cost discipline to digitize customer journeys, upgrade core data architecture, and revamp compliance and risk infrastructure. This investment will enable RAKBANK’s journey to provide a superior customer experience that is characterized by its hyper-personalization and relevance. The recent launch of our first fully digital accounts opening capability with straight-through processing is a good example of how we are digitizing our customer journeys.
Continuing from Q4 2022, we are focusing on expanding strategic hires to lead our growth, and we remain committed to and supporting the career aspirations and ambitions of our colleagues. Special attention is drawn to developing our Emirati talents as we align ourselves to the UAE leadership’s mission of growing and nurturing local talent.
As one of the nation’s leading financial institutions, RAKBANK recognizes our responsibility to support the ‘UAE Net Zero by 2050’ initiative. The team is actively engaged with RAK Government on COP28 submissions, working on financial inclusion and reducing emissions. We continue to support financial inclusion and accelerate digital remittances through our wages protection system partner and the United Nations Capital Development Fund.
Lastly, our outlook for FY 2023 remains positive yet cautious, with the buoyant UAE economy and uncertain global macro set up as backdrops. While we closely monitor the headwinds of inflation, rising interest rates, geopolitical developments, we will continue building on the Bank’s strengths and remain committed to delivering on our strategy.”
| Digital Transactions
+12% YoY |
Card Spends
|
Payment through our rails (In/Out) +9% YoY |
Digitally Active Customers
+15% YoY
|
Financial Highlights for Q1 2023
| Income Statement Highlights | Quarter Results | Variance | |||
| (AED Mn) | Q1’23 | Q4’22 | Q1’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Net Interest Income and net income from Islamic financing | 788.8 | 733.1 | 540.4 | 46.0% | 7.6% |
| Non-Interest Income | 284.4 | 261.6 | 186.5 | 52.5% | 8.7% |
| Total Income | 1,073.2 | 994.8 | 726.9 | 47.6% | 7.9% |
| Operating Expenditures | (389.0) | (371.4) | (372.4) | (4.5%) | (4.7%) |
| Operating Profit Before Provisions for Impairment | 684.2 | 623.3 | 354.6 | 93.0% | 9.8% |
| Provisions for Impairment | (233.9) | (338.7) | (134.5) | (73.9%) | 30.9% |
| Net Profit | 450.3 | 284.6 | 220.1 | 104.6% | 58.2% |
| Balance Sheet Highlights | Results as at | Variance | |||
| (AED Bn) | Mar’23 | Dec’22 | Mar’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Total Assets | 68.9 | 66.4 | 60.0 | 14.8% | 3.8% |
| Gross Loans & Advances | 38.7 | 38.1 | 37.2 | 4.1% | 1.4% |
| Deposits | 46.4 | 44.9 | 39.8 | 16.4% | 3.3% |
| Key Ratios | Quarter Ratios | Variance | |||
| Percentage | Mar’23 | Dec’22 | Mar’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Return on Equity* | 19.4% | 12.5% | 10.5% | 8.9% | 6.9% |
| Return on Assets* | 2.8% | 1.7% | 1.5% | 1.3% | 1.1% |
| Net Interest Margin* | 4.9% | 4.5% | 3.8% | 1.1% | 0.4% |
| Cost to Income | 36.2% | 37.3% | 51.2% | 15.0% | 1.1% |
| Impaired Loan Ratio | 3.0% | 3.0% | 3.6% | 0.6% | 0.0% |
| Impaired Loan Coverage Ratio | 192.1% | 181.7% | 137.8% | 54.3% | 10.4% |
| Total Capital Adequacy Ratio Basel III** | 16.8% | 16.4% | 16.5% | 0.3% | 0.4% |
| * Annualized | |||||
| **After application of Prudential Filter | |||||
Profitability Growth supported by Income momentum and improvement in Provisions
- Net Profit increased by 104.6% to 450.3M (vs Q1’22 104.6% and Q4’22 58.2%).
- Net Interest Income and Income from Islamic products net of distribution to depositors increased by 46.0% to AED 788.8M (vs Q4’22 7.6%).
- Interest income from conventional loans and investments increased by 79.7%, while interest costs on conventional deposits and borrowings increased by 300.5%. Net income from Sharia-compliant Islamic financing increased by 7.8%.
- Non-Interest Income increased by 52.5% to AED 284.8M (vs Q1’22 52.5% and Q4’22 8.7%), primarily due to forex and derivative income booked in Q1 2023.
- Total Income increased by 47.6% (vs Q4’22 7.9%), benefiting from the balance sheet growth momentum.
- Operating Expenditure was AED 389.0M (vs Q1’22 AED 372.4M), reflecting a 4.5% increase compared to the same period in 2022, and a 4.7% increase compared to Q4 2022, due to the Bank’s growth investments.
- Operating Expenses increased mainly due to higher staff costs, card expenses, and other operating expenses. However, these were partly offset by lower IT expenses, occupancy costs, depreciation, and communication expenses.
- Cost-to-Income ratio for the bank decreased to 36.2% (vs Q1’22 51.2% and Q4’22 37.3%).
- Provision for credit loss increased by 73.9% to AED 233.9M for Q1 2023 compared to Q1 2022, due to prudent precautionary measures in anticipation of expected developments. However, compared to Q4 2022, the provision for credit loss decreased by 30.9% for Q1 2023.
- Net Credit Losses to average loans and advances closed at 2.5% (vs Q4’22 3.4%).
Balance Sheet crosses AED 68.9B with a strong uptick across all customer segments.
- Balance sheet crosses AED 68.9B as the Total Assets increased by AED 2.5B compared to 31 December 2022, reflecting a growth of 3.8%, with an increase in Cash/Central Bank balances by AED 929.2M, Investments by AED 805.8M, Gross Loans and Advances by AED 551.9M and Lending to Banks by AED 480.3M as compared to 31 December 2022.
- Business Banking portfolio increased by AED 264M, Retail Banking by AED 286.2M and Wholesale Banking segment (including bank lending) increased by AED 211M compared to 31 December 2022.
- Business Banking recorded 2.9% growth compared to 31 December 2022 with Business Loans growing by 5.3% and an increase of 1.5% on the Trade and Working Capital Loans portfolio.
- Retail Banking reflected a growth of AED 286.2 M supported by a strong sales momentum across products with Mortgages growing by 4.8% and Auto Loans by 6.4%.
- Non-performing Loans and Advances to Gross Loans and Advances ratio remained same at 3.0% as at 31 March 2023 compared to 31 December 2022.
Robust Growth in Customer Deposits as we continue to be the main bank for most of our customers
- Q1’23 Customer deposits increased by 3.3% compared to 31 December 2022, mainly due to an increase of AED 1,089.5M in CASA deposits and AED 404.7M in time deposits, endorsing the trust our customers place in RAKBANK’s solutions and services. RAKBANK has built a strong CASA franchise with a CASA ratio of 70.5 % as at 31 March 2023.
Strong Capital and Liquidity position
- The Bank’s Capital and Liquidity ratios remained strong.
- With a Total Capital Ratio as per Basel III, after the application of prudential filter, at 16.8% compared to 16.4% at the end of 2022.
- The regulatory eligible liquid asset ratio at the end of 31 March 2023 at 14.8%, compared to 12.8% as at 31 December 2022, and the advances to stable resources ratio stood comfortably at 81.8% compared to 79.7% at the end of 2022.
Healthy Cash Flows from operating activities
- Cash and cash equivalent as at 31 March 2023 were AED 4.7B compared to AED 4.3B as at 31 December 2022.
- Net cash generated from operating activities was AED 1.2B, AED 819.8M was used in investing activities and AED 4.7M used in financing activities.
Impact of Projected Capital Expenditure and Development
- The Group incurred AED 37.3M in capital expenditure in Q1 2023.
- RAKBANK will carry on advancing its investment towards customer-centric technology transformation.
Ratings
RAKBANK gets continuously rated by leading rating agencies with their latest ratings shown in the table below. This rating reflects the institutional strength of the Bank that is backed up by trust and transparency in financial reporting.
| Rating Agency | Last Update | Deposits | Outlook | |
| Moody’s | November 2022 | Baa1 / P-2 | Stable | |
| Fitch | April 2023 | BBB+ / F2 | Stable | |
| Capital Intelligence | August 2022 | A- / A2 | Positive | |
Financial
PATRIZIA appoints Hassan Awada as Senior Executive Officer to lead and accelerate Middle East expansion

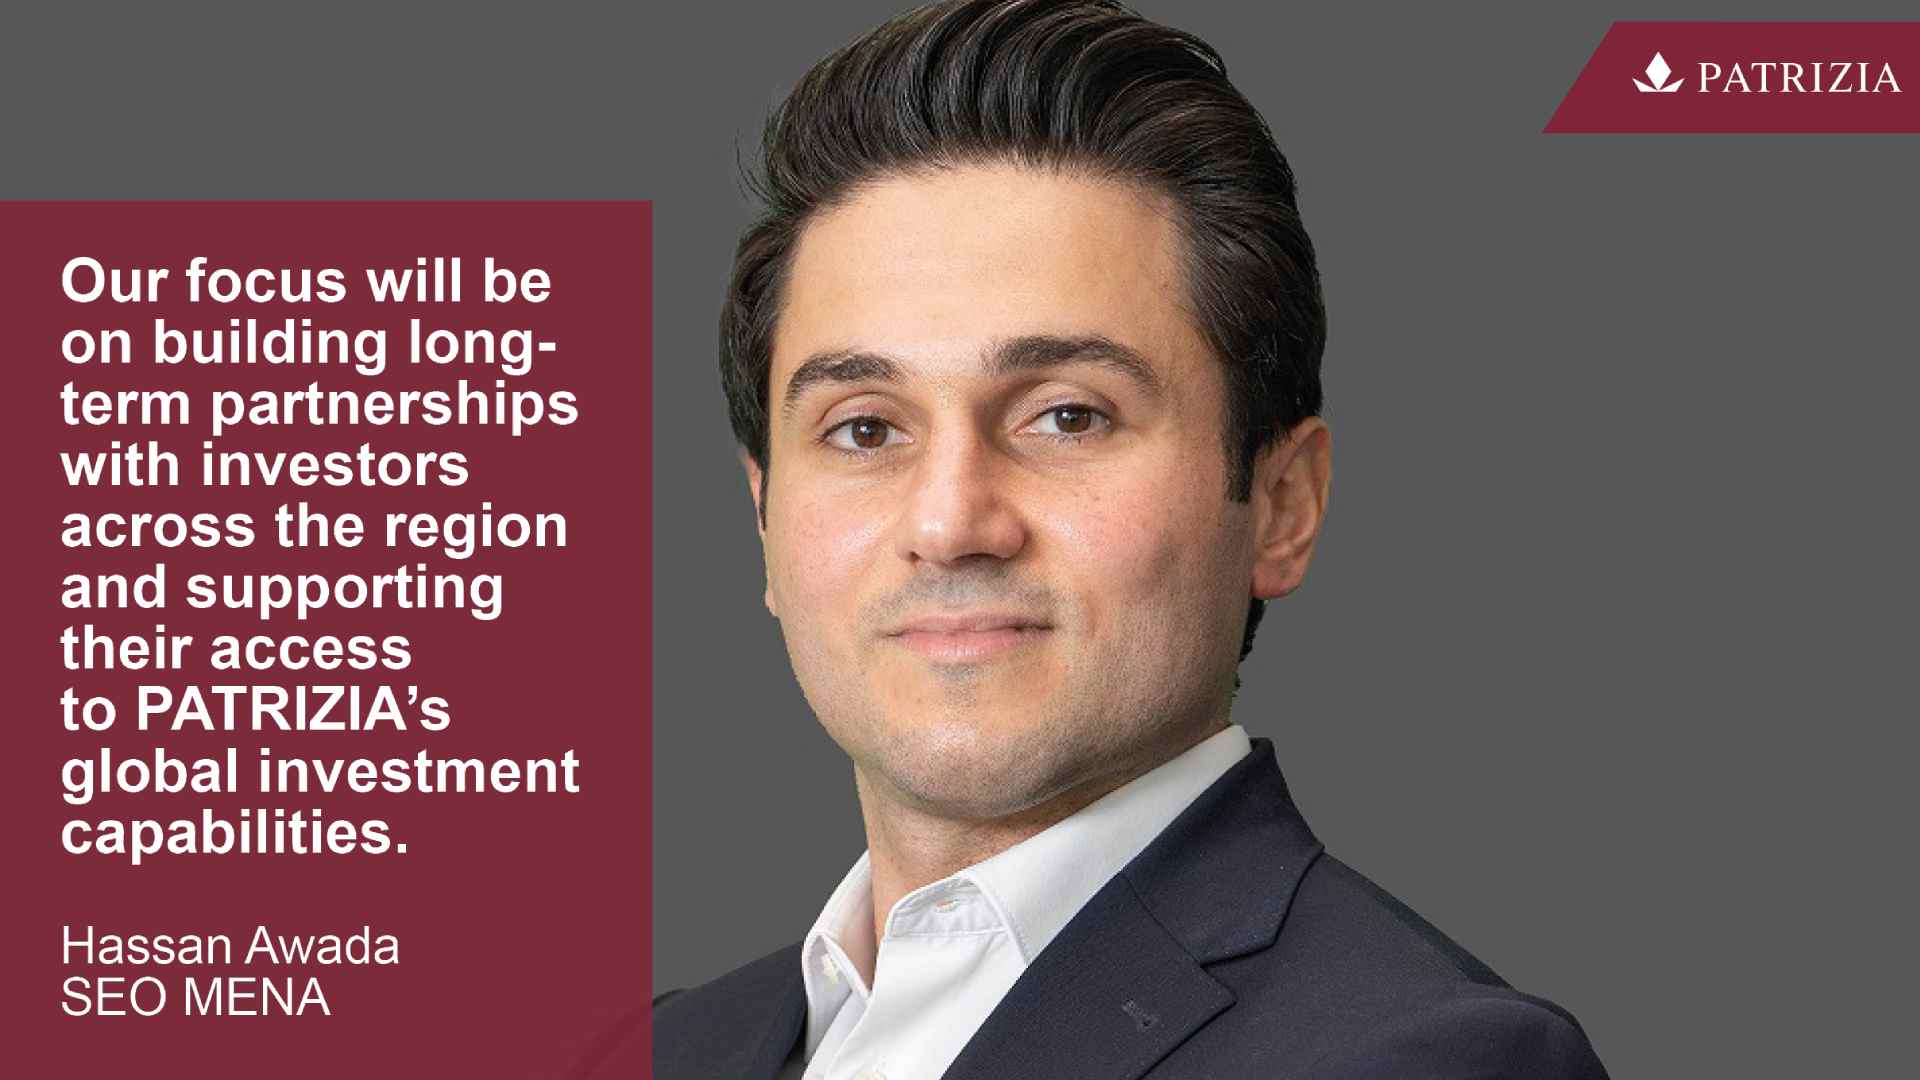
PATRIZIA, a global investment manager in real assets, has announced the appointment Hassan Awada as Senior Executive Officer (SEO), MENA. Based in ADGM, the international financial centre of the UAE’s capital, Abu Dhabi, Awada will lead the continued growth of PATRIZIA’s business across the MENA region, with a focus on deepening relationships with institutional investors and strategic partners and providing access to PATRIZIA’s international real assets investment platform.
Awada brings over 20 years of experience advising institutional investors across the full investment lifecycle, including origination, structuring, execution and asset management. Prior to joining PATRIZIA, he held senior roles at Kroll, Cornerstone Capital, Gleacher Shacklock, PwC and EY.
Konrad Finkenzeller, Head of Client Division at PATRIZIA, commented: “The Middle East is a key strategic region for PATRIZIA, and we continue to see strong demand from investors for direct exposure to high-quality real estate and infrastructure opportunities globally. Hassan’s appointment strengthens our presence on the ground and enhances our ability to deepen relationships with regional investors and connect them with PATRIZIA’s global investment platform.”
Hassan Awada, SEO MENA at PATRIZIA, added: “Real assets have long underpinned Middle Eastern economies and will continue to play a central role in the region’s growth. Meeting increasingly sophisticated investor needs requires tailored, strategic solutions. With its global platform and 42-year track record, PATRIZIA is well positioned to deliver. Our focus will be on building long-term partnerships with investors across the region and supporting their access to PATRIZIA’s global investment capabilities, aligned with their strategic priorities and long-term objectives.”
Arvind Ramamurthy, Chief Market Development Officer, ADGM, said: “This appointment reflects the firm’s strong growth trajectory in the Middle East and its commitment to expanding from Abu Dhabi. It also underscores ADGM’s role as a leading international financial centre, enabling firms to establish and scale their regional presence from the capital.”
With EUR 17.5 billion in Living assets under management, PATRIZIA is one of Europe’s largest residential investment managers and continues to grow its platform across major urban markets. The firm is currently delivering new housing across a number of European markets, including Germany, UK & Ireland, Spain and Belgium, reflecting the scale of its European platform. Alongside Living, PATRIZIA is expanding its infrastructure platform across energy, digital and smart city assets, supporting the transition to low-carbon and connected economies while delivering long-term, resilient returns for investors.
Financial
Fimple adds five GCC financial institutions in first year, targets doubling regional customer base
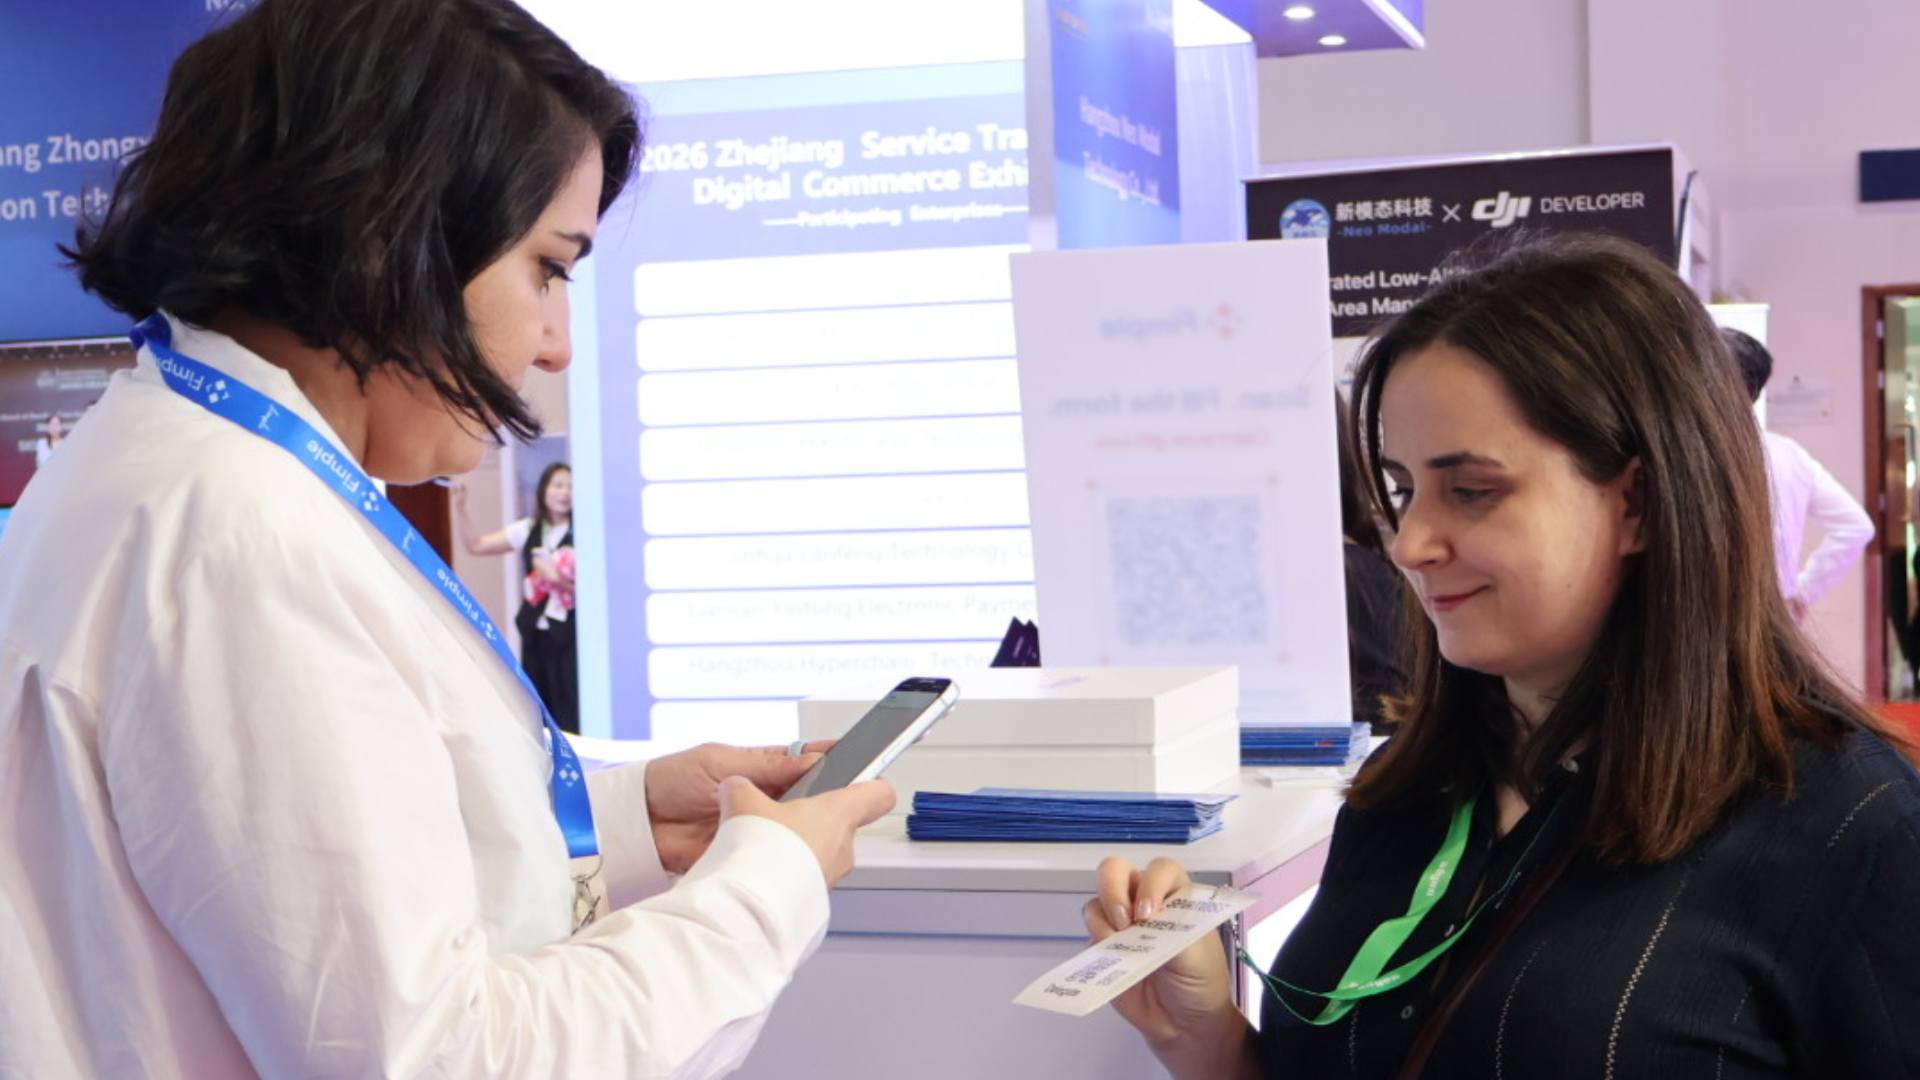
Fimple, an AI-native, API-first, composable financial platform, has signed five financial institutions across the GCC within its first year in the region and plans to double its regional customer base.
Fimple established its Dubai presence in October 2025 and has grown from zero to five GCC customers in 12 months. The region now accounts for close to a fifth of its global customer base of more than 35 financial institutions across 10 countries, making it the company’s fastest-growing region.
The company has also opened an office in Riyadh and plans to expand its customer and delivery presence across the GCC, serving institutions with teams based within the region.
Fimple’s regional growth comes as the UAE continues to advance its ambitions across Islamic finance and financial technology. Under the UAE Strategy for Islamic Finance and Halal Industry, the country aims to increase local Islamic bank assets from AED 986 billion to AED 2.56 trillion by 2031. (Source: UAECabinet.ae)
Dubai is also advancing its ambitions in AI-enabled financial services, with the Dubai International Financial Centre (DIFC) announcing plans in 2026 to become the world’s first AI-native financial centre. (Source: Dubai Media Office/DIFC)
“The UAE is an important market for Fimple because financial institutions here are moving quickly on both Islamic finance and new technology,” said Amr Kandel, GCC Country Manager and Product Director at Fimple. “Banks want to launch products faster, respond to local market needs and modernise without having to change everything at once. The growth we’ve seen in our first year shows there is real appetite for that.”
Islamic finance is a key driver of Fimple’s growth in the GCC. The platform enables financial institutions to run conventional and Islamic finance within the same system, with a range of Sharia-compliant financing and investment structures built into its product engine.
Fimple’s regional customers include Mawarid Finance, a UAE Islamic finance provider that entered into a strategic agreement with Fimple in June 2026.
As banks look to move AI from pilot projects into wider use, Fimple says the underlying core banking infrastructure is becoming increasingly important.
“Banks are already experimenting with AI, but the systems underneath need to be ready for it,” Kandel said. “If the core can’t provide the right data or connect easily with new technology, AI can get stuck at the pilot stage. That’s why the core matters.”
Fimple has built three banking AI agents covering independent audit report processing, customer intelligence from official notices and risk screening across official sources. The agents operate on the Fimple platform with human approval required for each action and full traceability. Further agents are planned as part of the company’s 2026–2027 roadmap.
According to Fimple, it implements a full working core in three to six months on average. Its composable architecture also enables financial institutions to connect selected modules to existing systems rather than replacing their entire core infrastructure at once.
“The GCC has become our fastest-growing region in just one year, and we expect to double our customer base here,” said Mücahit Gündebahar, CEO and Co-founder of Fimple. “We are growing our team and presence in the region so we can support customers locally as we expand across the GCC.”
Fimple will participate as a Gold Sponsor of Seamless Middle East 2026, taking place from Sept. 22–24 at Dubai World Trade Centre. The company will exhibit at stand G64, with Kandel delivering the session “Beyond the AI Hype: Why the Future of Banking Depends on an AI-Ready Core” on Sept. 23 at Stage 1, Fintech Forum.
Financial
Al Masraf and Moody’s Sign Strategic Agreement to Strengthen Risk Intelligence and Credit Capabilities
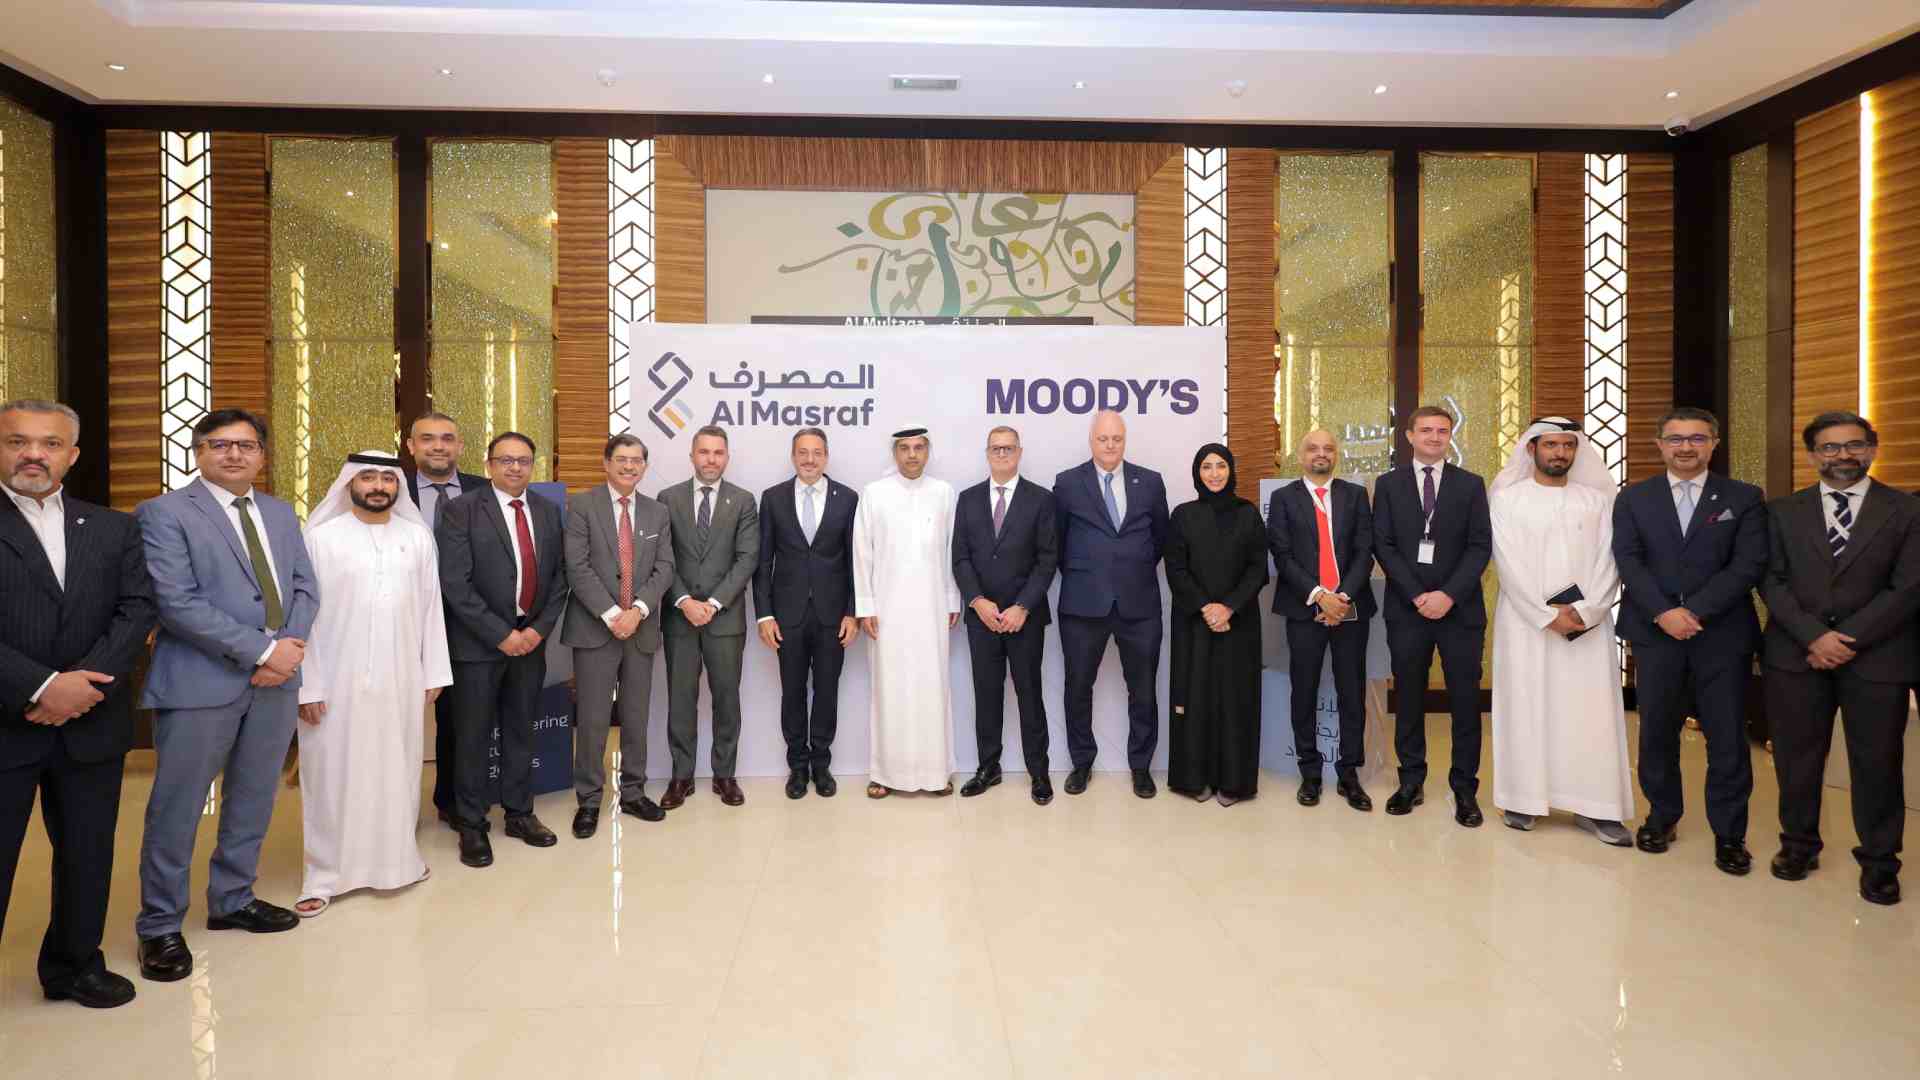
Al Masraf has signed a strategic agreement with Moody’s, a global provider of financial intelligence and risk assessment, marking an important step in strengthening the Bank’s risk management and credit capabilities through enhanced data, insights and technology.
The agreement was formalized during a signing ceremony held in Abu Dhabi, bringing together senior leadership from Al Masraf and Moody’s. The collaboration reflects both organizations’ commitment to leveraging advanced intelligence and risk expertise to support informed, data-driven decision-making in an increasingly complex financial environment.
As risks become increasingly interconnected and the financial landscape continues to evolve, access to timely, reliable and actionable intelligence is becoming essential for financial institutions. Through its combination of data, intelligence, risk expertise and technology, Moody’s helps organizations better understand interconnected risks.
The partnership will further support Al Masraf’s continued focus on strengthening its risk management framework, enhancing credit decision-making and building resilient, forward-looking capabilities that support sustainable growth.
Commenting on the occasion, Fuad Mohamed, CEO of Al Masraf, said: “At Al Masraf, we believe that sustainable growth is built on the strength of our ability to understand risk, anticipate change and make informed decisions. Our collaboration with Moody’s represents an important step in advancing our risk and credit capabilities through deeper intelligence, data and technology.”
He continued: “As the financial landscape continues to evolve, partnerships of this nature enable us to strengthen our resilience, enhance decision-making and create greater value for our customers and stakeholders. We look forward to building on this collaboration as we continue to shape a more agile, intelligent and future-ready Al Masraf.”
“We are delighted to partner with Al Masraf on an important step in modernizing its corporate lending operations. By bringing greater automation, efficiency, and insight to the credit journey, Moody’s is helping the bank build a future-ready operating model that enables faster, better-informed lending decisions, strengthens governance, and enhances risk management.” said Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East at Moody’s.
Senior representatives from both organizations attended the signing ceremony.
Representing Al Masraf were Fuad Mohamed, Chief Executive Officer; Moataz Khalil, Chief Wholesale Banking Officer; Safeya Almarzooqi, Chief Credit Officer; Mirel Baila, Acting Chief Operating Officer; Rohit Kumar, Chief Risk Officer; and senior representatives from the Bank’s Wholesale Banking, Credit, Risk, Information Technology, Islamic Banking, Corporate Banking, Project Management and Business Management functions.
Representing Moody’s were Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East; Brendan Gavaghan, Senior Director, Middle East; Raghavendra Katagade, Director, UAE; Blaine Connan, Director, UAE; Ali Abdullah, Director, UAE; and Anand Thirunellai Radhakrishnan, Senior Director, Middle East & Europe.
The agreement underscores Al Masraf’s commitment to continuous innovation and adopting advanced capabilities that strengthen its ability to navigate an evolving risk environment, while supporting the Bank’s broader ambition to deliver sustainable growth and enhanced value to its customers and stakeholders.

Long Stay demand Jumps by 20% at Mileo The Palm – A shift from mere staying to experiential living

Holcim And National Development Consortium Sign Strategic MoU to Advance Integrated, Sustainable Development Across the UAE
Good Hair Days Start At Breakfast: Mary Ruth’s Liquid Multivitamin + Hair Growth, Now on iHerb Middle East


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai