 Have a question? +971 56 404 0503

Financial Features
How Embedded Finance Transforms Supply Chains and Fuels Unprecedented Growth

By Vinay Kapoor, Executive Vice President, Triterras
In the heart of the Middle East, the United Arab Emirates (UAE) is undergoing a profound transformation in its business landscape, propelled by the groundbreaking influence of embedded finance. This innovative financial paradigm is not only reshaping traditional structures but also fundamentally altering the way businesses conduct transactions, manage financial risks and navigate the complex financial landscape.
Vinay Kapoor, Executive Vice President, Triterras
At its core, embedded finance involves integrating financial services seamlessly into non-financial platforms, weaving banking functionalities into everyday activities. This innovation allows businesses to offer financial services as part of their core offerings, creating a seamless and integrated customer experience. As we delve into the transformative era of embedded finance in the UAE, the impact is profound, influencing how businesses interact with, and leverage financial tools to enhance operational efficiency and customer engagement.
The UAE, comprising of seven emirates, has strategically transitioned from being a logistics-centric hub to a comprehensive business nerve centre, strategically catering to Asia, Europe and the Middle East and Africa (MEA). This strategic shift is a result of the UAE’s commitment to economic diversification initiatives, the meticulous implementation of national logistics plans and the widespread adoption of cutting-edge digital technologies.
Embedded finance, with an annual growth rate projected at an impressive 30.1% until 2029 in the UAE, stands as a beacon of this transformative journey. At the forefront of this financial revolution is embedded payments, a phenomenon that seamlessly integrates digital payment options within non-financial platforms. This integration streamlines the payment process, enabling customers to make transactions without leaving the website or app. Instant payments and digital wallets like Payit have become integral, illustrating how financial transactions are now seamlessly embedded into the daily operations of businesses, enhancing transaction efficiency and elevating customer experiences.
Another dynamic facet of this transformation is embedded insurance, a strategy that involves selling insurance alongside another product or service, typically at the point of sale. The concept of add-on insurance for products or travel, for example, not only enhances customer confidence but also mitigates risks for both consumers and businesses. In the fiercely competitive market of the UAE, this integrated approach serves as a valuable differentiator, fortifying businesses against unforeseen challenges.
Embedded lending services are actively bridging financial gaps within businesses by providing easier access to credit. The rise of Buy Now, Pay Later (BNPL) services, SME financing and co-branded credit cards exemplify this trend. These lending solutions empower businesses to manage their finances more efficiently, fostering growth and innovation. The impressive growth projection of BNPL services at a CAGR of 13.1% during 2023-2028 in Saudi Arabia underlines the transformative impact of embedded lending in the region.
Embedded investing is also making waves, democratizing wealth management services. Businesses can now seamlessly offer investment opportunities integrated into their digital platforms. Non-financial companies, such as the ride-hailing giant Careem, have ventured into investment products, marking a departure from traditional financial institutions and creating a more inclusive approach to wealth creation.
While the prospects of embedded finance are promising, it is crucial to address challenges such as regulatory frameworks, data security concerns and ensuring transparency in financial practices. Navigating these challenges adeptly presents opportunities for businesses operating in the UAE. The integration of embedded finance not only opens new revenue streams and enhances customer loyalty, but also establishes a symbiotic relationship between financial and non-financial entities.
The UAE government has taken bold initiatives to bolster the nation’s financial infrastructure, seamlessly aligning with the rise of embedded finance. For instance, the Central Bank of UAE launched the Financial Infrastructure Transformation Programme, a pivotal initiative to accelerate digital transformation in the financial sector. This program supports digital transactions, fosters innovation and positions the UAE as a hub for financial excellence. Such initiatives foster a climate conducive to greater financial integration, digitalization and sustainability in business operations. As businesses navigate this new era, where financial services seamlessly intertwine with their core operations, the UAE stands at the precipice of a new financial landscape.
One of the noteworthy impacts of embedded finance, is its transformative effect on the supply chain in the UAE. The efficiency gains achieved through streamlined payments, innovative lending solutions and enhanced financial management directly contribute to a more interconnected, efficient and resilient supply chain ecosystem.
In the context of the supply chain, embedded payments play a pivotal role. The seamless integration of digital payment options reduces friction in transactions, expediting the entire procurement process.
Suppliers and manufacturers can now receive instant payments, improving cash flow and reducing the need for complex invoicing procedures. This not only accelerates the pace of transactions, but also minimizes delays and uncertainties in the supply chain.
Furthermore, embedded lending solutions such as BNPL services and SME financing, inject liquidity into the supply chain. Businesses can access credit more easily, allowing them to optimize inventory levels, meet sudden demand surges and navigate through seasonal fluctuations. This financial flexibility enhances the resilience of the supply chain, ensuring a continuous and smooth flow of goods and services.
Embedded insurance contributes to risk mitigation within the supply chain. The ability to purchase insurance at the point of sale provides businesses with an additional layer of protection against unforeseen disruptions. Whether it is insuring shipments against damages or protecting against financial losses due to unforeseen events, embedded insurance fosters a more secure and reliable supply chain environment.
Moreover, embedded finance facilitates strategic partnerships within the supply chain. Businesses can collaborate more seamlessly, leveraging shared financial platforms and services. This not only streamlines payment processes between partners, but also fosters trust and transparency in financial transactions. Collaborative financial tools, such as co-branded credit cards, enable businesses to jointly invest in initiatives that enhance the efficiency and sustainability of the supply chain.
The versatility of embedded finance is evident in its application across various non-financial customer journeys, including ride-hailing, food delivery and in-store retail experiences. This versatility enables businesses to adapt to changing consumer preferences and market trends, ensuring a more dynamic and responsive supply chain.
Buy Now, Pay Later (BNPL) services emerge as a poster child within the embedded finance ecosystem, particularly in the supply chain. Despite regulatory scrutiny, the growth of BNPL payments in Saudi Arabia exemplifies the widespread adoption of this innovative financial tool. In the context of the supply chain, BNPL services empower businesses to manage cash flows efficiently, providing them with the flexibility to make payments based on the actual revenue generated from the delivered goods.
The transformative impact of embedded finance on the UAE’s business dynamics extends beyond financial services; it is redefining the very fabric of the supply chain. As businesses embrace this financial evolution, the UAE is poised to usher in an era where collaboration between financial and non-financial entities propels unprecedented economic growth and innovation. Embedded finance, with its seamless integration into supply chain operations, is revolutionizing the way transactions occur, creating a more interconnected, efficient, and resilient ecosystem that will define the future of commerce in the UAE.
By Gopal Agarwal, Director, Ryan, Saudi Arabia
When “It’s All Within the Family” Is No Longer Enough
When the Zakat, Tax and Customs Authority (“ZATCA”) amended the Kingdom’s Transfer Pricing By-Laws in 2023, the change was largely viewed as a technical expansion of the existing framework. Transfer pricing obligations, which had historically applied to income taxpayers and mixed-ownership entities, were extended to Zakat payers for financial years beginning on or after 1 January 2024.
Since then, the broader significance of that change is becoming clearer.
The amendment brought transfer pricing into the world of Saudi-owned corporate groups, including some of the Kingdom’s largest and most established family businesses. Many of these groups have no foreign parent, no offshore intellectual property and no cross-border royalty arrangements. Their businesses may be entirely Saudi in ownership and operations. For many, transfer pricing had therefore been viewed as a concern primarily for multinational groups managing transactions across borders.
That assumption no longer holds. For many family-owned groups, including wholly Saudi-owned groups with no foreign parent or cross-border transactions, transfer pricing is now firmly within the compliance landscape.
The critical point is that transfer pricing does not depend on a transaction crossing a border. The Saudi Transfer Pricing By-Laws apply to controlled transactions between related parties or persons under common control. A transaction between two Saudi companies owned by the same family can thereby fall within the transfer pricing framework, even where there is no international element.
The Border Is No Longer the Boundary
This is particularly relevant for family offices because their structures naturally contain a network of related entities – holding companies, operating businesses, real estate vehicles, investment entities and the family office itself. As these structures have evolved, so have the arrangements between them.
A family group may have intercompany loans provided without interest, management services charged at a nominal or flat fee, properties leased at historic rates, guarantees provided without consideration and shared employees whose costs are never formally allocated. These arrangements may have made perfect commercial sense when viewed as decisions within a single family-owned economic unit.
The transfer pricing regime asks a different question: would independent parties have agreed to the same arrangements on the same terms, and can the group demonstrate why?
The challenge for family offices is hence often not a lack of commercial rationale. It is that the rationale has historically existed in people’s understanding rather than in agreements, policies, benchmarking or contemporaneous documentation.
The Transactions Hiding in Plain Sight
For many family groups, the hardest question is surprisingly basic: what related-party transactions do we have?
Family businesses often operate through multiple entities, finance teams and accounting systems. Some arrangements are documented formally; others exist through journal entries, emails or simply an established way of working. Shared employees, IT, procurement, finance and management support may never have been separately identified as intercompany transactions.
Transaction mapping is consequently an important starting point. The objective is not simply to identify intercompany invoices, but to understand how funding, services, people, assets, intellectual property and economic benefits move across the group.
This becomes particularly important during succession, restructuring or consolidation. What appears internally to be a straightforward family restructuring may require a different assessment from a transfer pricing perspective.
Disclosure Today, Documentation Tomorrow
Two documents sit at the heart of the documentation requirement. The Master File describes the family group as a whole, its ownership and organizational structure, main business activities, intercompany financing arrangements and overall transfer pricing policies. The Local File focuses on the Saudi entity itself. It sets out each related-party transaction, who performs which functions, owns which assets and bears which risks, and includes a benchmarking analysis showing that the pricing is consistent with what independent parties would have agreed. Together, the two files allow ZATCA to understand both the group and the individual transaction, and to test whether the pricing can be supported.
For Zakat payers with related-party transactions, the Controlled Transaction Disclosure Form (“CTDF”) is required with the annual return within 120 days of year-end, together with the required auditor’s affidavit[1]. This disclosure requirement is broader than the thresholds determining whether Local File and Master File documentation is required. So, a transaction falling below the documentation threshold does not necessarily fall outside the disclosure framework.
The documentation requirements are phased in. For financial years 2024 to 2026, a group with related-party transactions of up to Saudi riyal (SAR) 48 million is not required to prepare Local File and Master File documentation, preparation is optional for transactions between SAR 48 million and SAR 100 million, and it is required for transactions of SAR 100 million or more. From 2027, documentation becomes mandatory for transactions above SAR 48 million.
The significance of 2027 is therefore clear: the transition period is narrowing.
Once requested by ZATCA, Local and Master Files generally need to be produced within 30 days. For a group that has already mapped its transactions and established its transfer pricing policies, this may be manageable. For one beginning the exercise only after receiving a request, 30 days can be a very short period in which to reconstruct agreements, obtain financial information and undertake benchmarking.
The sensible approach is to use the transition period proactively – understand the group’s related-party transactions, identify potential gaps and formalize arrangements before the requirements become more demanding.
In this context, transfer pricing discipline can become a broader governance signal. A group that can clearly explain who performs a function, who owns an asset, who bears the risk, who receives the benefit and why an intercompany charge exists demonstrates a level of institutional maturity that extends beyond tax compliance.
The Question Family Offices Should Be Asking Now
For Saudi family businesses, transfer pricing represents a shift from viewing related-party arrangements primarily through the lens of common ownership to considering them through the lens of economic substance and commercial rationale.
The objective is not to formalise every family-business decision or impose complexity where none is warranted. Rather, it is to ensure that transactions between related entities have a clear commercial basis, are appropriately priced where required, and can be supported by evidence that reflects how the business actually operates.
As 2027 approaches, the transition period should be viewed not merely as time before a compliance deadline, but as an opportunity to strengthen the governance of the family enterprise.
The real test is not whether a family group has related-party transactions. It is whether the group understands them, has a defensible basis for them, and can demonstrate that basis when required.
Disclaimer: This article is intended for general information only and does not constitute tax, legal, accounting or other professional advice. It reflects the tax rules in force as of the publication date, and the described regulatory landscape continues to develop. Readers should obtain professional advice appropriate to their own facts and circumstances before acting on any matter discussed.
With Dubai fast-tracking agentic AI and AI use among DIFC financial firms rising sharply, Samir Akel, Regional Vice President, Emerging Markets at Nintex, sets out how orchestration turns agentic AI into results for UAE banks and insurers.
This week, much of the region’s technology community has gathered in Abu Dhabi for AI Everything, and the question on the show floor has moved on. A year ago, banks and insurers asked whether to deploy AI agents; today they want to know how to make those agents deliver results across an entire customer journey.
Government is setting the pace. On 5 October, the Dubai Future Foundation launched an agentic AI accelerator covering 33 government entities and more than 300 public-facing use cases, building on the federal target to run half of government services and operations on agentic AI within two years. Few countries have put a number and a deadline on agentic AI. The UAE has done both.
Finance is keeping up. The Dubai Financial Services Authority’s survey of 661 DIFC firms found that 52% now use AI, up from 33% a year earlier, while generative AI use rose by 166%; the regulator also noted that, for many firms, adoption is still at an early stage. UAE finance has AI in many places. The value comes when those pieces work together.
Work in financial services is fragmented
Follow a corporate account opening at a typical UAE bank. The application lands in a portal or a relationship manager’s inbox; documents and identity are checked, sanctions screening runs in a separate tool, a risk team reviews the file, a committee signs it off and operations sets up the account in core banking. That’s six steps, six systems and one waiting customer.
AI agents speed up individual steps: an agent can extract a trade licence in seconds or draft a risk summary in minutes. Then the file sits in a queue for a reviewer who has no idea it is ready. The task gets faster, while the journey stays as slow as its slowest handoff.
That gap is the coordination tax, made up of the hours lost chasing approvals, re-keying data and fielding “where is my application?” calls. In banking, insurance and payments, where one journey can cross half a dozen teams, it is often the largest cost nobody actually measures.
Process is the foundation
Institutions that turn AI into outcomes start by understanding how work actually runs, and regulated firms have a head start here because they already document their processes for supervisors. The task is to map those processes as they really operate (workarounds and exceptions included) and give each step to the right worker.
Steps that must run identically every time, such as sanctions checks and payment releases, suit rules-based workflow. Reading documents and reasoning over unusual cases suit AI agents. Judgement belongs to people. With the Central Bank’s AI guidance for the sector placing clear emphasis on human oversight, deciding where people sit in a process is now part of designing it.
Orchestration makes AI operational
Once the process is clear, orchestration connects it. It coordinates people, systems, data and agents across a whole journey, deciding who or what acts next and routing exceptions to the right person before they become delays.
Think of an airport, where more aircraft add capacity only when air traffic control sequences them. AI agents work in the same way.
For a bank or insurer, orchestration brings one view of every application, claim or payment. Core banking and policy platforms keep their role while work flows between them, and each orchestrated journey becomes a template for the next, so the tenth deployment goes live faster than the first.
A 90-day starting point
Finance can borrow the government’s 90-day rhythm. Pick one journey that crosses at least three systems and two departments, such as SME lending or a motor claim, and map it as it runs today. Count the handoffs and measure the time lost between them; that figure is your coordination tax. Then assign each step to a rule, an agent or a person, orchestrate the whole journey and track time to decision. Reuse what works.
The orchestrators will lead
At the accelerator launch, Digital Dubai’s Director General said the future of digital government depends on an integrated ecosystem that brings expertise, data and capabilities together. The same holds inside every bank.
Over the next year, the number of AI agent use cases across UAE banking and government will grow rapidly. The institutions that pull ahead will be those with a platform to orchestrate and govern those agents, taking them from pilot to production at scale, while keeping people in control. In the AI era, operational advantage belongs to the orchestrators.
By Arash Jalali | Venture Builder | Revona
Most people hear the word “debt” and think of stress, bankruptcy and sleepless nights. It is the villain of personal-finance books and the scapegoat of every economic crisis. But after years of building ventures and, at Revona, structuring financing for developers and corporates every day, I have come to see debt very differently.
Debt is not merely a burden to be minimised. It is one of the most elegant, powerful and, yes, contradictory ideas humanity has ever invented.
That distinction matters especially now. Higher rates have made the cost of debt more visible, while a wall of maturities is turning yesterday’s cheap money into tomorrow’s refinancing decision. The response should not be to romanticise leverage. It should be to become more exacting about the work debt is asked to do.
Debt Is Older Than Money Itself
Long before coins and banknotes, communities ran on credit: promises recorded on clay tablets and in shared memory. Debt is, at its core, a technology for moving value through time. It lets tomorrow’s income fund today’s ambition. When a developer borrows to build a tower, or a founder raises venture debt to extend runway, they are pulling the future forward. That is not recklessness; it is one mechanism through which economies compound.
But the debt debate often starts in the wrong place. There is no magic ratio at which prudent borrowing becomes recklessness. A debt ratio is a snapshot; the real story is what the money is financing, whether cash flow can carry it and whether the borrower has time to adapt when conditions change. That is why the quality of the investment, the maturity profile and the resilience of the balance sheet matter more than the headline number alone.
In the architecture of the modern economy, debt does something even more subtle. It reduces the cost of financial oversight, helps create money through the banking system and smooths the path of economic growth. Every mortgage, every credit facility and every bond issue is a small act of coordinated trust between strangers. Trust, priced and packaged, is what capital markets actually trade.
The Debt That Never Dies
The numbers tell a more precise story than the usual rhetoric. Global debt reached a record nearly $353 trillion by the end of March 2026, according to the Institute of International Finance. That figure covers public, corporate and household debt. At the same time, the global debt-to-GDP ratio stood at about 305%, broadly stable since 2023. A record stock of debt, in other words, does not by itself tell us whether borrowers can carry it; the relationship between liabilities, income, assets and refinancing capacity does.
Nor should a stable global aggregate be mistaken for an all-clear. The IIF reported that debt in mature markets edged lower in the first quarter, while debt in emerging markets excluding China rose to a record $36.8 trillion. Debt is never one homogeneous thing. Its burden depends on who owes it, in what currency, at what rate, for how long, and against which cash flows.
The immediate market test is refinancing. The OECD expects governments and companies to borrow $29 trillion from bond markets in 2026 — 17% more than in 2024 and roughly double the amount ten years ago. Much of that activity is not fresh expansion; it is the constant work of renewing obligations. The OECD estimates that 78% of OECD government borrowing in 2026 will refinance existing debt. That is why the calendar can matter as much as the headline debt total.
The U.S. Lesson: Borrowing Can Stabilise Growth
The United States makes the point in unusually stark terms. The Office of Management and Budget’s fiscal-year-end measure of federal debt held by the public — the debt outside federal government accounts — rose from 25.2% of GDP in FY1981 to 99.5% in FY2025.
That is a profound change, but it was not a straight line and it cannot be explained by one White House. The ratio fell from 46.8% in FY1992 to 33.7% in FY2000, then rose through the financial crisis and jumped during the pandemic. The chart shows presidential terms as chronology, not as a scorecard: a fiscal year spans two calendar years, and debt reflects Congress, inherited commitments, recessions, interest costs and emergencies as well as executive choices.
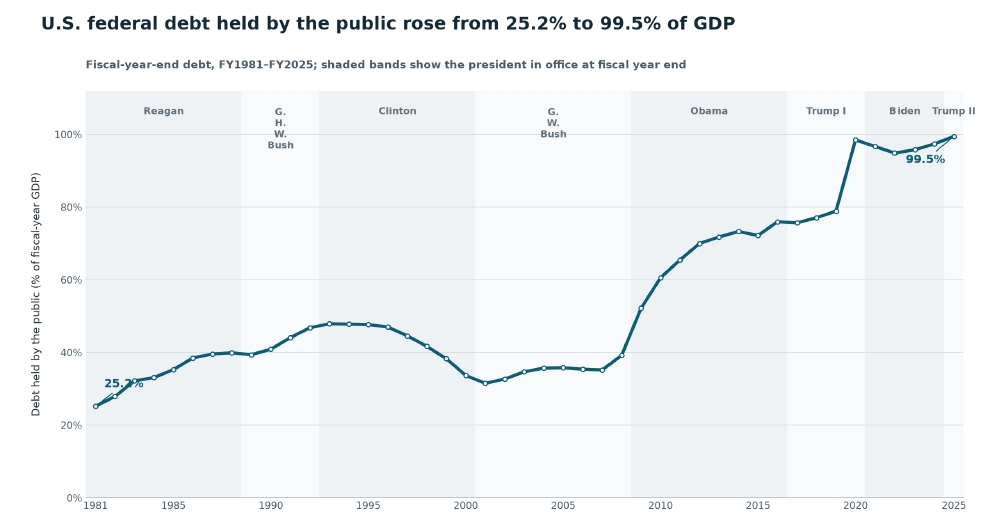
Figure 1. U.S. federal debt held by the public as a share of fiscal-year GDP. Source: Office of Management and Budget, Historical Tables, Table 7.1 (FY2027 release). Debt is measured at fiscal-year end. Administration bands identify the president in office on that date; they do not attribute causation.
The more useful lesson is not that a larger debt stock automatically produces prosperity. It is that, when private demand collapses, borrowing can prevent a deeper contraction. The Congressional Budget Office estimated that the major pandemic laws enacted in 2020 increased real GDP by 4.7% in 2020 and 3.1% in 2021, relative to an implied no-legislation baseline.
That is a concrete example of debt financing acting as a bridge: preserving household income, business liquidity and state and local services at a moment when the alternative was a sharper fall in economic activity.
But bridges must lead somewhere. CBO also projected that the additional debt would raise borrowing costs and reduce output and national income over the longer term. The point is not to celebrate the size of the U.S. debt pile. It is to recognise that borrowing can be a positive driver of growth when it is targeted at a productive investment or a defined emergency — and that its value erodes when cash flows, repayment capacity and the economic return are treated as afterthoughts.
The Beautiful Contradiction
Debt is a paradox, and that is precisely what makes it beautiful. It is simultaneously:
| Debt as… | For whom |
|---|---|
| An asset | The lender, bondholder or pension fund earning a contractual return. |
| A liability | The borrower who must service and ultimately repay it. |
| An engine of growth | The developer, founder or economy that applies it to a productive opportunity. |
| A source of crisis | Anyone who mistakes leverage for a substitute for fundamentals. |
The same instrument that funds a hospital can sink a household. The same leverage that lets a developer sell units before completion can, if mispriced, freeze an entire market. Debt does not care about intentions; it amplifies what is already there. Good projects can become great. Weak projects can fail faster. That amplification is the whole point.
The Revona Angle: Debt as Craft, Not Gamble
This is exactly where Revona operates, and why I find this space so compelling as a builder. If debt is a powerful but indifferent amplifier, the real value lies not in whether a client borrows, but in how the debt is engineered: the rate, the loan-to-value, the tenor, the covenants and the match between an asset’s cash flows and the facility that finances it.
Those are not cosmetic details. A lower headline rate can be a poor bargain if it comes with a refinancing date that arrives before the asset can reliably generate cash. A high loan-to-value ratio may look efficient until a change in valuations removes the borrower’s room for error. A fixed rate can buy time, but it does not eliminate the economics of refinancing.
That final distinction is becoming more important. The Federal Reserve reported in 2025 that long-term, fixed-rate liabilities had softened the initial pass-through of higher rates for large public companies. Yet about 15% of investment-grade bonds and 27% of high-yield bonds were due to mature within one to three years. The protection was real; it was also time-limited.
The OECD has similarly warned that, as higher long-term rates lead borrowers to issue at shorter maturities, near-term interest costs may fall while near-term refinancing risk rises.
At Revona, we treat financing as a craft. We map a client’s full balance sheet, identify untapped equity and structural inefficiencies, and match their profile against the lending criteria of more than sixty banks and institutions to find the optimal structure, not simply the fastest “yes.”
For developers, well-structured off-plan financing can mean buyers are pre-approved during construction, sales accelerate and project cash flow improves. Debt, structured properly, stops being merely a cost of doing business and becomes a competitive advantage.
The failures we associate with debt — the crashes, defaults and horror stories — are more often failures of structure and underwriting than evidence that debt is inherently flawed. They arise when there is too much leverage against too little cash flow; when short-term money funds long-term assets; when currency, revenue and debt-service obligations do not match; or when no one has stress-tested the downside.
The instrument gets blamed for the craftsmanship.
The Takeaway
Debt is usually framed as financial pressure and bankruptcy risk, but its role in the modern economy runs far deeper. It is a centuries-old technology for turning trust into growth, a nearly $353 trillion river of contractual claims, and a mirror that reflects the discipline — or indiscipline — of whoever wields it.
The world’s most sophisticated companies and governments do not avoid debt. They engineer it. As builders and investors, that should be our posture too: respect the contradiction, master the structure and let leverage do what it was invented to do — move the future forward.
AJ is a venture builder. Revona is a financing partner and portfolio manager providing institutional-grade credit and debt financing solutions for developers and corporates.

Qatar Airways Unveils Onboard Signature Music Created in Partnership with Award-Winning Composer Hans Zimmer

Laura Hammett Expands to the Middle East with New Studio in Dubai
RAF ABU DHABI ADDS STARZPLAY AS DISTRIBUTION PARTNER ACROSS MENA


-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai