 Have a question? +971 56 404 0503

Financial Features
How Embedded Finance Transforms Supply Chains and Fuels Unprecedented Growth

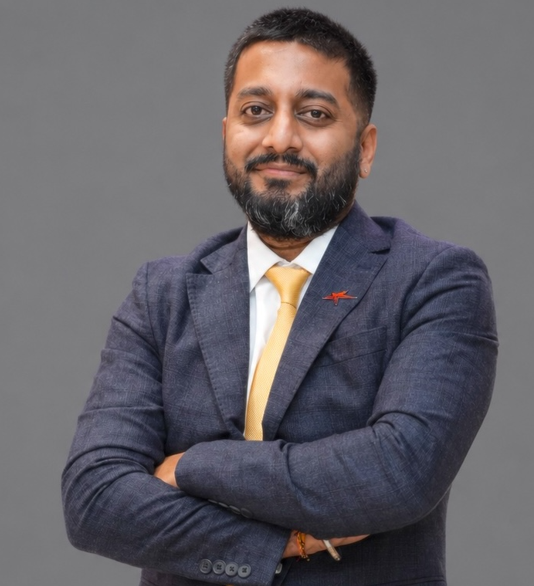
By Vinay Kapoor, Executive Vice President, Triterras
In the heart of the Middle East, the United Arab Emirates (UAE) is undergoing a profound transformation in its business landscape, propelled by the groundbreaking influence of embedded finance. This innovative financial paradigm is not only reshaping traditional structures but also fundamentally altering the way businesses conduct transactions, manage financial risks and navigate the complex financial landscape.
Vinay Kapoor, Executive Vice President, Triterras
At its core, embedded finance involves integrating financial services seamlessly into non-financial platforms, weaving banking functionalities into everyday activities. This innovation allows businesses to offer financial services as part of their core offerings, creating a seamless and integrated customer experience. As we delve into the transformative era of embedded finance in the UAE, the impact is profound, influencing how businesses interact with, and leverage financial tools to enhance operational efficiency and customer engagement.
The UAE, comprising of seven emirates, has strategically transitioned from being a logistics-centric hub to a comprehensive business nerve centre, strategically catering to Asia, Europe and the Middle East and Africa (MEA). This strategic shift is a result of the UAE’s commitment to economic diversification initiatives, the meticulous implementation of national logistics plans and the widespread adoption of cutting-edge digital technologies.
Embedded finance, with an annual growth rate projected at an impressive 30.1% until 2029 in the UAE, stands as a beacon of this transformative journey. At the forefront of this financial revolution is embedded payments, a phenomenon that seamlessly integrates digital payment options within non-financial platforms. This integration streamlines the payment process, enabling customers to make transactions without leaving the website or app. Instant payments and digital wallets like Payit have become integral, illustrating how financial transactions are now seamlessly embedded into the daily operations of businesses, enhancing transaction efficiency and elevating customer experiences.
Another dynamic facet of this transformation is embedded insurance, a strategy that involves selling insurance alongside another product or service, typically at the point of sale. The concept of add-on insurance for products or travel, for example, not only enhances customer confidence but also mitigates risks for both consumers and businesses. In the fiercely competitive market of the UAE, this integrated approach serves as a valuable differentiator, fortifying businesses against unforeseen challenges.
Embedded lending services are actively bridging financial gaps within businesses by providing easier access to credit. The rise of Buy Now, Pay Later (BNPL) services, SME financing and co-branded credit cards exemplify this trend. These lending solutions empower businesses to manage their finances more efficiently, fostering growth and innovation. The impressive growth projection of BNPL services at a CAGR of 13.1% during 2023-2028 in Saudi Arabia underlines the transformative impact of embedded lending in the region.
Embedded investing is also making waves, democratizing wealth management services. Businesses can now seamlessly offer investment opportunities integrated into their digital platforms. Non-financial companies, such as the ride-hailing giant Careem, have ventured into investment products, marking a departure from traditional financial institutions and creating a more inclusive approach to wealth creation.
While the prospects of embedded finance are promising, it is crucial to address challenges such as regulatory frameworks, data security concerns and ensuring transparency in financial practices. Navigating these challenges adeptly presents opportunities for businesses operating in the UAE. The integration of embedded finance not only opens new revenue streams and enhances customer loyalty, but also establishes a symbiotic relationship between financial and non-financial entities.
The UAE government has taken bold initiatives to bolster the nation’s financial infrastructure, seamlessly aligning with the rise of embedded finance. For instance, the Central Bank of UAE launched the Financial Infrastructure Transformation Programme, a pivotal initiative to accelerate digital transformation in the financial sector. This program supports digital transactions, fosters innovation and positions the UAE as a hub for financial excellence. Such initiatives foster a climate conducive to greater financial integration, digitalization and sustainability in business operations. As businesses navigate this new era, where financial services seamlessly intertwine with their core operations, the UAE stands at the precipice of a new financial landscape.
One of the noteworthy impacts of embedded finance, is its transformative effect on the supply chain in the UAE. The efficiency gains achieved through streamlined payments, innovative lending solutions and enhanced financial management directly contribute to a more interconnected, efficient and resilient supply chain ecosystem.
In the context of the supply chain, embedded payments play a pivotal role. The seamless integration of digital payment options reduces friction in transactions, expediting the entire procurement process.
Suppliers and manufacturers can now receive instant payments, improving cash flow and reducing the need for complex invoicing procedures. This not only accelerates the pace of transactions, but also minimizes delays and uncertainties in the supply chain.
Furthermore, embedded lending solutions such as BNPL services and SME financing, inject liquidity into the supply chain. Businesses can access credit more easily, allowing them to optimize inventory levels, meet sudden demand surges and navigate through seasonal fluctuations. This financial flexibility enhances the resilience of the supply chain, ensuring a continuous and smooth flow of goods and services.
Embedded insurance contributes to risk mitigation within the supply chain. The ability to purchase insurance at the point of sale provides businesses with an additional layer of protection against unforeseen disruptions. Whether it is insuring shipments against damages or protecting against financial losses due to unforeseen events, embedded insurance fosters a more secure and reliable supply chain environment.
Moreover, embedded finance facilitates strategic partnerships within the supply chain. Businesses can collaborate more seamlessly, leveraging shared financial platforms and services. This not only streamlines payment processes between partners, but also fosters trust and transparency in financial transactions. Collaborative financial tools, such as co-branded credit cards, enable businesses to jointly invest in initiatives that enhance the efficiency and sustainability of the supply chain.
The versatility of embedded finance is evident in its application across various non-financial customer journeys, including ride-hailing, food delivery and in-store retail experiences. This versatility enables businesses to adapt to changing consumer preferences and market trends, ensuring a more dynamic and responsive supply chain.
Buy Now, Pay Later (BNPL) services emerge as a poster child within the embedded finance ecosystem, particularly in the supply chain. Despite regulatory scrutiny, the growth of BNPL payments in Saudi Arabia exemplifies the widespread adoption of this innovative financial tool. In the context of the supply chain, BNPL services empower businesses to manage cash flows efficiently, providing them with the flexibility to make payments based on the actual revenue generated from the delivered goods.
The transformative impact of embedded finance on the UAE’s business dynamics extends beyond financial services; it is redefining the very fabric of the supply chain. As businesses embrace this financial evolution, the UAE is poised to usher in an era where collaboration between financial and non-financial entities propels unprecedented economic growth and innovation. Embedded finance, with its seamless integration into supply chain operations, is revolutionizing the way transactions occur, creating a more interconnected, efficient, and resilient ecosystem that will define the future of commerce in the UAE.
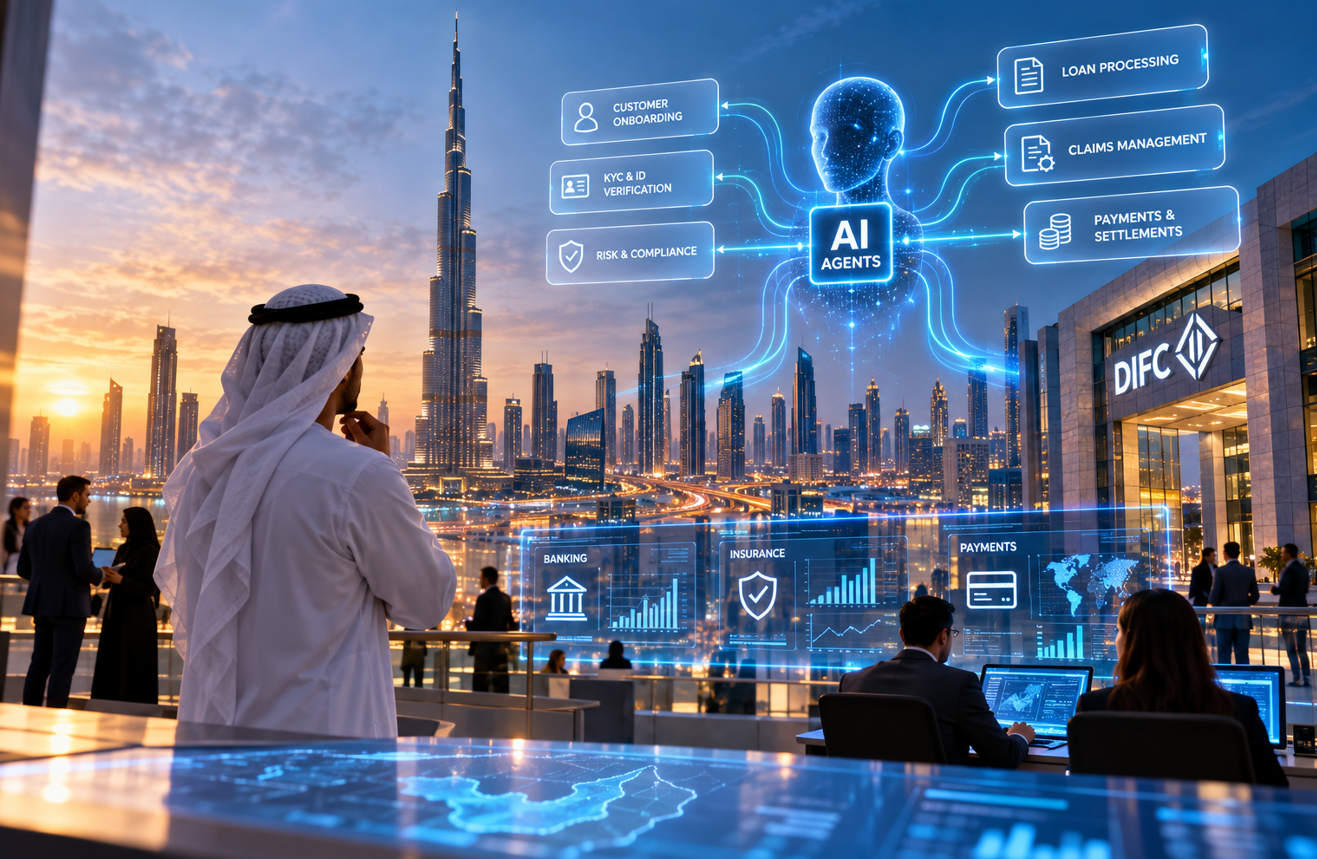
With Dubai fast-tracking agentic AI and AI use among DIFC financial firms rising sharply, Samir Akel, Regional Vice President, Emerging Markets at Nintex, sets out how orchestration turns agentic AI into results for UAE banks and insurers.
This week, much of the region’s technology community has gathered in Abu Dhabi for AI Everything, and the question on the show floor has moved on. A year ago, banks and insurers asked whether to deploy AI agents; today they want to know how to make those agents deliver results across an entire customer journey.
Government is setting the pace. On 5 October, the Dubai Future Foundation launched an agentic AI accelerator covering 33 government entities and more than 300 public-facing use cases, building on the federal target to run half of government services and operations on agentic AI within two years. Few countries have put a number and a deadline on agentic AI. The UAE has done both.
Finance is keeping up. The Dubai Financial Services Authority’s survey of 661 DIFC firms found that 52% now use AI, up from 33% a year earlier, while generative AI use rose by 166%; the regulator also noted that, for many firms, adoption is still at an early stage. UAE finance has AI in many places. The value comes when those pieces work together.
Work in financial services is fragmented
Follow a corporate account opening at a typical UAE bank. The application lands in a portal or a relationship manager’s inbox; documents and identity are checked, sanctions screening runs in a separate tool, a risk team reviews the file, a committee signs it off and operations sets up the account in core banking. That’s six steps, six systems and one waiting customer.
AI agents speed up individual steps: an agent can extract a trade licence in seconds or draft a risk summary in minutes. Then the file sits in a queue for a reviewer who has no idea it is ready. The task gets faster, while the journey stays as slow as its slowest handoff.
That gap is the coordination tax, made up of the hours lost chasing approvals, re-keying data and fielding “where is my application?” calls. In banking, insurance and payments, where one journey can cross half a dozen teams, it is often the largest cost nobody actually measures.
Process is the foundation
Institutions that turn AI into outcomes start by understanding how work actually runs, and regulated firms have a head start here because they already document their processes for supervisors. The task is to map those processes as they really operate (workarounds and exceptions included) and give each step to the right worker.
Steps that must run identically every time, such as sanctions checks and payment releases, suit rules-based workflow. Reading documents and reasoning over unusual cases suit AI agents. Judgement belongs to people. With the Central Bank’s AI guidance for the sector placing clear emphasis on human oversight, deciding where people sit in a process is now part of designing it.
Orchestration makes AI operational
Once the process is clear, orchestration connects it. It coordinates people, systems, data and agents across a whole journey, deciding who or what acts next and routing exceptions to the right person before they become delays.
Think of an airport, where more aircraft add capacity only when air traffic control sequences them. AI agents work in the same way.
For a bank or insurer, orchestration brings one view of every application, claim or payment. Core banking and policy platforms keep their role while work flows between them, and each orchestrated journey becomes a template for the next, so the tenth deployment goes live faster than the first.
A 90-day starting point
Finance can borrow the government’s 90-day rhythm. Pick one journey that crosses at least three systems and two departments, such as SME lending or a motor claim, and map it as it runs today. Count the handoffs and measure the time lost between them; that figure is your coordination tax. Then assign each step to a rule, an agent or a person, orchestrate the whole journey and track time to decision. Reuse what works.
The orchestrators will lead
At the accelerator launch, Digital Dubai’s Director General said the future of digital government depends on an integrated ecosystem that brings expertise, data and capabilities together. The same holds inside every bank.
Over the next year, the number of AI agent use cases across UAE banking and government will grow rapidly. The institutions that pull ahead will be those with a platform to orchestrate and govern those agents, taking them from pilot to production at scale, while keeping people in control. In the AI era, operational advantage belongs to the orchestrators.
By Arash Jalali | Venture Builder | Revona
Most people hear the word “debt” and think of stress, bankruptcy and sleepless nights. It is the villain of personal-finance books and the scapegoat of every economic crisis. But after years of building ventures and, at Revona, structuring financing for developers and corporates every day, I have come to see debt very differently.
Debt is not merely a burden to be minimised. It is one of the most elegant, powerful and, yes, contradictory ideas humanity has ever invented.
That distinction matters especially now. Higher rates have made the cost of debt more visible, while a wall of maturities is turning yesterday’s cheap money into tomorrow’s refinancing decision. The response should not be to romanticise leverage. It should be to become more exacting about the work debt is asked to do.
Debt Is Older Than Money Itself
Long before coins and banknotes, communities ran on credit: promises recorded on clay tablets and in shared memory. Debt is, at its core, a technology for moving value through time. It lets tomorrow’s income fund today’s ambition. When a developer borrows to build a tower, or a founder raises venture debt to extend runway, they are pulling the future forward. That is not recklessness; it is one mechanism through which economies compound.
But the debt debate often starts in the wrong place. There is no magic ratio at which prudent borrowing becomes recklessness. A debt ratio is a snapshot; the real story is what the money is financing, whether cash flow can carry it and whether the borrower has time to adapt when conditions change. That is why the quality of the investment, the maturity profile and the resilience of the balance sheet matter more than the headline number alone.
In the architecture of the modern economy, debt does something even more subtle. It reduces the cost of financial oversight, helps create money through the banking system and smooths the path of economic growth. Every mortgage, every credit facility and every bond issue is a small act of coordinated trust between strangers. Trust, priced and packaged, is what capital markets actually trade.
The Debt That Never Dies
The numbers tell a more precise story than the usual rhetoric. Global debt reached a record nearly $353 trillion by the end of March 2026, according to the Institute of International Finance. That figure covers public, corporate and household debt. At the same time, the global debt-to-GDP ratio stood at about 305%, broadly stable since 2023. A record stock of debt, in other words, does not by itself tell us whether borrowers can carry it; the relationship between liabilities, income, assets and refinancing capacity does.
Nor should a stable global aggregate be mistaken for an all-clear. The IIF reported that debt in mature markets edged lower in the first quarter, while debt in emerging markets excluding China rose to a record $36.8 trillion. Debt is never one homogeneous thing. Its burden depends on who owes it, in what currency, at what rate, for how long, and against which cash flows.
The immediate market test is refinancing. The OECD expects governments and companies to borrow $29 trillion from bond markets in 2026 — 17% more than in 2024 and roughly double the amount ten years ago. Much of that activity is not fresh expansion; it is the constant work of renewing obligations. The OECD estimates that 78% of OECD government borrowing in 2026 will refinance existing debt. That is why the calendar can matter as much as the headline debt total.
The U.S. Lesson: Borrowing Can Stabilise Growth
The United States makes the point in unusually stark terms. The Office of Management and Budget’s fiscal-year-end measure of federal debt held by the public — the debt outside federal government accounts — rose from 25.2% of GDP in FY1981 to 99.5% in FY2025.
That is a profound change, but it was not a straight line and it cannot be explained by one White House. The ratio fell from 46.8% in FY1992 to 33.7% in FY2000, then rose through the financial crisis and jumped during the pandemic. The chart shows presidential terms as chronology, not as a scorecard: a fiscal year spans two calendar years, and debt reflects Congress, inherited commitments, recessions, interest costs and emergencies as well as executive choices.
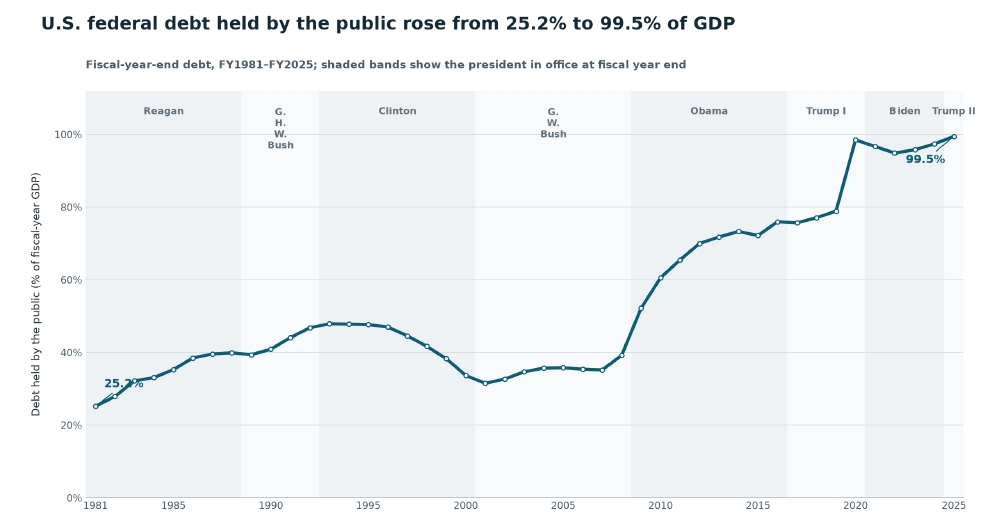
Figure 1. U.S. federal debt held by the public as a share of fiscal-year GDP. Source: Office of Management and Budget, Historical Tables, Table 7.1 (FY2027 release). Debt is measured at fiscal-year end. Administration bands identify the president in office on that date; they do not attribute causation.
The more useful lesson is not that a larger debt stock automatically produces prosperity. It is that, when private demand collapses, borrowing can prevent a deeper contraction. The Congressional Budget Office estimated that the major pandemic laws enacted in 2020 increased real GDP by 4.7% in 2020 and 3.1% in 2021, relative to an implied no-legislation baseline.
That is a concrete example of debt financing acting as a bridge: preserving household income, business liquidity and state and local services at a moment when the alternative was a sharper fall in economic activity.
But bridges must lead somewhere. CBO also projected that the additional debt would raise borrowing costs and reduce output and national income over the longer term. The point is not to celebrate the size of the U.S. debt pile. It is to recognise that borrowing can be a positive driver of growth when it is targeted at a productive investment or a defined emergency — and that its value erodes when cash flows, repayment capacity and the economic return are treated as afterthoughts.
The Beautiful Contradiction
Debt is a paradox, and that is precisely what makes it beautiful. It is simultaneously:
| Debt as… | For whom |
|---|---|
| An asset | The lender, bondholder or pension fund earning a contractual return. |
| A liability | The borrower who must service and ultimately repay it. |
| An engine of growth | The developer, founder or economy that applies it to a productive opportunity. |
| A source of crisis | Anyone who mistakes leverage for a substitute for fundamentals. |
The same instrument that funds a hospital can sink a household. The same leverage that lets a developer sell units before completion can, if mispriced, freeze an entire market. Debt does not care about intentions; it amplifies what is already there. Good projects can become great. Weak projects can fail faster. That amplification is the whole point.
The Revona Angle: Debt as Craft, Not Gamble
This is exactly where Revona operates, and why I find this space so compelling as a builder. If debt is a powerful but indifferent amplifier, the real value lies not in whether a client borrows, but in how the debt is engineered: the rate, the loan-to-value, the tenor, the covenants and the match between an asset’s cash flows and the facility that finances it.
Those are not cosmetic details. A lower headline rate can be a poor bargain if it comes with a refinancing date that arrives before the asset can reliably generate cash. A high loan-to-value ratio may look efficient until a change in valuations removes the borrower’s room for error. A fixed rate can buy time, but it does not eliminate the economics of refinancing.
That final distinction is becoming more important. The Federal Reserve reported in 2025 that long-term, fixed-rate liabilities had softened the initial pass-through of higher rates for large public companies. Yet about 15% of investment-grade bonds and 27% of high-yield bonds were due to mature within one to three years. The protection was real; it was also time-limited.
The OECD has similarly warned that, as higher long-term rates lead borrowers to issue at shorter maturities, near-term interest costs may fall while near-term refinancing risk rises.
At Revona, we treat financing as a craft. We map a client’s full balance sheet, identify untapped equity and structural inefficiencies, and match their profile against the lending criteria of more than sixty banks and institutions to find the optimal structure, not simply the fastest “yes.”
For developers, well-structured off-plan financing can mean buyers are pre-approved during construction, sales accelerate and project cash flow improves. Debt, structured properly, stops being merely a cost of doing business and becomes a competitive advantage.
The failures we associate with debt — the crashes, defaults and horror stories — are more often failures of structure and underwriting than evidence that debt is inherently flawed. They arise when there is too much leverage against too little cash flow; when short-term money funds long-term assets; when currency, revenue and debt-service obligations do not match; or when no one has stress-tested the downside.
The instrument gets blamed for the craftsmanship.
The Takeaway
Debt is usually framed as financial pressure and bankruptcy risk, but its role in the modern economy runs far deeper. It is a centuries-old technology for turning trust into growth, a nearly $353 trillion river of contractual claims, and a mirror that reflects the discipline — or indiscipline — of whoever wields it.
The world’s most sophisticated companies and governments do not avoid debt. They engineer it. As builders and investors, that should be our posture too: respect the contradiction, master the structure and let leverage do what it was invented to do — move the future forward.
AJ is a venture builder. Revona is a financing partner and portfolio manager providing institutional-grade credit and debt financing solutions for developers and corporates.
What could follow the December deadline is an assessment cycle, not a filing cycle.
By Manish Bansal, Associate Partner, Dhruva Advisors, A Ryan Affiliate, Saudi Arabia
For most of the past five years, inter-alia, one of the major topics of tax conversation in Saudi boardrooms has been e-invoicing. Are we on the Fatoora platform? Which wave are we in? Has the ERP been configured or do we go with a third-party e-invoicing solution? Will we make the deadline?
Those were the right questions for the period we have just left. They are not necessarily the right questions for the period we are entering.
On 29 June 2026, the Zakat, Tax and Customs Authority (“ZATCA”), acting on a decision of the Minister of Finance, extended the Cancellation of Fines and Exemption of Financial Penalties initiative for a further six months, running from 1 July to 31 December 2026. It covers excise tax, value added tax, real estate transaction tax, withholding tax and corporate income tax. That much has been widely reported.
Less widely noticed is a condition set out in the accompanying guideline. If the Authority extends the initiative again past December, that further extension will not reach returns that fell due after 30 June 2026.
The Authority has not simply granted more time. It has informed the market, in advance, where the relief eventually stops. Whatever is announced in December, the clean-up window for historical positions is being drawn shut. For a tax administration, that is about as clear a statement as one can give.
What the regulator already sees
The reason this matters now, rather than in some indeterminate future, is that the Authority’s information position has changed fundamentally.
Wave 24 of the e-invoicing Integration Phase closed on 30 June 2026. Announced in September 2025, it captured every taxpayer whose VAT-subject revenues exceeded SAR 375,000 in 2022, 2023 or 2024. That figure is not arbitrary: it is the mandatory VAT registration threshold. In effect, the wave brought the entire registered population into scope.
And the direction has not stopped there. On 24 July 2026 – ZATCA published the criteria for Wave 25, halving the threshold to SAR 187,500 of VAT-subject revenue in 2022, 2023, 2024 or 2025, with integration required by 1 February 2027.
Under the Integration Phase, standard business-to-business invoices are cleared by ZATCA before they reach the buyer, and simplified business-to-consumer invoices are reported within twenty-four hours. Invoices must be issued in a prescribed structured format, carrying a cryptographic stamp and a unique identifier.
The Authority is therefore no longer reliant on what appears in a filed return. It holds the underlying transactional record, in structured form, close to real time, across the whole economy.
This is the shift most finance functions have not yet absorbed. For years, the Saudi assessment process began with an information request. In an environment of structured, near-live data, it begins instead with an anomaly the system has already identified. The taxpayer’s first substantive contact with the process is not a request for documents. It is a proposition to be answered.
Key exposure areas to be mindful of
In our experience, the following key areas could be more visible and exposed to assessment risk in the Kingdom once transactional data can be cross matched against declarations.
The first is permanent establishment risk arising from project delivery. Groups routinely deploy technical staff, secondees and subcontracted specialists into Saudi projects while treating the arrangement as an offshore supply. Given that most KSA government portals are inter-linked, careful monitoring of in-Kingdom presence is critical, in particular, employees of non-resident companies undertaking fly-in/fly-out assignments in the Kingdom. It is worth noting that the current tax law has no de minimis threshold for the creation of a permanent establishment. Accordingly, even a single day of presence in the Kingdom could potentially give rise to a permanent establishment, although in practice, the ZATCA may apply a more facts-based approach when assessing whether a permanent establishment exists.
Second is related-party pricing, and here a change that took effect two years ago is still under-appreciated. Following amendments to the Transfer Pricing By-Laws, the transfer pricing provisions apply to zakat payers as well as taxpayers for financial years beginning on or after 1 January 2024, and Advance Pricing Agreements became available to both. For a Saudi family group with decades of intercompany arrangements built for operational convenience rather than for documentation, this is a material change in obligation, and one that many such groups have not yet worked through.
Lastly, needless to state that VAT audits are likely to get much more sophisticated with real time data and the data analytics and AI tools available.
What the amnesty covers, and what it does not
Many companies are counting on this window. It is worth being precise about what it covers.
The initiative covers late registration, late payment and late filing fines, penalties on the amendment or correction of a VAT return, and other financial fines imposed under Article 45 of the VAT Law, including field detection and e-invoicing violations. To benefit, a taxpayer must register where registration is required, submit the outstanding returns, and either pay the amounts due or obtain ZATCA’s approval for an instalment plan.
Two limits deserve emphasis. The initiative does not extend to penalties relating to tax evasion violations. And it operates on fines for returns falling due up to 30 June 2026.
There is also a point that no guideline states because it does not need to. The initiative waives penalties. It does not validate a technical position. A voluntary disclosure that corrects an arithmetic omission is a straightforward matter. A voluntary disclosure that reveals a contestable tax treatment is a different exercise entirely, because it puts a position on the record that will be read. The analysis must come before the filing, not after it.
Fewer than four months
For most groups, what remains to be done before 31 December is a short list. It is also, notably, not a systems exercise. The e-invoicing platforms are already built and connected. The work now is reviewing the positions those systems have been reporting all along.
Reconcile first. Take VAT/ Tax/ Zakat returns, customs declarations, withholding tax filings and audited financial statements for the open years and reconcile them against one another before ZATCA’s systems do it. Where the numbers do not tie, understand why, and document the reason contemporaneously rather than reconstructing it under assessment.
Then sort. Separate the genuine errors, which the current window is designed to resolve, from the judgement positions, which need to be assessed on their merits and defended with evidence that pre-dates the query.
Finally, treat documentation as a deliverable with a deadline. Substantiation assembled after an assessment notice arrives carries markedly less weight than substantiation prepared when the transaction occurred.
A regulator that publishes wave criteria six months ahead, that notifies taxpayers directly, that issues guidance with worked examples, and that tells the market in advance where relief will end, is behaving like the administration of a mature investment destination. That predictability is an asset for serious businesses, and it is what long-term capital looks for.
But predictability runs in both directions. The Kingdom has been clear about what it expects and when. The businesses that will move through the coming assessment cycle with least disruption are those that use the next few months to answer the questions before they are asked.
Disclaimer: This article is intended for general information only and does not constitute tax, legal, accounting or other professional advice. It reflects the tax rules in force as of the publication date, and the described regulatory landscape continues to develop. Readers should obtain professional advice appropriate to their own facts and circumstances before acting on any matter discussed.
Terrace Dining, Oktoberfest, and Beach Days Return to InterContinental Abu Dhabi This October

THE STORIES BEHIND THE MATERIALS SHAPING UAE INTERIORS
Form Room welcomes new JVC residents with a complimentary coffee and exclusive discounts


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai