 Have a question? +971 56 404 0503

Financial
MEX Global’s Cash Payout Service: A Game-Changer for UAE Clients


In an exclusive interview with Naser Taher, Founder and Chairman of MultiBank Group, Financial Integrator delves into the company’s strategic partnership with Al Ansari Exchange, which has launched innovative cash payout services to improve financial accessibility in the UAE. As part of its global expansion, MultiBank Group is leveraging cutting-edge technologies such as AI, blockchain, and digital assets to fuel growth and address the evolving needs of its clients.
What inspired MEX Global to introduce cash payment services in partnership with Al Ansari Exchange, and what core objectives are you aiming to achieve with this service in the UAE market?
At MultiBank Group, we are committed to staying ahead of market trends by innovating and adapting our offerings, ensuring it meets the evolving demands of the financial world. Through our subsidiary, MEX Global, we introduced this innovative cash payout service in partnership with Al Ansari Exchange to provide clients in the UAE with a more seamless, flexible, and accessible way to manage their funds.
By leveraging Al Ansari Exchange’s extensive branch network, we aim to simplify financial transactions, offering our clients the convenience of depositing and withdrawing funds in a secure and efficient manner.
Through strategic alliances with key financial entities like Al Ansari Exchange, MultiBank Group enhances its operational capabilities, drives strategic growth, and reinforces its commitment to delivering excellence in customer satisfaction.
Where is MultiBank Group seeing the biggest growth in its client base? Are there specific sectors or services you’re focusing on for future expansions?
Since its inception in 2005, MultiBank Group has emerged as the world’s largest financial derivatives institution, with a client base of over 1 million in more than 100 countries. Our expansion continues to be on enhancing our service offerings, adopting latest technologies, and strengthening our global presence.
In the future, we are enhancing social trading with advanced features, influencer partnerships, and the MultiBank Academy. Through the MultiBank Chain, we aim to bridge real-world assets with crypto derivatives while advancing AI-powered trading with smart bots and machine learning. We plan to launch the MBG Token, which will facilitate seamless transactions, staking, and decentralized finance, alongside an NFT marketplace for digital assets. Additionally, our future plans include MultiBank INC, a fully digital bank integrated with our trading platforms, and MEX PAY, an electronic payment gateway for retail and institutional clients. These initiatives reflect our commitment to merging traditional finance with cutting-edge technology to serve evolving client needs.
What is MultiBank Group’s perspective or take on the state of the GCC economies?
Relocating to Dubai has brought us closer to global markets, given us a strong regulatory environment, and placed us within a thriving regional financial ecosystem. According to the World Bank, the GCC countries are making significant strides in diversifying their economies, moving beyond traditional oil
dependency. Economic growth in the region is projected to rebound to an impressive 4.7% by 2025, driven by proactive investments in non-oil sectors and a steady recovery in oil production.
This resilience highlights the GCC’s commitment to fostering a sustainable and robust economic future, underscoring its role as a key player in the global economy. At MultiBank Group, we view this transformation as an opportunity to align with the region’s progressive vision and contribute to its continued success through innovative financial services and solutions.
With a daily trading volume exceeding $18.1 billion, what trends do you see shaping the future of financial derivatives trading, particularly in the UAE and the GCC?
MultiBank Group is creating a comprehensive and secure financial ecosystem, ensuring our clients have access to the most advanced, efficient, and user-friendly trading platforms. This forward-thinking approach positions us as leaders in the financial derivatives market, particularly in the UAE and the broader GCC region.
Blockchain and AI are pivotal in shaping the future of financial derivatives trading and are central to MultiBank Group’s strategy. Our new AI division, MultiBank-AI, focuses on integrating AI into our internal processes and client services to boost efficiency and enhance the customer experience. Blockchain adds security and transparency, and we’re pioneering ways for clients to trade cryptocurrencies versus traditional assets combined with a state-of-the-art social copy trading platform, creating new opportunities in finance.
We see the industry moving towards more digital integration, especially in fintech, and we’re committed to growing our digital asset offerings, upgrading our tech infrastructure, and maintaining top-tier compliance and customer service to stay competitive.
Financial
Pay10 Announces Strategic Partnerships at Dubai FinTech Summit 2026, Advancing the UAE’s Digital Payments Ecosystem
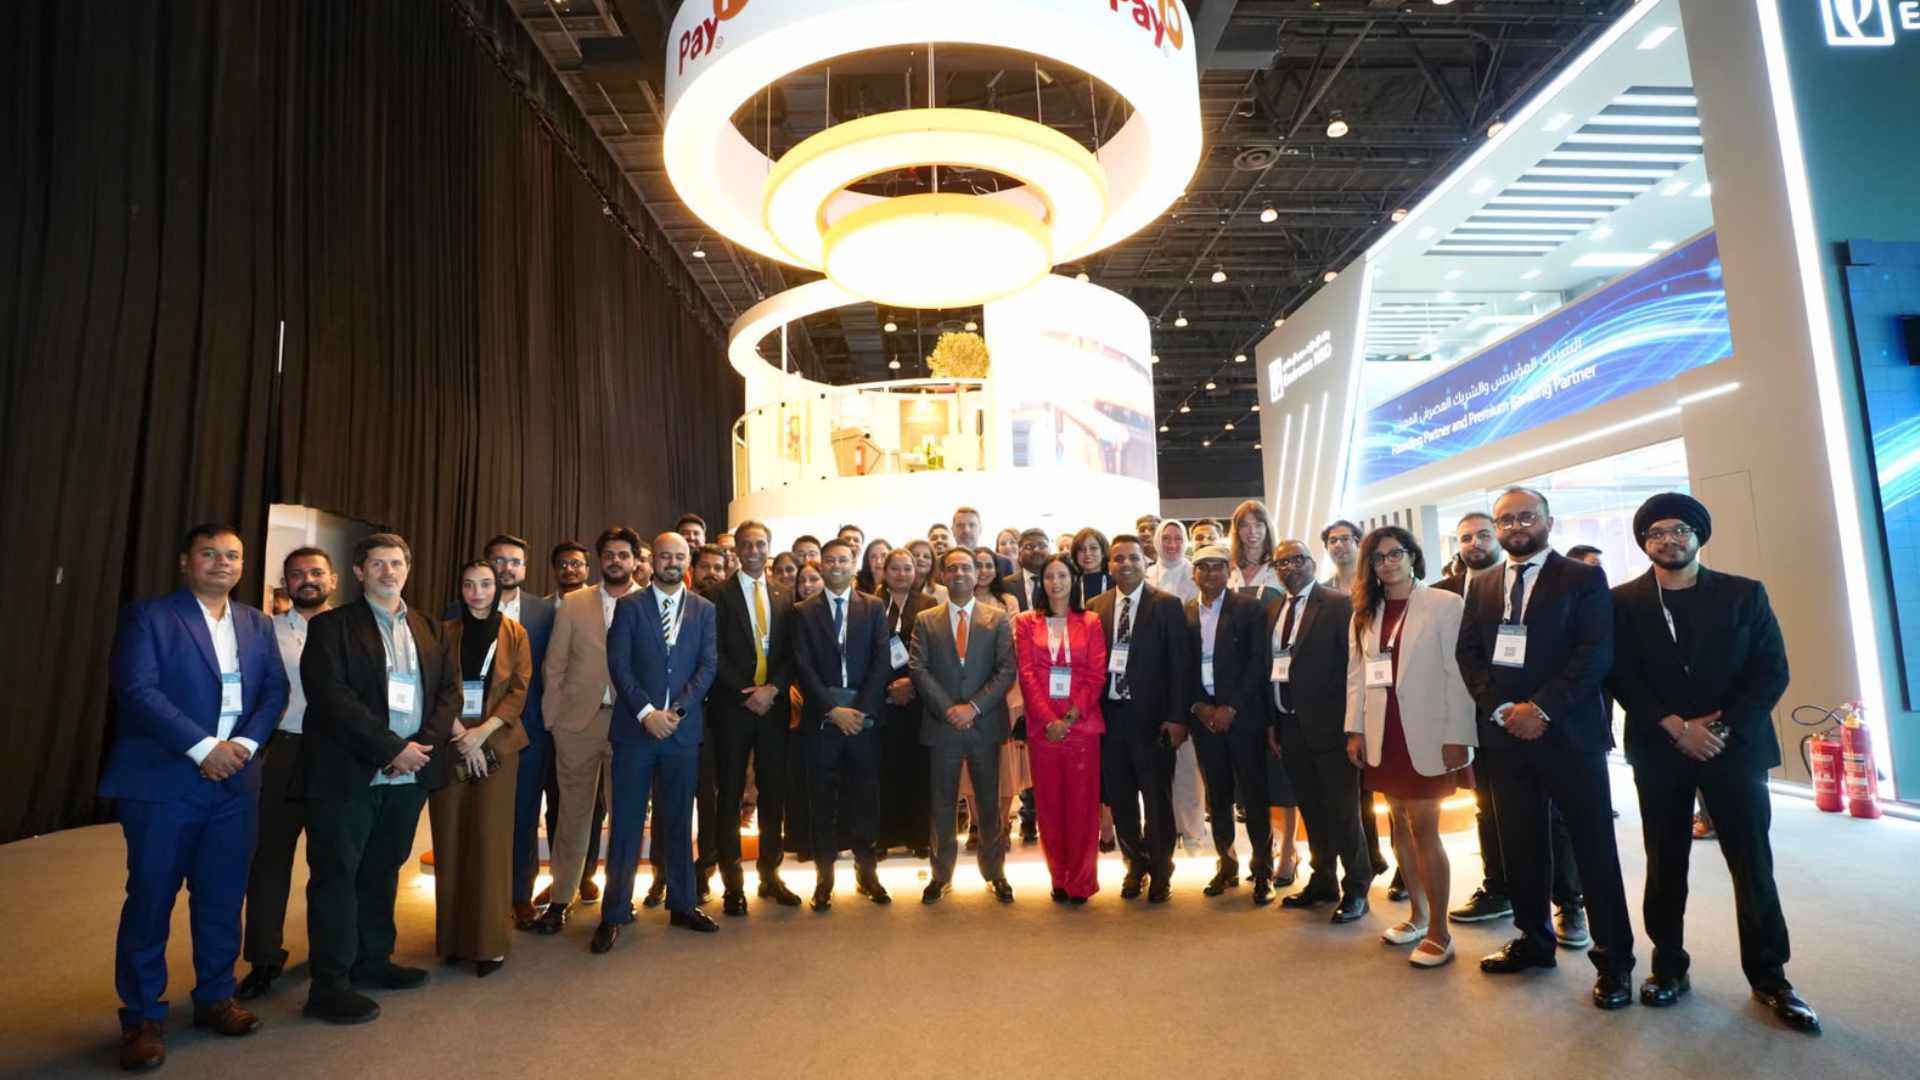
Pay10, a UAE-regulated financial technology company, today announced a series of strategic partnerships, commercial agreements and Memoranda of Understanding (MoUs) at Dubai FinTech Summit 2026. The announcements mark a step towards expanding digital payment choices and supporting the UAE’s transition towards real-time, interoperable and account-based payments, in alignment with the Central Bank of the UAE’s Financial Infrastructure Transformation (FIT) Programme.
Pay10’s partnerships with leading brands, including GEMS, Jumbo Electronics, Bikanervala, Allday, Just Gold and Save In Gold, span education, retail, food and beverage and specialised commerce. With live deployments already in place at GEMS, Bikanervala, Allday and Just Gold, Pay10 is extending its payment ecosystem across everyday consumer and business transactions.
Building a Connected Payments Ecosystem
Pay10 brings together instant payments, Open Finance, digital accounts, domestic card infrastructure and merchant payment acceptance through an integrated platform.
Directly integrated with Aani, Pay10 enables instant payments and supports account-based payment experiences. Its Open Finance capabilities allow consumers to securely connect supported bank accounts, access consolidated financial information and monitor spending through one application. Its Jaywan issuance capabilities also enable eligible wallet customers to access domestic card payments across POS terminals, ATMs and e-commerce channels.
For merchants, the platform offers multiple payment acceptance options, including Pay by Pay10, Pay by Bank, card acceptance, interoperable QR payments, payment links and digital payouts. Its proprietary POS application, QR and soundbox solutions are supported by an in-house Terminal Management System.
Through supported account-based payment methods, merchants can access funds in real time, helping improve cash flow and reduce payment acceptance costs, with potential savings of up to 70% in applicable use cases. Pay10 also reports transaction success rates of over 90% across its integrated technology infrastructure.
Strategic Partnerships and Collaborations
The partnerships with GEMS and Jumbo Electronics aim to expand digital payment choices and improve collection efficiency across education and consumer retail. Existing deployments with GEMS, Bikanervala, Allday and Just Gold demonstrate the application of Pay10’s payment solutions across different commercial environments.
Allday, a leading convenience chain in the region, presents an opportunity to explore the impact of digital payment solutions across high-frequency, small-value transactions.
Pay10 also announced several MoUs to explore emerging financial use cases. Its partnership with Yalla Financial Solutions, part of Fintra Holding, will explore bank-account-based wallet funding through Open Finance.
Additionally, our collaboration with TotalPay will enable TotalPay to access Pay10’s merchant payment acceptance capabilities through its technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
Dr. Waleed Sadek, Founder & CEO of Yalla Financial Solutions, said: “We are pleased to explore this strategic collaboration with Pay10, reflecting our shared vision of building a more connected and accessible financial ecosystem. Through Open Finance and account-based wallet funding, we aim to unlock new opportunities for seamless digital payments and enhance the financial experience for businesses and consumers across the region.”
Supporting the UAE’s Financial Infrastructure
Pay10’s strategy aligns with the Central Bank of the UAE’s FIT Programme through the adoption of domestic payment infrastructure, including Aani, Jaywan and Open Finance. By investing in direct infrastructure connectivity and proprietary technology, the company aims to support greater interoperability, financial inclusion and more efficient payment experiences.
Harry Gill, Founder & Chairman, Pay10, said: “The UAE has laid the foundations for the future of finance, and our goal is to make it accessible to everyone. Pay10 is building a UAE-based alternative payment ecosystem that brings together domestic payment infrastructure, Open Finance, accounts, cards and merchant solutions. Our partnerships with GEMS, Jumbo Electronics, Bikanervala, Allday and Just Gold reflect growing confidence in this vision. We remain committed to advancing the UAE’s financial ambitions through a connected, interoperable ecosystem built to scale globally.”
Our collaboration with TotalPay will enable it to access Pay10’s payment acceptance capabilities for merchants through TotalPay’s technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
With further agreements, product launches and integrations in development, Pay10 aims to expand its consumer and merchant capabilities across the UAE and international markets.
By Gopal Agarwal, Director, Ryan, Saudi Arabia
When “It’s All Within the Family” Is No Longer Enough
When the Zakat, Tax and Customs Authority (“ZATCA”) amended the Kingdom’s Transfer Pricing By-Laws in 2023, the change was largely viewed as a technical expansion of the existing framework. Transfer pricing obligations, which had historically applied to income taxpayers and mixed-ownership entities, were extended to Zakat payers for financial years beginning on or after 1 January 2024.
Since then, the broader significance of that change is becoming clearer.
The amendment brought transfer pricing into the world of Saudi-owned corporate groups, including some of the Kingdom’s largest and most established family businesses. Many of these groups have no foreign parent, no offshore intellectual property and no cross-border royalty arrangements. Their businesses may be entirely Saudi in ownership and operations. For many, transfer pricing had therefore been viewed as a concern primarily for multinational groups managing transactions across borders.
That assumption no longer holds. For many family-owned groups, including wholly Saudi-owned groups with no foreign parent or cross-border transactions, transfer pricing is now firmly within the compliance landscape.
The critical point is that transfer pricing does not depend on a transaction crossing a border. The Saudi Transfer Pricing By-Laws apply to controlled transactions between related parties or persons under common control. A transaction between two Saudi companies owned by the same family can thereby fall within the transfer pricing framework, even where there is no international element.
The Border Is No Longer the Boundary
This is particularly relevant for family offices because their structures naturally contain a network of related entities – holding companies, operating businesses, real estate vehicles, investment entities and the family office itself. As these structures have evolved, so have the arrangements between them.
A family group may have intercompany loans provided without interest, management services charged at a nominal or flat fee, properties leased at historic rates, guarantees provided without consideration and shared employees whose costs are never formally allocated. These arrangements may have made perfect commercial sense when viewed as decisions within a single family-owned economic unit.
The transfer pricing regime asks a different question: would independent parties have agreed to the same arrangements on the same terms, and can the group demonstrate why?
The challenge for family offices is hence often not a lack of commercial rationale. It is that the rationale has historically existed in people’s understanding rather than in agreements, policies, benchmarking or contemporaneous documentation.
The Transactions Hiding in Plain Sight
For many family groups, the hardest question is surprisingly basic: what related-party transactions do we have?
Family businesses often operate through multiple entities, finance teams and accounting systems. Some arrangements are documented formally; others exist through journal entries, emails or simply an established way of working. Shared employees, IT, procurement, finance and management support may never have been separately identified as intercompany transactions.
Transaction mapping is consequently an important starting point. The objective is not simply to identify intercompany invoices, but to understand how funding, services, people, assets, intellectual property and economic benefits move across the group.
This becomes particularly important during succession, restructuring or consolidation. What appears internally to be a straightforward family restructuring may require a different assessment from a transfer pricing perspective.
Disclosure Today, Documentation Tomorrow
Two documents sit at the heart of the documentation requirement. The Master File describes the family group as a whole, its ownership and organizational structure, main business activities, intercompany financing arrangements and overall transfer pricing policies. The Local File focuses on the Saudi entity itself. It sets out each related-party transaction, who performs which functions, owns which assets and bears which risks, and includes a benchmarking analysis showing that the pricing is consistent with what independent parties would have agreed. Together, the two files allow ZATCA to understand both the group and the individual transaction, and to test whether the pricing can be supported.
For Zakat payers with related-party transactions, the Controlled Transaction Disclosure Form (“CTDF”) is required with the annual return within 120 days of year-end, together with the required auditor’s affidavit[1]. This disclosure requirement is broader than the thresholds determining whether Local File and Master File documentation is required. So, a transaction falling below the documentation threshold does not necessarily fall outside the disclosure framework.
The documentation requirements are phased in. For financial years 2024 to 2026, a group with related-party transactions of up to Saudi riyal (SAR) 48 million is not required to prepare Local File and Master File documentation, preparation is optional for transactions between SAR 48 million and SAR 100 million, and it is required for transactions of SAR 100 million or more. From 2027, documentation becomes mandatory for transactions above SAR 48 million.
The significance of 2027 is therefore clear: the transition period is narrowing.
Once requested by ZATCA, Local and Master Files generally need to be produced within 30 days. For a group that has already mapped its transactions and established its transfer pricing policies, this may be manageable. For one beginning the exercise only after receiving a request, 30 days can be a very short period in which to reconstruct agreements, obtain financial information and undertake benchmarking.
The sensible approach is to use the transition period proactively – understand the group’s related-party transactions, identify potential gaps and formalize arrangements before the requirements become more demanding.
In this context, transfer pricing discipline can become a broader governance signal. A group that can clearly explain who performs a function, who owns an asset, who bears the risk, who receives the benefit and why an intercompany charge exists demonstrates a level of institutional maturity that extends beyond tax compliance.
The Question Family Offices Should Be Asking Now
For Saudi family businesses, transfer pricing represents a shift from viewing related-party arrangements primarily through the lens of common ownership to considering them through the lens of economic substance and commercial rationale.
The objective is not to formalise every family-business decision or impose complexity where none is warranted. Rather, it is to ensure that transactions between related entities have a clear commercial basis, are appropriately priced where required, and can be supported by evidence that reflects how the business actually operates.
As 2027 approaches, the transition period should be viewed not merely as time before a compliance deadline, but as an opportunity to strengthen the governance of the family enterprise.
The real test is not whether a family group has related-party transactions. It is whether the group understands them, has a defensible basis for them, and can demonstrate that basis when required.
Disclaimer: This article is intended for general information only and does not constitute tax, legal, accounting or other professional advice. It reflects the tax rules in force as of the publication date, and the described regulatory landscape continues to develop. Readers should obtain professional advice appropriate to their own facts and circumstances before acting on any matter discussed.
Exclusive Interview with Nasir Khan, Co-Founder, Synovo
The MENA startup ecosystem is shifting from growth at all costs to sustainable business models. What has changed, and what does it take to build a financially resilient startup from the outset?
I think the biggest change is that investors have become less willing to finance a business model indefinitely while founders work out the economics. A few years ago, a compelling growth story could carry a lot of weight. Today, people want to know what each additional customer costs, when that customer becomes profitable and how much cash the company needs to get there.
For me, resilience starts with knowing the difference between revenue, profit and cash. Having worked across telecom distribution, factoring and healthcare ventures, I’ve seen businesses look healthy on paper while working capital quietly becomes their biggest problem.
My advice is to start small enough to test your assumptions, know your margins well and build a business that can survive a slow month, not just celebrate a good one.
Raising capital is only one step towards building a successful business. What financial mistakes do startups commonly make after securing investment, and how can they avoid them?
The most common mistake is treating money in the bank as proof that the business has succeeded. Suddenly there is a bigger office, a larger team and three new markets on the roadmap, before the original model has really been proven. Fixed costs rise quickly, and reversing them is much harder.
I prefer to see founders tie each stage of spending to a milestone: demonstrating repeat purchases, shortening the sales cycle, improving gross margin or reaching a defined number of paying customers.
I’d also keep a fallback plan in case the next round takes twice as long as expected. Fundraising buys time, but what matters is what you prove during that time.
Drawing on your experience in structured finance, how should MENA founders choose between equity, debt and other financing options at different stages of growth?
I spent years in factoring and structured finance, and one lesson has stayed with me: match the type of financing to the risk you are financing.
Equity makes sense when the product, market or revenue model is still uncertain, because investors are sharing the risk of finding out whether the business works. Debt is better suited to predictable cash flows or identifiable assets. Once a business has reliable receivables, trade finance or factoring can fund working capital without giving away more ownership.
But debt is not a cure for an unprofitable business. It creates a payment obligation whether the next contract arrives or not. Founders should also watch for currency mismatches and personal guarantees. The cheapest-looking capital is not always the safest.
Access to capital varies across MENA markets. How should founders in emerging startup hubs approach financial planning differently from those in established ecosystems such as the UAE and Saudi Arabia?
First, I would resist treating MENA as a single market. Access to investors is only one difference. Collection cycles, currency exposure, regulation, customer purchasing power and the availability of experienced hires all change from country to country.
In a smaller funding ecosystem, I would plan for a longer fundraising process and keep costs as variable as possible. A local commercial partnership is often more useful early on than opening a fully staffed operation.
Even in the UAE or Saudi Arabia, access to capital does not mean every startup is fundable. Founders still have to show that they understand their own market. Expansion should follow customer evidence, not a regional map in a pitch deck.
Cash flow is critical to a startup’s survival. Which financial metrics should founders monitor, and how can they maintain cash flow discipline while pursuing growth?
I would start with five things: cash in the bank, monthly net burn, runway, gross margin and the time between invoicing a customer and actually collecting the money.
For subscription businesses, retention and customer acquisition cost matter enormously. For businesses selling to corporates or governments, receivables ageing can be just as important as revenue growth.
A simple weekly cash forecast looking 13 weeks ahead can prevent a lot of unpleasant surprises. I also like a monthly downside scenario: what happens if collections are delayed, or sales come in 25% below plan?
These are not glamorous exercises, but I’ve seen how quickly a growing business can run into trouble when sales rise faster than the cash needed to deliver them.
What makes a startup truly investor-ready today, particularly in terms of financial reporting, governance, unit economics and operational discipline?
Investor readiness is not a beautiful data room put together two weeks before a meeting. It is the discipline with which the business has been run over the previous year.
Can the founder explain the margin on a customer? Reconcile revenue to cash received? Show who owns the company, what obligations exist and which assumptions sit behind the forecast? Do they know how much of their revenue depends on a handful of customers?
In healthcare ventures such as Synovo, which I co-founded, financial planning also has to reflect clinical evidence, regulatory requirements and hospital procurement cycles. Ignore those realities and even an attractive forecast becomes meaningless.
Investors understand that early-stage businesses will not have perfect systems. What worries them is when founders cannot explain their numbers or become defensive when challenged. Being candid about risks usually strengthens investor confidence rather than weakening it.
How can MENA founders balance growth with profitability and reduce dependence on repeated funding rounds? When should they rethink their strategy if new investment fails to materialise?
Profitability does not need to arrive on day one, but the route to it should be visible. The test I use is whether growth improves the economics or simply increases the losses. If every new customer makes the funding gap bigger, scale is not solving the problem.
I would review the plan well before the runway becomes critical. If investment is uncertain, narrow the product range, protect the best customers, reduce fixed commitments and concentrate on revenue that turns into cash.
Sometimes a smaller, profitable core is the right foundation for a much larger company. Waiting until the last three months of cash to make those decisions usually leaves very few good options.
Through your involvement with the London Business School MENA Startup Competition, what distinguishes genuinely scalable startups from those with compelling pitches, and what will define the next generation of successful MENA businesses?
The competition reminded me that a polished pitch and a scalable business are two different things. The founders who caught my attention were not necessarily the ones with the grandest projections. They were the ones who could explain what customers had actually done, what they had learned from being wrong and what the next round of capital would achieve.
Our shortlisted teams were mentored by LBS alumni and volunteers, and it was encouraging to see founders willing to challenge their own assumptions rather than defend them.
I think the next generation of strong MENA businesses will combine regional ambition with local execution, sensible capital structures and the ability to earn customer trust.
Winning a competition can open doors. What founders build after the applause is what ultimately counts.
Dr. Nasir Khan is a medical doctor, entrepreneur and Sloan Fellow from London Business School. He has been building businesses since 2001 across telecom distribution, financial services, medtech and process manufacturing, and has co-founded ventures including Synovo, a UK-based digital health platform. He has also served as a judge for startup induction at the Punjab Information Technology Board’s incubation programme in Lahore and is Co-President of the LBS Entrepreneurship Club, MENA.

Pay10 Announces Strategic Partnerships at Dubai FinTech Summit 2026, Advancing the UAE’s Digital Payments Ecosystem

Under the Patronage of the Prime Minister and Minister of Foreign Affairs of the State of Qatar, Qatar Airways Hosts Arab Air Carriers’ Organization’s 59th Annual General Meeting
The Coffee Lab Celebrates Three Years at Aljada with Complimentary Cupcakes and Coffee Vouchers


-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai