 Have a question? +971 56 404 0503

Home Feature
HOW DIRECT ENGAGEMENT WITH BUYERS CAN TRANSFORM REAL ESTATE DEVELOPMENT

Have you ever wondered why real estate commissions never seem to change? In the UAE, agent commissions are typically 2 percent of a property’s price and up to 5 percent of rental value. In many other countries, it’s the same story — commissions are generally fixed, without regard to the quality of the property, its size and value, or even the quality of service.
Is this a fair deal? Opinions may differ, but over the years many experts have often cited this practice as one of the enduring inefficiencies and limitations of the developer–agent–buyer chain. Traditionally, in this model, buyers make decisions largely based on what is presented to them by intermediaries, while developers rely on the same agents to gather market feedback. One party, the intermediary, acts as gatekeepers of the flow of information, and consequently holds more insights than both developers and buyers.
Analysts say this set-up has led to information frictions in the market, a term they use to describe information that is imperfect, costly, or asymmetric. It’s a system prone to distortions, delays, and inefficiencies that ultimately result in mispricing, misaligned offerings, slower feedback, and missed market insights.
But for years things have remained largely unchanged. Amid one of the real estate market’s most dynamic phases, we would be tempted to think otherwise — that the conditions for change have never been stronger. In Dubai, the property market reached a value of AED 761 billion in 2024, shattering records according to the Dubai Land Department. The entire city is buzzing with new projects, including a much-awaited third metro train line. But as they say, developers build quickly yet adapt slowly.
So while we’re seeing skylines transform at breathtaking speed, many business practices, e.g. how properties are marketed, sold, and priced, have largely remained the same. Pricing structures and commission models have been left untouched. Countless studies have exhaustively discussed why this is so, e.g. the real estate and construction industries being historically change-averse. The usual excuses: they’re asset-heavy, heavily regulated, and have a strong reliance on long-standing relationships and legacy processes.
But change is becoming a competitive necessity. While maintaining the status quo preserves certain best practices, the conventional developer–agent–buyer set-up has also entrenched inefficiencies that no longer serve today’s developers or buyers. Breaking the status quo means rethinking how knowledge moves through the property value chain. But who will take the first step?
Direct-to-owner model
Disintermediation, the process of removing middlemen between developers and buyers, is an alternative approach that overcomes many of these inefficiencies. From the outset, this model is seen to greatly benefit real estate consumers as it completely removes the need for agent commissions. But developers and many individual home sellers also stand to gain from engaging directly with homebuyers as it gives them complete control over the sales process and market data – two critical factors for maintaining a competitive edge in a rapidly evolving market.
This is not a totally new concept. Disintermediation was coined in the 1960s when consumers started to invest directly in securities such as stocks, bonds, hedge funds, and mutual funds, instead of depositing their money in banks. Technology was key to unlocking this shift, not just in finance but in other industries such as real estate.
In the age of the internet and artificial intelligence, disintermediation has taken on a far more practical and transformative role, particularly in real estate. The modern buyer’s journey increasingly begins, and many times ends, online, with AI influencing every stage. In fact, the UAE has now achieved 100% internet penetration, according to a report by the Telecommunications and Digital Government Regulatory Authority (TDRA), effectively making online platforms a default starting point for most property seekers.
Meanwhile, there has been a big shift in the homebuyer profile towards a younger, more tech-savvy generation. The average age of homebuyers has significantly dropped from 53-54 in 2017 to 42-44 in 2025. Moreover, 36-45-year-olds now account for up to 40% of off-plan sales and 44% for ready and re-sale transactions. An even younger cohort, the 21-25 age group, is becoming increasingly active in the property market, buying 38.6% and 33.3% more off-plan and ready property, respectively, over the previous year.
This shows a clear shift in who is buying as well as in the potential of data-driven and algorithm-assisted decision-making as younger real estate consumers increasingly turn to online platforms to buy and gather insights. Yet, in the traditional developer–agent–buyer chain, that data, enriched with AI insights on buyer behavior and preferences, is filtered through layers of intermediation before reaching the developer.
Giving back control to those who create value
Direct-to-owner platforms are now changing that dynamic entirely. Instead of relying on agents to interpret the market, developers and sellers can engage directly with their customers, gaining complete visibility and control over their data and customer interactions. They see first-hand how buyers respond to pricing, visuals, and messaging, and can adjust their strategies accordingly in real time. In our experience at Gllit, a direct-to-owner property listing platform, the efficiencies gained from direct customer engagement are significant — giving developers and sellers critical customer insights that allow them to respond faster to trends and design more inclusive, market-aligned projects and strategies.
Disintermediation is ultimately about restoring balance in the flow of information and of the real estate transaction process. Developers gain agility and data ownership, while buyers benefit from transparency and fairer pricing. In the age of the internet and AI, platforms that allow direct engagement with buyers offer a practical and more efficient alternative to the conventional model that puts control, data, and insight back into the hands of those who create real value.
Attributed to Twinkle Aswani, Editorial division, Integrator Media
Dubai’s push to become a global hub for healthy longevity is moving into a new phase, with the emirate formally setting out a regulatory and investment framework for a sector expected to span healthcare, wellness, technology and increasingly, the built environment.
On Sunday, H.H. Sheikh Hamdan bin Mohammed bin Rashid Al Maktoum approved the strategy and operating budget of the Dubai Longevity Authority, moving the body from establishment into implementation. Created in June, the Authority is the world’s first dedicated regulator for the Longevity, Wellness and Advanced Health sector, with a mandate covering research, clinical trials, manufacturing, commercialisation, investment and infrastructure.
While the strategy is rooted in healthcare and life sciences, its wider focus on healthspan, quality of life and supporting infrastructure comes as wellness is already becoming a significant part of the UAE real estate market.
According to the Global Wellness Institute, the UAE’s wellness real estate market grew from USD 3.3 billion in 2017 to USD 14.6 billion in 2025, with the segment now accounting for more than 12% of total construction making the country among the world’s fastest-growing wellness real estate markets
The shift is increasingly visible in Dubai, where a growing number of developments are moving beyond conventional gyms and swimming pools towards concepts centred on sleep, air and water quality, movement, recovery, biophilic design, social connection and preventative wellbeing.
One example is EYWA Tree of Life by R.Evolution, positioned as Dubai’s first fully longevity-led residential development, using neuroarchitecture and biophilic design principles to create an environment designed to support residents’ long-term health and wellbeing.
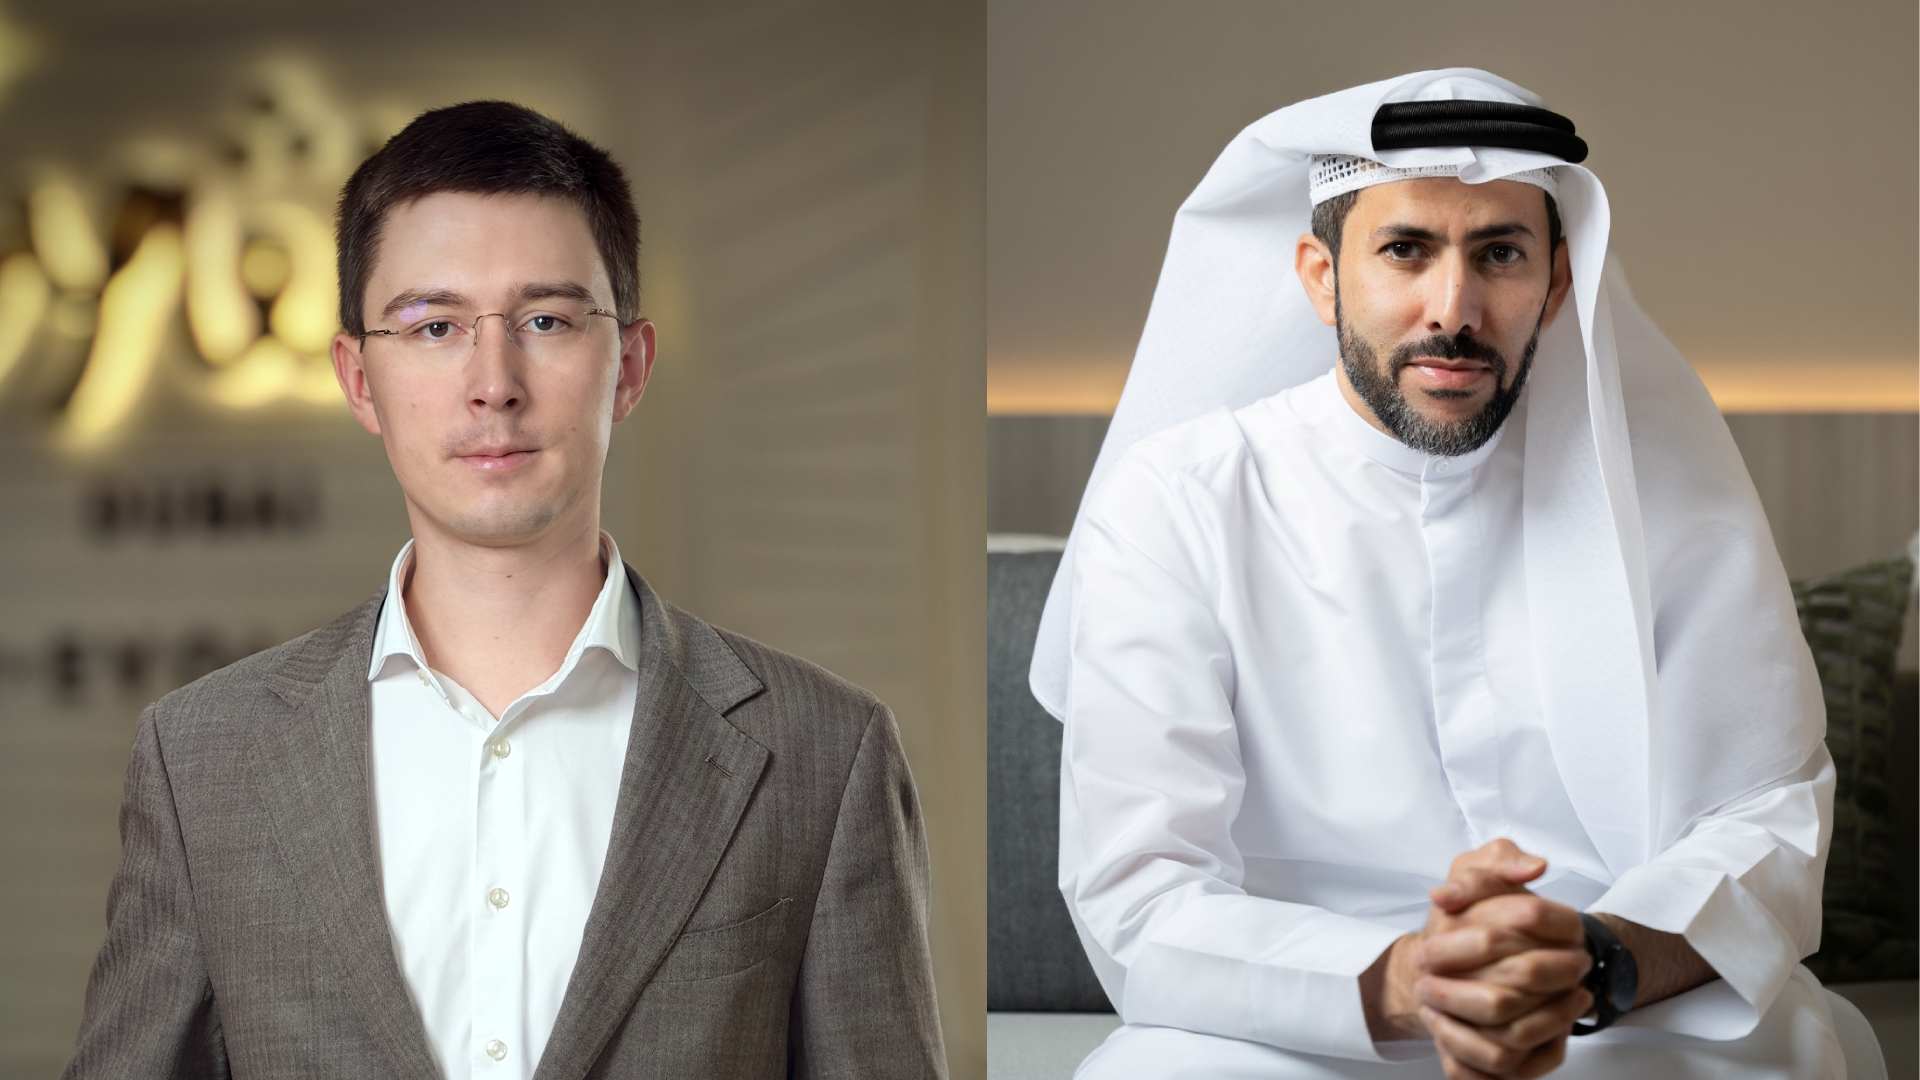
“The significance of the Longevity Authority is that it broadens the conversation from treating illness to supporting healthspan over the long term. We spend around 90% of our time indoors, so the built environment has a meaningful role in how well we live and age. Longevity in real estate therefore goes beyond adding wellness amenities. It means considering how every element of a home, from air quality and light to movement, recovery and social connection, can support healthier daily routines over many years. As this thinking becomes more established, it could begin to influence wider industry expectations, shaping how developments are designed, planned and, potentially, regulated in the future.” said Igor Karpikov, CCO of R.Evolution.
The movement also coincides with the UAE’s growing position as a global wellness destination. Industry analysis has previously placed the country among the world’s top 20 wellness and spa tourism destinations, with wellness travellers spending more than USD 5 billion in 2022 and per-trip expenditure exceeding USD 1,500. Dubai has continued adding high-end preventative health, longevity and wellness concepts aimed at an international clientele.
That demand is beginning to influence expectations in residential real estate as well. For affluent buyers, luxury is increasingly being defined by the quality of the environment around them and whether a home can support healthier daily routines over the long term.
“Dubai recorded 296 home sales above USD 10 million in the first half of 2026 alone, showing the depth of its HNWI buyer base. For these buyers, the conversation is increasingly moving beyond size and finishes towards the quality of the environment and how a home supports everyday life. As longevity develops into a more structured sector, these considerations are likely to move from being differentiators in selected projects to more established purchasing criteria across the premium market, particularly as more affluent buyers choose Dubai as a long-term home.” said Abdulla Lahej, Chairman of Amaal.
The creation of a dedicated Longevity Authority could accelerate that transition. Its remit includes attracting investment and talent, establishing regulatory standards and creating an environment in which longevity-focused businesses can test and scale new products and services. As that ecosystem develops, Dubai’s next generation of residential developments could increasingly be shaped around the question: What is this home doing for the health of the person living in it?
By Sima Barazi, Founder of Boom & Mellow
When I first entered retail in Dubai 24 years ago, part of the role of a multi-brand retailer was giving customers access to designers and products they simply couldn’t find here. Today, the situation is almost the opposite. Consumers can access virtually anything, anywhere, at any time.
I believe that has made curation more important, not less. There is simply too much chatter. Between social media, global e-commerce, marketplaces, influencers and fast fashion, we are constantly being shown something new. More choice sounds like a good thing, but at a certain point it becomes overwhelming. The role of a good retailer today is no longer simply to offer products; it is to filter through that noise and help customers discover what is genuinely worth their attention.
We’ve all had the experience of seeing something online that looks fantastic, ordering it impulsively and being disappointed when it arrives. The colour isn’t what you expected, the fabric feels completely different, the quality isn’t there or the piece simply doesn’t look like the photograph. Fast fashion has made experimentation incredibly accessible, but it has also contributed to a culture of constant consumption and disposability.
At Boom & Mellow, our concept store in Dubai, every product has already gone through a filter before it reaches the customer. Whether I am looking at fashion, accessories, fine jewellery or gifts, I am considering the quality, creativity, design and individuality of a piece, but also whether its price makes sense for what it is. Expensive does not necessarily mean overpriced, just as inexpensive does not necessarily mean good value. Materials, craftsmanship, originality and design all have to justify the price.
After more than two decades of buying, much of that judgment becomes instinctive. I genuinely believe some people naturally have an eye for aesthetics and trends, although experience, travel and exposure refine it enormously. Part of the pleasure of being a curator is discovering a designer before everyone is talking about them and recognising that there is something special there. We brought so many brands, including Sarah’s Bag, Alexis Bittar and Kismet by Milka, to our customers early in their journeys, and that sense of discovery remains one of my favourite parts of retail.
But curation isn’t only about predicting the next trend. It is about knowing your customer.
That human relationship has become even more valuable in a digital world. Our customers can walk into our boutique in Dubai, see and touch something, try it on and understand its quality. But that same relationship now continues digitally. Customers WhatsApp us looking for an outfit, a piece of jewellery or a gift; we send photographs and suggestions, help them narrow down the options, send a payment link and can often deliver within Dubai within three hours.
In a way, the modern boutique has become a personal filter. A customer doesn’t necessarily need another website showing her 5,000 options. Sometimes she needs someone whose taste she trusts to show her five. This is particularly true with gifting: often a customer comes to us without knowing exactly what she wants, and part of our role is helping her discover it.
For me, particularly in the last few years, curation has also become about more than aesthetics. Increasingly, it is about purpose.
As a female founder, I am particularly proud that the overwhelming majority of the designers and entrepreneurs represented at Boom & Mellow are women. This wasn’t created as a marketing strategy; it evolved organically through the brands and stories I was drawn to. Over the years, I’ve met extraordinary women who have built independent businesses around their creativity, often while balancing many other responsibilities in their lives.
We also consciously seek out brands whose impact extends beyond the finished product. Through purpose-led brands such as Sarah’s Bag and Inaash, traditional embroidery and craftsmanship can provide work and economic opportunities for women while preserving skills that might otherwise disappear. We also look for products with sustainable or circular elements, because increasingly customers want to understand not only what they are buying, but who made it, how it was made and what their purchase supports.
As a woman, mother and entrepreneur myself, those stories resonate with me. I opened Tiger Lily while pregnant with my first son and Boom & Mellow in Mall of the Emirates while pregnant with my second. Motherhood and entrepreneurship have therefore been intertwined throughout my journey. Building businesses while raising three children taught me to prioritise, adapt and, perhaps most importantly, trust my instincts.
Retail has changed enormously since I began. Trends move faster, customers are more informed and technology has removed almost every geographical barrier to shopping. But I don’t believe technology can replace the human instinct, experience and personal connection that sit at the heart of good curation. The most meaningful choices are rarely made by data alone; they are shaped by context, trust and an understanding of what will make something matter to a particular person.
An algorithm can show us more of what we already like. A great curator can introduce us to something we didn’t even know we were looking for – and, sometimes, to a designer, story or object that stays with us for years.
That, to me, is why curation matters more than ever. In a world overflowing with choice, the future of retail isn’t necessarily about offering customers more. It is about offering them meaning, confidence and the pleasure of being understood. Technology can organise what exists, but only human curation can recognise what is truly worth discovering.
By Eddy Nemri, Vice President at Object 1
Dubai closed the first half of 2026 with roughly AED 420 billion in real estate transactions across more than 112,000 deals, a pace that puts the year on track to beat 2025’s record. Heading into 2026, the consensus among analysts and developers was that this momentum would deepen rather than plateau. Six months on, the numbers back that up, and in several areas the market has moved faster than most predictions anticipated. Here’s how each widely-forecast trend is actually playing out.
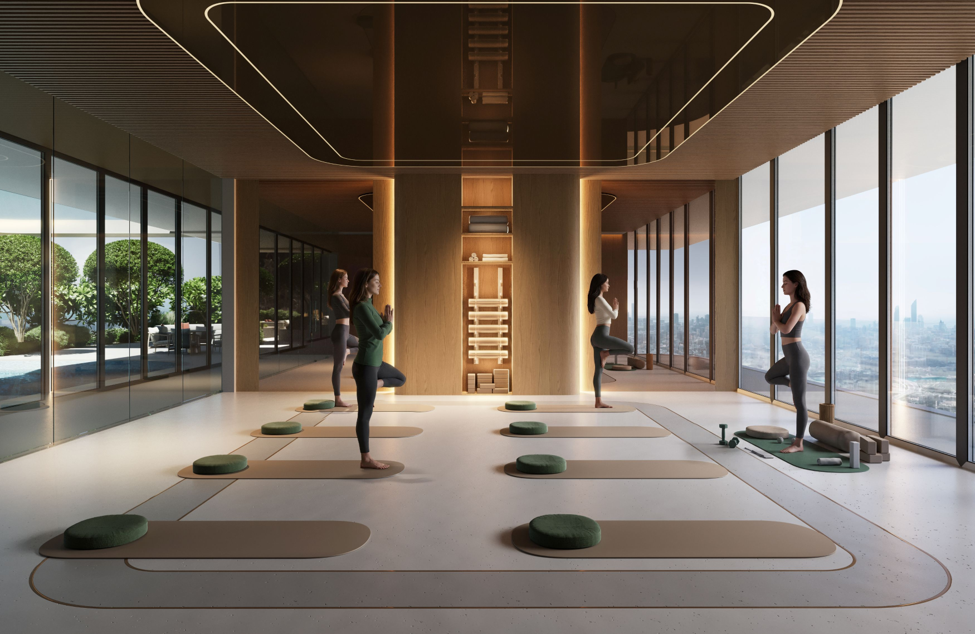
Abu Dhabi’s Breakout Is Confirmed, Not Just Forecast
Abu Dhabi was widely tipped as the next investor hot spot. It has arrived ahead of schedule: property sales reached AED 84.5 billion in H1 2026, up 174% year-on-year and putting the emirate on course for a record year. Al Reem Island led on sales volume, Hudayriyat Island led on value, and together with Yas Island and Saadiyat Island the four districts accounted for roughly two-thirds of both deals and value in the emirate. Off-plan sales dominated activity, and repeat sales prices climbed double digits for both apartments and villas — evidence that this is broad-based demand, not a single-project spike.
Tokenization Has Moved From Pilot to Live Market
Of everything flagged industry-wide at the start of the year, this trend has advanced the furthest. What was a concept in most outlooks is now operational infrastructure: the Dubai Land Department’s tokenization pilot closed out its first phase in February 2026 and opened a regulated secondary market for the tokens issued during it. VARA has since published formal guidance clarifying how tokenized property is regulated as a security at the federal level — the framework younger, cost-conscious buyers need to trust the model is now in place, not just promised. The long-range projection stands: tokenized assets could represent close to 7% of Dubai’s real estate transactions by 2033.
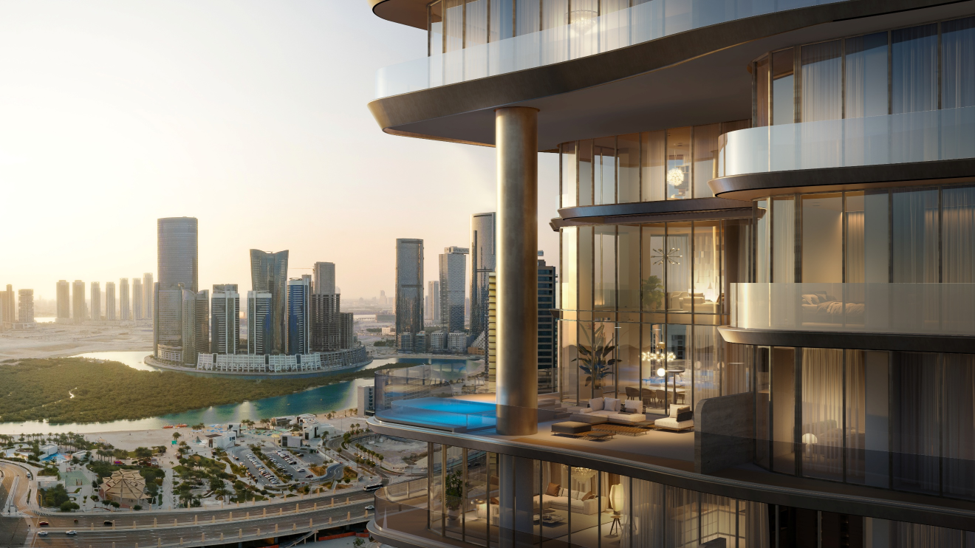
Hybrid Living Keeps Reshaping What Buildings Need to Offer
The shift toward co-working lounges, private meeting pods and serious digital infrastructure inside residential buildings has held steady through the first half of the year. Hybrid work remains structurally embedded in the UAE’s working patterns, and mixed-use communities built around the Dubai 2040 Urban Master Plan’s people-centric principles continue to outperform standard apartment stock on occupancy.
Smart Technology Is No Longer a Differentiator — It’s the Baseline
This trend has accelerated faster than the “becoming standard” framing most predictions used at the end of 2025. Automated systems, data-driven design and energy optimization are now table stakes in new launches rather than a selling point layered on top. The projects gaining the most attention in 2026 are the ones pairing that technical intelligence with genuinely human-centred design, not the ones leading with specs alone.
Connectivity Is Already Repricing Neighbourhoods
The Dubai Metro Blue Line has gone from groundbreaking to visible construction: tunnelling is underway, excavation milestones have been hit ahead of pace, and the RTA has the line on track for roughly 30% completion by the end of 2026, with opening set for September 2029. The RTA’s own modelling points to property values near stations rising by up to 25%, and early anticipation is already visible along parts of the corridor, well before a single station opens.
Wellness Remains a Non-Negotiable, Not a Trend
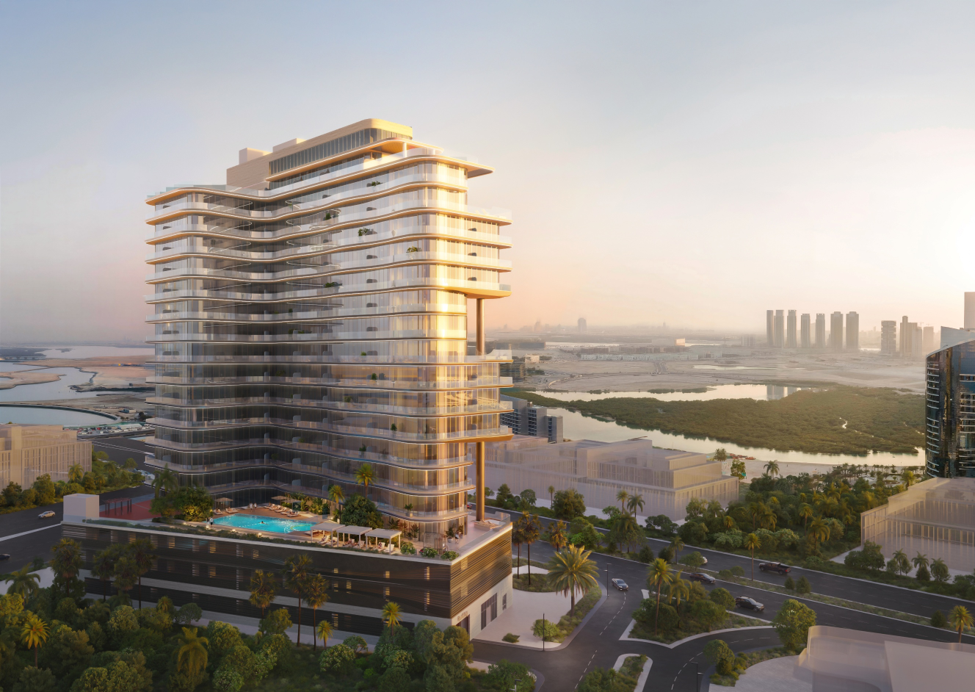
Buyer priorities haven’t shifted here — clean air, natural light, communal space and access to active living are still deciding factors, and biophilic design continues to move from amenity to expectation across new developments.
Regulation Has Tightened Exactly as Predicted
Oversight has strengthened on schedule. At the federal level, the Securities and Commodities Authority was reconstituted as the Capital Markets Authority on 1 January 2026 under new decree-laws, adding a clearer national layer to how capital markets — including tokenized real estate — are supervised. Dubai’s RERA and Abu Dhabi’s regulatory bodies have continued tightening escrow, disclosure and developer-accountability standards alongside it, reinforcing the market’s stability story for global investors.
Where This Leaves the Rest of 2026
Halfway through the year, the story isn’t “will these trends materialize” — it’s how quickly they have. The developers who benefit most through year-end will be the ones who’ve already built for this market rather than the one the industry was forecasting for twelve months ago.

Dubai Longevity Authority Could Accelerate Shift Towards Wellness-Led Homes

TiE Women MENA Crowns Five Regional Winners Ahead of GITEX Global Final

Beyond the camera: Why video surveillance is becoming a business intelligence tool


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai