 Have a question? +971 56 404 0503

Tech Features
How the Middle East Moved Beyond Followers to Build Brands

Yet another compelling new piece by Mariam Abouzeid, Marketing Manager, MEA at Nothing Technology
There is a $771 million evolution happening at the center of the Middle East marketing industry. For the past five years, the global narrative around influencer marketing was built on a flawed premise that reach equals influence. Brands in New York and London debated whether the creator economy was a bubble, while marketers obsessed over vanity metrics and fleeting viral moments. In the GCC, we stopped debating and started building. The influencer marketing market in the GCC is valued at $315.5 million in 2025 and is projected to reach $771.6 million by 2032. But the real story is not the money. It is the maturity.
Having overseen communications strategies that collectively generated billions of impressions across the region, I have watched Dubai and Riyadh transform from emerging markets into the global vanguard of creator led brand building.
The signals are clear. The Middle East is not catching up to the global influencer economy. We are leading it. We are doing it by fundamentally reprioritizing how creators are used, moving them out of the traditional PR umbrella and embedding them as the ultimate engine for mass awareness and deep brand trust. When you look at brands like Huda Beauty, which generates over $75 million a year through the strategic amplification of creator content, you see the blueprint for the future. Huda Kattan built a billion dollar empire right here in Dubai not by treating influencers as a PR add on, but by embedding them into the core architecture of the brand. This creator first model has paved the way for a new generation of Middle East beauty empires, from Youmna Khoury’s Youmi Beauty to Aliona Shcherba’s Aliona Cosmetics, proving that the region is no longer just consuming global beauty trends. It is exporting them.
The Mass Awareness Machine
Before we examine where the Middle East is going, it is worth understanding the foundation it has built. Influencers are the most powerful mass awareness engine ever created. In a region where the GCC is on track to have 263,000 active influencers in 2025, brands have access to a decentralized media network that no television buy or billboard campaign can replicate. When 60 percent of Saudi users and 48.1 percent of UAE users use social networks as their primary tool for researching brands and products, creators are not supplementing the media plan. They are the media plan. According to EMARKETER, US social network amplified content ad spending is projected to match creator sponsored content revenues at $14.15 billion in 2027 before surpassing them in 2028. Brands are about to spend more money boosting creator content than they pay
creators to make it. In the UAE and Saudi Arabia, this strategy is already taking hold. Ounass, the Middle East premier luxury e-commerce platform, provides a perfect example of this evolution. They do not just pay influencers for one off posts. They use data driven insights to identify top performing creators, then amplify that content through targeted performance marketing, blending emotional storytelling with rational product attributes to build a luxury narrative that resonates deeply with Gulf consumers and drives measurable return on ad spend/ But here is where the Middle East diverges from the global playbook. While Western brands are still treating influencers purely as awareness tools, the GCC has moved further up the value chain.
The QSR Reality Check: Awareness vs Consideration
To understand this shift, look no further than the highly competitive food and dining sector in the Middle East. This is a category where influencer marketing has been deployed more aggressively than almost any other. At the mass market end, brands like Americana operating KFC and Pizza Hut, McDonald’s, Papa Johns, and Subway pour millions into influencer campaigns to stay top of mind. Yet AlBaik, the beloved Saudi homegrown champion, topped YouGov KSA QSR Rankings 2026 with a consideration score exceeding 50 percent, a position built on decades of genuine consumer love, not just influencer hype. Global giants McDonald’s and KFC follow at 26.9 percent and 23.2 percent consideration respectively, despite their enormous social media presence.
At the premium end, the contrast is even sharper. Shake Shack, Five Guys, P.F. Chang’s, Joe & The Juice, and homegrown hero SALT have all built their GCC presence on the back of creator driven content, using beautiful food photography, viral reels, and influencer queues around the block. Nobu and Zuma in Dubai have become synonymous with aspirational lifestyle content, their dining rooms perpetually filled with creators documenting every dish.
Consider the rise of % Arabica. The Kyoto born coffee brand has grown into a $1.3 billion global giant with virtually zero traditional marketing. In the UAE, its minimalist, highly aesthetic stores were designed specifically for the Instagram and TikTok era. The brand relies entirely on organic discovery, user generated content, and influencer footfall to drive its massive queues. It is the ultimate example of a brand built entirely on the back of social media awareness and creator aesthetics .
The stories of FIX Dessert Chocolatier and Bi Laban are perhaps the most instructive. FIX Can’t Get Knafeh of It chocolate bar became a global social media phenomenon in 2024 and 2025, generating a staggering 1,259 percent year over year explosion in social conversations. The viral awareness was undeniable, leading to $22 million in sales at
Dubai Duty Free in the first quarter of 2025 alone 10 . But as the Ehrenberg Bass Institute for Marketing Science noted, the viral fad diluted the brand identity, turning a specific product into a generic design brief copied by everyone 11 . Similarly, Bi Laban became a regional sensation engineered through influencer seeding and relentless creator buzz. The queues were real. But when the hype faded, the business fundamentals were exposed. Viral awareness, it turned out, is not a substitute for operational excellence, quality consistency, and genuine consumer loyalty.
The data reveals a stark reality. Hype does not seamlessly translate into habit. While 53 percent of Saudi residents eat fast food weekly, their ultimate choice of where to dine is driven by cleanliness at 48 percent and price at 46 percent, operational realities that no influencer can fake 12 . Influencers drive the initial discovery, cited by 61 percent of consumers as their source for finding new spots, but they are highly inefficient at closing the sale 12 .
The Cost of Misalignment: When Influence Breaks Brands
If the Middle East is learning how to build brands through creators, the global market has provided the ultimate cautionary tales of what happens when influence is misaligned with brand equity. The collapse of the Adidas and Yeezy partnership remains the most expensive influencer marketing failure in history. Adidas tied its cultural relevance to a single, highly volatile creator. When the relationship imploded, Adidas posted its first annual loss in 30 years, warning of a $1.3 billion revenue hit due to unsold inventory 13 . The lesson for regional brands is clear. Renting cultural relevance from a creator without building your own brand equity is a catastrophic financial risk.
Similarly, Pepsi infamous Kendall Jenner campaign remains the textbook example of scripted authenticity failing spectacularly 14 . Pepsi paid a massive premium for Jenner reach, assuming her follower count would automatically translate into cultural resonance. Instead, the tone deaf execution sparked a global backlash, proving that massive awareness without genuine cultural alignment actively damages brand trust. These global failures have taught Middle East marketers a crucial lesson. Awareness without alignment is dangerous. Influence must be anchored in trust, not just reach.
The Beauty Blueprint: From Awareness to Empire
If the F&B sector illustrates the limits of viral conversion, the beauty and luxury sectors provide the blueprint for the great reprioritization. Huda Kattan built Huda Beauty into a billion dollar empire using this exact logic. She did not treat influencers as a direct sales channel. She treated them as a massive awareness engine. Today, Huda Beauty generates over $75 million a year through paid media amplification of creator content. The brand understood early that organic influencer
posts build top of funnel awareness, but it is the paid amplification of that content that drives actual scale.
Similarly, Mona Kattan fragrance brand Kayali has mastered this shift. Kayali does not rely on influencers to push promo codes. It uses them to build cultural relevance and awareness around scent layering. The result? According to Sephora merchant partners, Kayali now has one of the highest repurchase rates in the entire fragrance category globally 15 . The brand uses influencers to get the consumer attention, but relies on product quality and brand equity to secure the conversion and the repeat purchase.
This blueprint is now being replicated by the most powerful creators in the GCC. Kuwaiti influencer Noha Nabil leveraged her massive regional following to launch Noha Nabil Beauty, building a brand deeply rooted in Arab culture and diversity that earned her a spot on the Forbes Women Behind Middle Eastern Brands list 16 . Similarly, Emirati superstar Balqees Fathi transformed her 13 million Instagram followers into a luxury cosmetics empire with Bex Beauty, merging global innovation with specific GCC beauty ideals 17 .
These founders understand that influence is the spark, but operational excellence and cultural alignment are the engine.
The Trust Capital of the World
This is why the Middle East is winning. Brands here have realized that influencers are not a shortcut to conversion. They are the architects of trust. According to the 2026 Edelman
Trust Barometer, global trust is contracting inward. People are retreating into insular, values aligned circles, making it harder than ever for mass corporate messaging to penetrate 18 . Yet, the UAE topped the 2026 Edelman Trust Index globally with a score of 80 out of 100, up eight points from the previous year 19 .
Why? Because brands in the UAE and Saudi Arabia understood early that trust cannot be broadcast. It must be brokered. As Edelman research highlights, in an insular world, trust is built and scaled by creators who act as cultural mediators 18 .
This is backed by new academic research. A 2026 study from Imperial College Business School on influencer authenticity found that the era of renting credibility through one off posts is over 20 . Professor Omar Merlo research proves that when brands treat influencers as long term partners rather than transactional media channels, they move from a transactional to a transformational relationship with consumers 20 .
The Global Validation: Unilever Pivot
The model pioneered in the Middle East is now being adopted by the world largest advertisers. In early 2026, Unilever made a declaration that validated everything regional marketers have been building. The FMCG giant shifted 50 percent of its total digital advertising budget away from traditional corporate ads and directly into social media and creators 21 . By April 2026, that commitment had translated into a network of 300,000 influencers actively promoting Unilever brands globally 22 .
Unilever CMO Leandro Barreto described the strategy as building Desire at Scale, using creators to embed brands authentically in culture 22 . This is exactly what the Middle East has been doing for years. When a global giant like Unilever restructures its entire marketing apparatus to match the creator first model, it proves that influencer marketing has officially graduated from the PR department to become the central nervous system of modern brand building.
The Academic Consensus on Brand Value
The data is clear, and the academic consensus is catching up to what we already know in the GCC. A recent Harvard Business Review study on how brand associations drive customer spending found that what consumers spontaneously think about a brand matters far more than what they agree with on a rating scale 23 . The research proves that brand equity is built through deep, authentic associations over time.
Furthermore, as McKinsey 2026 State of Marketing report highlights, branding has returned as the number one priority for marketing leaders globally 24 . CMOs view branding ability to drive distinctiveness and embody a clear value proposition as critical to building competitive differentiation 24 . In the Middle East, we know that the fastest, most authentic way to build that distinctiveness is through the voices of trusted creators.
The Way Forward: Leading the Next Era
The next wave of global marketing innovation will not come from Silicon Valley or Madison Avenue. It is coming from Dubai and Riyadh. According to EMARKETER, 57 percent of ad buyers globally say influencer ads and partnerships are their top investment priority for 2026. The world is finally waking up to the power of the creator economy, but the Middle
East is already living in its future.
We have moved past the vanity metrics. We have moved past the debate over whether influencers belong in PR or paid media. We have built an ecosystem where creators are the undisputed architects of mass awareness, brand trust, and deep consideration.
The Middle East audience is among the most digitally connected and brand aware anywhere in the world, and it expects marketing strategies that reflect that level of sophistication. Influencer marketing is not just growing here. It is setting the global standard. The brands that recognise this will not just win the region. They will lead the world.
Kayvan Karim, Programme Director of MSc Software Engineering, School of Mathematical and Computer Sciences, Heriot-Watt University Dubai
For the past few years, the AI infrastructure race has largely been measured in scale: more GPUs, larger data centres and greater power capacity. That expansion is continuing, but the economics are beginning to change. Competitive advantage may increasingly depend not only on securing additional power, but on extracting more useful AI work from the power already available. Part of the reason is a change like AI demand. We are moving from relatively simple prompt-and-response systems towards agents that can reason across multiple steps, call tools, inspect results, revise plans and continue working autonomously. Anthropic’s latest Economic Index notes that Claude usage is increasingly shifting towards long-running agentic tasks and that more computationally intensive conversations tend to be associated with higher-value outputs.
This transition could have significant implications for infrastructure demand. A chatbot might generate one answer to one prompt. An agent performing a software-development, research or business task may invoke a model dozens of times, maintain a large context, call external tools and generate many intermediate reasoning steps before producing an outcome. Demand may therefore grow in two ways: more people using AI and more inference, model calls, and tokens processed for each task. Major AI laboratories are already working on this efficiency problem. OpenAI says one of its primary inference objectives is to serve more tokens from the same hardware, using techniques including scheduling, caching, kernel optimisation and improved model implementation. It also describes GPT-5.6 as being trained to accomplish more work per token. Google DeepMind is pursuing a similar direction: its Gemini 3.6 Flash was designed for scaled agentic workloads and uses fewer output tokens than its predecessor on several evaluations. In contrast, its recent agentic video system reduced token consumption by up to 88% for that workload.
Other approaches address efficiency at the model architecture level. DeepSeek-V3, for example, uses a Mixture-of-Experts design with 671 billion total parameters but activates 37 billion per token, so only part of the network is used for each computation. Meta has similarly worked on inference efficiency through grouped-query attention and more efficient tokenisation; the Llama 3 tokeniser was reported to require up to 15% fewer tokens than Llama 2 for equivalent text. Taken together, these approaches show that model capability is increasingly being developed alongside the cost of delivering it.
Model-level efficiency, however, is unlikely to remove the infrastructure constraint on its own. Global data-centre electricity consumption was approximately 415 TWh in 2024, according to the International Energy Agency, and its base case projects this to reach around 945 TWh by 2030. AI is expected to drive most of that growth. Efficiency is therefore improving while aggregate demand continues to rise. One reason is the Jevons, or rebound, effect: efficiency improvements reduce the resources required for each unit of work, but lower costs can also encourage greater overall use. If agents become much cheaper to operate, organisations may respond by deploying more of them, running them for longer, or applying them to tasks that were previously uneconomic. Efficiency can reduce the compute required for an individual task while still increasing total demand.
That increased demand meets infrastructure that cannot expand as quickly. Models and software can improve quickly, but grids, substations, transformers and power-generation infrastructure usually have much longer development cycles. The IEA notes that while a data centre can sometimes be developed within two or three years, the broader energy infrastructure required to support it often involves longer planning and construction periods. Where grid capacity is constrained, each available megawatt becomes a more valuable production resource. The amount of power available remains important, but so does the amount of useful computation that can be produced within that power envelope.
That changes how we should understand capacity. Improvements in accelerator performance, model architecture, workload scheduling, caching, utilisation and inference software can increase computational output without increasing a site’s electrical connection. OpenAI’s recently reported Jalapeño inference hardware illustrates the direction of travel: the company says the chip can deliver more AI work per unit of power while increasing throughput and reducing latency. Efficiency can therefore act as a form of virtual capacity. If two operators each control 100 MW, but one can consistently deliver substantially more useful AI work within that power envelope, their nominal capacity may be identical while their productive capacity is not.
The same constraint applies to physical space and cooling. AI systems are concentrating more computational power into individual racks, increasing both power density and heat output. Packing more accelerators into the same building only creates useful capacity if the electrical and thermal infrastructure can support them. This is one reason liquid cooling is moving from a specialist technology towards a more central part of AI data-centre design. Microsoft, for example, has introduced a closed-loop chip-level cooling architecture that it says eliminates evaporative water consumption for cooling and could avoid more than 125 million litres of water annually per data centre. The example also shows why power, cooling, water use and rack density cannot be treated independently.
The same shift creates a measurement problem. Power Usage Effectiveness, or PUE, has been valuable for showing how much facility energy is required beyond the electricity IT equipment consumes. It does not, however, measure whether that IT equipment is producing useful work efficiently. Uptime Institute’s 2025 survey placed average PUE at around 1.54 and noted that the headline industry figure had changed little for six years. Uptime has consequently argued for productivity measures that relate computational work to energy consumption. For AI inference, tokens per kilowatt-hour might offer one operational measure. Still, even that is incomplete: an efficient model that solves a task in 1,000 tokens may be more valuable than one generating 10,000. A more useful long-term measure may therefore be useful AI work per unit of energy, water and infrastructure.
Capacity will remain essential. The AI industry will continue to build larger data centres, secure new power supplies and deploy large quantities of computing hardware. As agentic systems create more persistent inference demand and physical resources become harder to expand, however, efficiency may increasingly determine the productive value of that capacity. Operators that can support more useful computation within the same power, cooling, water, and space constraints can accommodate more workloads without waiting for equivalent growth in physical infrastructure.
For AI infrastructure, installed megawatts will remain a headline measure. The more consequential measure may increasingly be how much useful AI work those megawatts can support.
Tech Features
TrendAI™Expands Vision One with New Security Capabilities for AI Agents and Application Development

TrendAI™, the global AI security leader and enterprise business unit of Trend Micro Incorporated (TYO: 4704; TSE: 4704), has announced new capabilities for TrendAI Vision One™. These include the private preview of Autonomous Vulnerability Discovery and expanded support for Claude’s Compliance API, which now covers Claude Code and Cowork sessions. Together, these services help enterprises identify exploitable vulnerabilities in source code before attackers do, investigate how AI agents operate, and maintain oversight as AI adoption scales.
The need for this oversight is growing rapidly across the region. According to research conducted by The Harris Poll for Dataiku, 62% of UAE chief information officers believe their organisation have more than 50 AI agents running in production, yet only 18% have a fully unified view of agents across platforms, data environments, and business applications. At the same time, AI is accelerating both how quickly code is written and how quickly attackers can identify flaws. Security teams therefore need to keep pace with AI adoption without losing visibility into what is happening across their environments.
The new capabilities extend TrendAI Vision One™ across both software development and AI agent activity. TrendAI Vision One™ Autonomous Vulnerability Discovery is powered by AESIR, TrendAI’s agentic exploit-remediation engine, which identifies and validates vulnerabilities, including zero-days. It also verifies fixes in customer source code. The engine uses purpose-built, multi-model AI architecture that relies primarily on Anthropic models and has outperformed single-model and agentic system scores on the CyberGym Leaderboard. Every finding is validated by experts from the TrendAI™ Zero-Day Initiative™ (ZDI), the world’s largest vendor-agnostic bug bounty programme. The Autonomous Vulnerability Discovery is deployed and operated on Amazon Bedrock from Amazon Web Services (AWS), enabling the full workflow to run within the customer’s AWS environment
In parallel, the expanded Claude Compliance API integration brings Claude Code and Cowork session records from Claude Enterprise into TrendAI Vision One™. These records include prompts, responses, and tool calls, each tied to a verified user. It enables security teams to investigate AI activity in context, correlate it with endpoint, identity, cloud and network signals, and build custom detections for relevant agent behaviour.
Commenting on the announcement, Salah Suleiman, Managing Director, South Gulf, TrendAI™, said, “AI is changing both how software is built and how work gets done across the enterprise. Code is being written faster than ever, while AI agents are increasingly able to access systems, call tools and act on behalf of users. As organisations across the UAE and the wider region scale AI at pace, their security teams need to identify vulnerabilities early while maintaining clear visibility into what AI systems are doing and whether their actions align with organisational policies. With these additions to TrendAI Vision One™, we are helping organisations move faster with AI while maintaining the context, oversight and control needed to do so securely.”
TrendAI Vision One™ also continues to ingest activity logs from Claude Enterprise, covering user logins, administrative actions and configuration changes, as well as from Claude Platform, covering administrative, system and resource events. Autonomous Vulnerability Discovery is now available in private preview to select enterprise customers running on AWS, while Claude’s Compliance API integration in TrendAI Vision One™ is available to TrendAI Vision One™ customers using Claude Enterprise.
Dr Ryad Soobhany, Deputy Academic Head of School of Mathematical & Computer Sciences, Heriot-Watt University Dubai
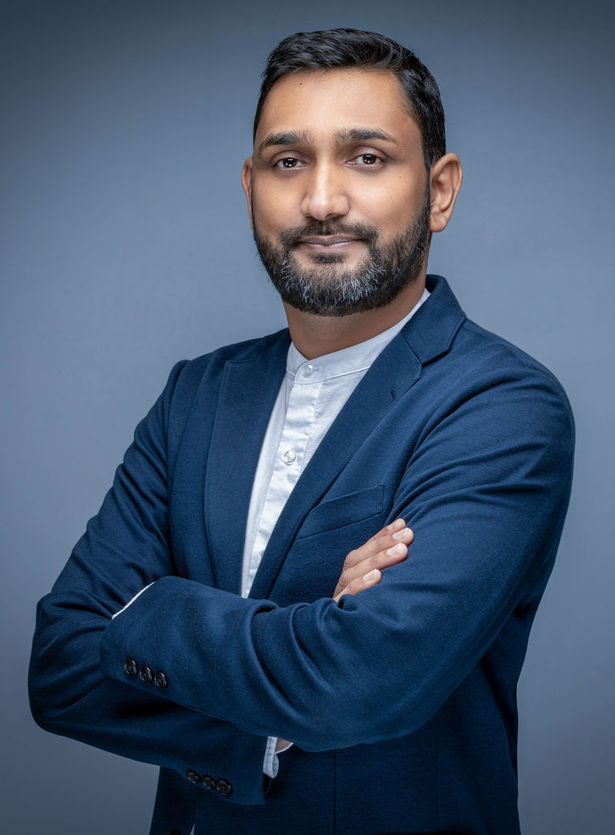
Camera systems, such as CCTV, are mainly used for video surveillance within organisations. Passive video surveillance has been part of the security ecosystem for years, providing organisations with the ability to monitor different areas simultaneously, while recorded footage can be inspected after an event occurs.
The evolution of computer chips and increased processing power has led to improved image quality, including better performance in low-light conditions, particularly at night. The advent of edge computing, with processing performed on edge devices within a network, has made object and scene recognition more readily accessible. This evolution has led to more active video surveillance through video analytics, where events can be identified and addressed in real time. Examples include number plate recognition systems and facial recognition for access control.
With the combination of AI and video data, computer vision can be integrated with business analytics to transform video surveillance from a security infrastructure into a business intelligence tool. Video surveillance is moving from passively recording events to sensing what is happening in the environment. This helps to answer questions such as which areas are congested, how customers are moving, how long they dwell in particular areas, and whether unusual events are occurring. Businesses can use this data to optimise their operations, such as improving the customer checkout process, monitoring asset or staff movement, and managing crowds or traffic flows. Organisations can also incorporate contextual business information to enhance the analytics by combining behavioural data with CRM or IoT data, providing additional context and insights for decision-making and improving the customer or visitor experience.
Video surveillance can be used to optimise operations, improve customer experiences, and support strategic decision-making across industries. Video itself does not create business intelligence; rather, its value increases when visual information is combined with other operational and contextual data, while computer vision is used to understand and enhance business operations. The pipeline from video to business intelligence can be represented as obtaining data from video sources such as fixed cameras, IoT-enabled cameras, or robots. Computer vision is then applied to the video to detect or track people, objects of interest, or activities. Behavioural data are taken into account, such as customer dwell time in particular product areas, occupancy of rooms or halls, movement of people across a building, and anomalies in behaviour. At this stage, operational data are also considered. The final stage is the business intelligence stage, where trends are identified and insights are inferred. At this stage, data visualisation plays an important role, with dashboards and data storytelling displaying correlations, predictions, and infographics that provide more than simple visual summaries of surveillance data. The camera becomes an operational sensor for the organisation. The important transformation occurs when visual data are combined with business data, such as sales, operational, and IoT data, to convert visual observations into business knowledge that informs operational, tactical, and strategic decision-making within an organisation.
The levels of business intelligence can be viewed as three analytical capabilities: descriptive intelligence, diagnostic intelligence, and combined predictive and prescriptive intelligence. Descriptive intelligence usually addresses what is happening. Visual analytics can identify footfall, occupancy, queue length, waiting time, dwell time, traffic flow, movement patterns, and detected events. Visualisation dashboards can present these indicators in real time or over historical periods, allowing managers to understand the current state of an operation. For example, a museum dashboard can show heat maps of visitor numbers, dwell time, and movement across different exhibition areas, while analysing visitor behaviour and providing insights into the optimal placement of exhibitions. An airport dashboard could display passenger volumes and queue lengths across terminals.
Terrace Dining, Oktoberfest, and Beach Days Return to InterContinental Abu Dhabi This October

THE STORIES BEHIND THE MATERIALS SHAPING UAE INTERIORS
Form Room welcomes new JVC residents with a complimentary coffee and exclusive discounts


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai