 Have a question? +971 56 404 0503

Tech Features
FROM SMART GRIDS TO SMART CITIES: THE NEXT PHASE OF URBAN INNOVATION

Dr Fadi Alhaddadin, Director of MSc Information Technology (Business), School of Mathematical and Computer Sciences, Heriot-Watt University Dubai
Urbanisation is accelerating at an unprecedented pace, placing immense pressure on cities to become more efficient, sustainable, and resilient. Today, urban areas account for most of the global energy consumption and greenhouse gas emissions, making them central to addressing climate and resource challenges. In response, cities around the world are transitioning from traditional infrastructure systems to advanced, technology-driven models. The evolution from smart grids to fully integrated smart cities marks a new phase of urban innovation.
At the core of this transformation lies the smart grid. Unlike standard energy systems, smart grids use digital communication technologies to enable real-time interaction between energy providers and consumers. This two-way communication allows for more efficient electricity distribution, improved demand management, and the seamless integration of renewable energy sources such as solar and wind. As a result, smart grids not only reduce energy waste but also enhance reliability and support decentralised energy systems. They form the foundational layer upon which broader smart city systems are built.
However, the true power of smart cities emerges from the convergence of multiple technologies. The Internet of Things (IoT), artificial intelligence (AI), and big data analytics work together to create highly interconnected urban environments. IoT devices ranging, from sensors and smart meters to connected infrastructure continuously collect data on various aspects of city life, including energy usage, traffic flow, air quality, and public services. This data is then analysed by AI systems, which generate insights and enable real-time decision-making.
Through AI-driven analytics, cities can predict energy demand, optimise transportation networks, and detect infrastructure issues before they escalate. For example, intelligent traffic management systems can reduce congestion and emissions by dynamically adjusting traffic signals based on real-time conditions. Similarly, predictive maintenance systems can identify potential failures in utilities or transportation networks, minimising disruptions and reducing operational costs.
One of the most significant benefits of smart city technologies is their contribution to sustainability. Energy-efficient buildings equipped with smart systems can automatically regulate lighting, heating, and cooling based on occupancy and environmental conditions. Smart transportation solutions, including connected public transit and electric mobility systems, help reduce carbon emissions and improve urban mobility. Furthermore, integrated resource management systems enable cities to optimise the use of energy, water, and other essential services, supporting a more sustainable urban ecosystem. A notable example in the Middle East is Masdar City, which has been designed as a sustainable urban development powered by renewable energy and smart technologies. The city integrates energy-efficient buildings, smart grids, and intelligent transportation systems, demonstrating how digital innovation can support low-carbon urban living.
The Middle East is increasingly positioning itself as a global leader in smart city development through ambitious national strategies and large-scale projects. In Dubai, smart city initiatives focus on digital governance, artificial intelligence, and integrated urban services to enhance efficiency and citizen experience. Similarly, Saudi Arabia’s NEOM project represents a transformative vision of a fully automated and sustainable urban environment powered by advanced technologies. These initiatives highlight the region’s commitment to leveraging innovation to address urban challenges and drive future economic growth.
Beyond environmental benefits, smart cities are designed to enhance the quality of life for their residents. Digital platforms enable more accessible and efficient public services, from healthcare to administrative processes. Smart health systems can improve patient care through remote monitoring and data-driven diagnostics, while intelligent safety systems enhance security through real-time surveillance and rapid emergency response. These advancements contribute to more convenient, inclusive, and liveable urban environments.
Resilience is another critical dimension of smart cities. As urban areas face increasing risks from climate change, natural disasters, and infrastructure strain, the ability to adapt and respond effectively becomes essential. Smart grids play a key role in enhancing energy resilience by supporting decentralised power generation and rapid recovery from outages. Meanwhile, data-driven systems allow city authorities to anticipate and prepare for potential disruptions, improving overall crisis management and response capabilities.
Despite their many advantages, the development of smart cities is not without challenges. The integration of interconnected systems raises concerns about cybersecurity and data privacy, as large volumes of sensitive information are collected and processed. Additionally, the high cost of implementing advanced infrastructure and the need for standardised systems can pose significant barriers. Addressing these issues requires strong governance, clear regulatory frameworks, and collaboration between governments, private sector stakeholders, and technology providers.
In conclusion, the transition from smart grids to smart cities represents a fundamental shift in how urban environments are designed and managed. By leveraging the combined capabilities of IoT, AI, and data-driven infrastructure, cities are becoming more efficient, sustainable, and resilient. This transformation is not only redefining urban systems but also shaping the future of how people live, work, and interact within cities. As this evolution continues, smart cities will play a crucial role in addressing global challenges and improving the overall quality of urban life.
Tech Features
TrendAI™Expands Vision One with New Security Capabilities for AI Agents and Application Development

TrendAI™, the global AI security leader and enterprise business unit of Trend Micro Incorporated (TYO: 4704; TSE: 4704), has announced new capabilities for TrendAI Vision One™. These include the private preview of Autonomous Vulnerability Discovery and expanded support for Claude’s Compliance API, which now covers Claude Code and Cowork sessions. Together, these services help enterprises identify exploitable vulnerabilities in source code before attackers do, investigate how AI agents operate, and maintain oversight as AI adoption scales.
The need for this oversight is growing rapidly across the region. According to research conducted by The Harris Poll for Dataiku, 62% of UAE chief information officers believe their organisation have more than 50 AI agents running in production, yet only 18% have a fully unified view of agents across platforms, data environments, and business applications. At the same time, AI is accelerating both how quickly code is written and how quickly attackers can identify flaws. Security teams therefore need to keep pace with AI adoption without losing visibility into what is happening across their environments.
The new capabilities extend TrendAI Vision One™ across both software development and AI agent activity. TrendAI Vision One™ Autonomous Vulnerability Discovery is powered by AESIR, TrendAI’s agentic exploit-remediation engine, which identifies and validates vulnerabilities, including zero-days. It also verifies fixes in customer source code. The engine uses purpose-built, multi-model AI architecture that relies primarily on Anthropic models and has outperformed single-model and agentic system scores on the CyberGym Leaderboard. Every finding is validated by experts from the TrendAI™ Zero-Day Initiative™ (ZDI), the world’s largest vendor-agnostic bug bounty programme. The Autonomous Vulnerability Discovery is deployed and operated on Amazon Bedrock from Amazon Web Services (AWS), enabling the full workflow to run within the customer’s AWS environment
In parallel, the expanded Claude Compliance API integration brings Claude Code and Cowork session records from Claude Enterprise into TrendAI Vision One™. These records include prompts, responses, and tool calls, each tied to a verified user. It enables security teams to investigate AI activity in context, correlate it with endpoint, identity, cloud and network signals, and build custom detections for relevant agent behaviour.
Commenting on the announcement, Salah Suleiman, Managing Director, South Gulf, TrendAI™, said, “AI is changing both how software is built and how work gets done across the enterprise. Code is being written faster than ever, while AI agents are increasingly able to access systems, call tools and act on behalf of users. As organisations across the UAE and the wider region scale AI at pace, their security teams need to identify vulnerabilities early while maintaining clear visibility into what AI systems are doing and whether their actions align with organisational policies. With these additions to TrendAI Vision One™, we are helping organisations move faster with AI while maintaining the context, oversight and control needed to do so securely.”
TrendAI Vision One™ also continues to ingest activity logs from Claude Enterprise, covering user logins, administrative actions and configuration changes, as well as from Claude Platform, covering administrative, system and resource events. Autonomous Vulnerability Discovery is now available in private preview to select enterprise customers running on AWS, while Claude’s Compliance API integration in TrendAI Vision One™ is available to TrendAI Vision One™ customers using Claude Enterprise.
Dr Ryad Soobhany, Deputy Academic Head of School of Mathematical & Computer Sciences, Heriot-Watt University Dubai
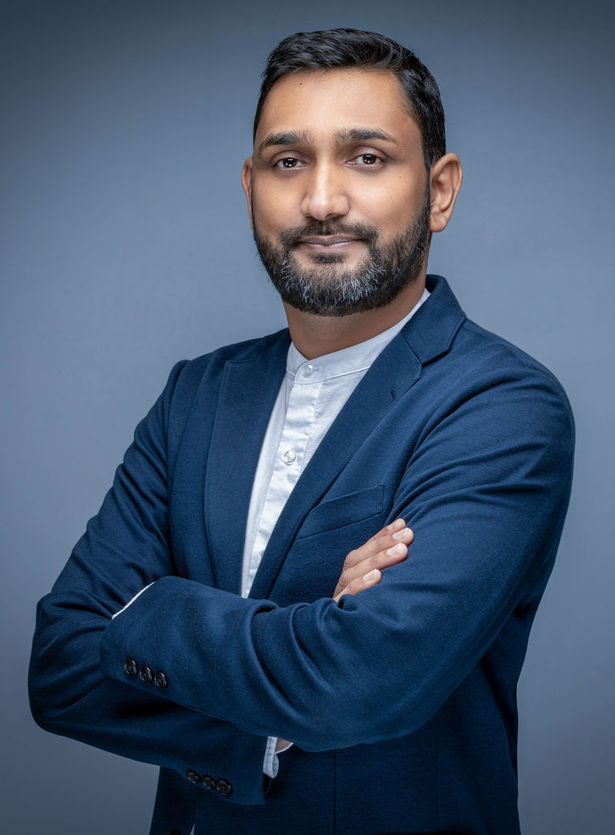
Camera systems, such as CCTV, are mainly used for video surveillance within organisations. Passive video surveillance has been part of the security ecosystem for years, providing organisations with the ability to monitor different areas simultaneously, while recorded footage can be inspected after an event occurs.
The evolution of computer chips and increased processing power has led to improved image quality, including better performance in low-light conditions, particularly at night. The advent of edge computing, with processing performed on edge devices within a network, has made object and scene recognition more readily accessible. This evolution has led to more active video surveillance through video analytics, where events can be identified and addressed in real time. Examples include number plate recognition systems and facial recognition for access control.
With the combination of AI and video data, computer vision can be integrated with business analytics to transform video surveillance from a security infrastructure into a business intelligence tool. Video surveillance is moving from passively recording events to sensing what is happening in the environment. This helps to answer questions such as which areas are congested, how customers are moving, how long they dwell in particular areas, and whether unusual events are occurring. Businesses can use this data to optimise their operations, such as improving the customer checkout process, monitoring asset or staff movement, and managing crowds or traffic flows. Organisations can also incorporate contextual business information to enhance the analytics by combining behavioural data with CRM or IoT data, providing additional context and insights for decision-making and improving the customer or visitor experience.
Video surveillance can be used to optimise operations, improve customer experiences, and support strategic decision-making across industries. Video itself does not create business intelligence; rather, its value increases when visual information is combined with other operational and contextual data, while computer vision is used to understand and enhance business operations. The pipeline from video to business intelligence can be represented as obtaining data from video sources such as fixed cameras, IoT-enabled cameras, or robots. Computer vision is then applied to the video to detect or track people, objects of interest, or activities. Behavioural data are taken into account, such as customer dwell time in particular product areas, occupancy of rooms or halls, movement of people across a building, and anomalies in behaviour. At this stage, operational data are also considered. The final stage is the business intelligence stage, where trends are identified and insights are inferred. At this stage, data visualisation plays an important role, with dashboards and data storytelling displaying correlations, predictions, and infographics that provide more than simple visual summaries of surveillance data. The camera becomes an operational sensor for the organisation. The important transformation occurs when visual data are combined with business data, such as sales, operational, and IoT data, to convert visual observations into business knowledge that informs operational, tactical, and strategic decision-making within an organisation.
The levels of business intelligence can be viewed as three analytical capabilities: descriptive intelligence, diagnostic intelligence, and combined predictive and prescriptive intelligence. Descriptive intelligence usually addresses what is happening. Visual analytics can identify footfall, occupancy, queue length, waiting time, dwell time, traffic flow, movement patterns, and detected events. Visualisation dashboards can present these indicators in real time or over historical periods, allowing managers to understand the current state of an operation. For example, a museum dashboard can show heat maps of visitor numbers, dwell time, and movement across different exhibition areas, while analysing visitor behaviour and providing insights into the optimal placement of exhibitions. An airport dashboard could display passenger volumes and queue lengths across terminals.
By Julio de Salvo, Chief Solution Officer for MENA & APAC at Globant
For decades, the financial industry has managed to replace banknotes and coins with “invisible” assets through different technological implementations. However, innovation in the sector has generally moved at a slow pace when dealing with something as sensitive as people’s finances. In 2026, the black swan is beginning to emerge: the first steps of AI agents that will redefine the industry (as they will many others). The financial black swan is not a crisis: it is a huge change. Across the Middle East and Africa, where a convergence of government-backed modernization agendas, digitally native consumers, and institutional ambition is accelerating the timeline for transformation.
The first step has been the use of Gen AI without the customer perceiving it. Coding, fraud prevention, phishing detection, and credit assessment are some of its tasks. But it is now beginning to become a tool for managing users’ finances. In the MENA region, this shift is already visible at the institutional level. Across the 25 MEA banks benchmarked by the Evident AI Index (June 2026), the established leaders are no longer running pilots, they are directing investment toward high-friction processes where AI can materially reshape productivity, scalability, and competitiveness. UAE-based banks and fintechs are already validating agent-initiated transaction pipelines in production environments. These are some of the examples, but there are more.
In July 2026, the revealing Mills Review, published by the FCA (Financial Conduct Authority), the UK’s official financial regulator, pointed out that AI agents will become the new financial interface. Essentially, an AI assistant will manage budgets, answer queries, generate reports on demand, and move money between accounts. How much was spent on a vacation in total, how a stock portfolio performed over the past month, or canceling an annual subscription will be as easy as making a query to ChatGPT today. For MENA consumers, who have in many cases leapfrogged legacy banking behaviors entirely, this vision is the baseline expectation.
The Mills Review also argues that Open Banking will evolve toward a model in which AI agents will have access to a broader range of financial products to enable intelligent decisions across different areas, and highlighted that this will lead to an evolution in regulation. In the GCC, this evolution is being actively shaped by regulators and governments alike, with initiatives such as Dubai’s target of 90%+ digital transactions by 2026 signaling not just ambition, but structural commitment to a cashless, AI-enabled financial ecosystem.
The agentic AI opportunity in the region is real, but it remains underexploited. According to EY-Parthenon’s 2025 Generative AI in Banking Survey, 99% of respondents are familiar with agentic AI, yet only 31% have pursued implementation, with a further 46% expressing interest. Awareness, in other words, has raced ahead of execution. This gap between recognition and production-grade deployment is precisely where the competitive battle will be won or lost.
This represents a major shift in the industry, where historically the leading banks have, for the most part, remained the same. Differentiation can now change everything, and it would not be surprising if new players manage to break into the ranks of the world’s most important financial institutions. In the Middle East, the region’s financial landscape already includes a new generation of digital-first challengers sitting alongside heritage institutions, all of which are now actively exploring or deploying agentic capabilities. The reason sounds obvious when explained: if the experience with an AI assistant can manage customers’ money better, it will prevail. This is not an exaggeration: just four years ago, nobody knew ChatGPT, and now we have become so accustomed to it that we all ask ourselves: why shouldn’t I manage my assets with a chatbot that can provide reports and recommendations? A study by JPMorgan found that half of Gen Z wanted to use them to manage their finances.
The infrastructure for agentic commerce is also being built in real time across the GCC. Mastercard has conducted regional pilots in partnership with Majid Al Futtaim, enabling consumers to search, select, and purchase VOX Cinema tickets programmatically through an integrated AI assistant. In May 2026, Visa launched its global Agentic Ready program in the UAE, with early adopters including ADCB, ADIB, Emirates NBD, Mashreq, Tabby, Wio, and Ziina already validating agent-initiated transaction pipelines in production.
We are living in a time of change. In its 2026 report on the financial sector, the World Economic Forum urged organizations to move with “urgency” and “discipline”. The greatest benefits, it stated, will go to those working on a holistic redesign of workflows and technology architecture. In the MENA region, the conditions for genuine transformation are already in place: strong institutional will, government-aligned modernization agendas, and a consumer base that has leapfrogged legacy behaviors entirely.
One of the major questions is why, if the financial sector has such a strong technological tradition, the emergence of AI Agents represents a black swan. There are several reasons. First, historically, customers used banks to execute transactions; therefore, in the executive conversations avoiding risk was prioritized over innovation. This is changing with the emergence of digital banks, which are generally more inclined toward disruption, and shifts in consumer habits. In the GCC specifically, consumers who bypassed branch banking and moved directly to mobile-first financial services are now primed to embrace AI-managed financial experiences with little friction. The challenge of the future is not to provide a tool, but to redesign experiences to address this transition comprehensively. AI has the potential to resolve the technological debt involved in migrating traditional banks, which have historically struggled the most with this transition.
The second reason is the technical debt banks have demonstrated in dealing with change. This has also occurred in other industries, but the idea of paying for a premium license for every employee and expecting immediate returns only leads to frustration. There is significant resistance when it becomes clear that certain tasks and workflows will inevitably be different from what has been established. In the Middle East, where several national banks have invested heavily in core banking modernization programs over the past decade, the foundations are more favorable than in many Western markets, but the final leap from modernized infrastructure to genuinely agentic deployment still requires focused capability and deliberate execution.
The third reason is regulation. Technology companies, banks, and authorities will need to maintain an ongoing dialogue to ensure that innovation and integrations do not affect users’ personal data or security, while ensuring that restrictions do not become a barrier to progress. One of the most valuable lessons from the banking sector’s legacy is the importance of being extremely careful when dealing with something as sensitive as people’s money.
For many years, the impact of AI was often explained as something that belonged to a distant future. In the financial sector, it is already a reality: it is part of multiple tasks and is beginning to become an asset in the customer proposition. With AI Agents, innovation can no longer, and should no longer, go unnoticed. New habits require the redesign of customer journeys, and this could represent a revolution for the sector. For Middle East banks, the opportunity is particularly compelling: a region where government will, consumer readiness, regulatory pragmatism, and institutional investment have aligned at the same moment. What is required now is the execution capability to convert that alignment into production-grade deployment. What is at stake is no small matter: the management of millions of people’s money and a battle for the competitiveness of banks on a scale rarely seen before. For those that move with urgency and discipline, the financial black swan is a transformation to be led.
A REIMAGINED PRIME68 RETURNS TO JW MARRIOTT MARQUIS DUBAI ALONGSIDE ION, A NEW “NEIGHBOURHOOD IN THE SKY”
Radisson Blu Hotel Dubai Deira Creek Invites Guests to Celebrate Diwali with Family, Flavour and Festive Stays
Trust Is the New Speed – AI, Lexis+ with Protégé and the future of legal work in the Middle East


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR10 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai