OPPO A7 Pro 5G puts longevity at the centre of the smartphone experience!
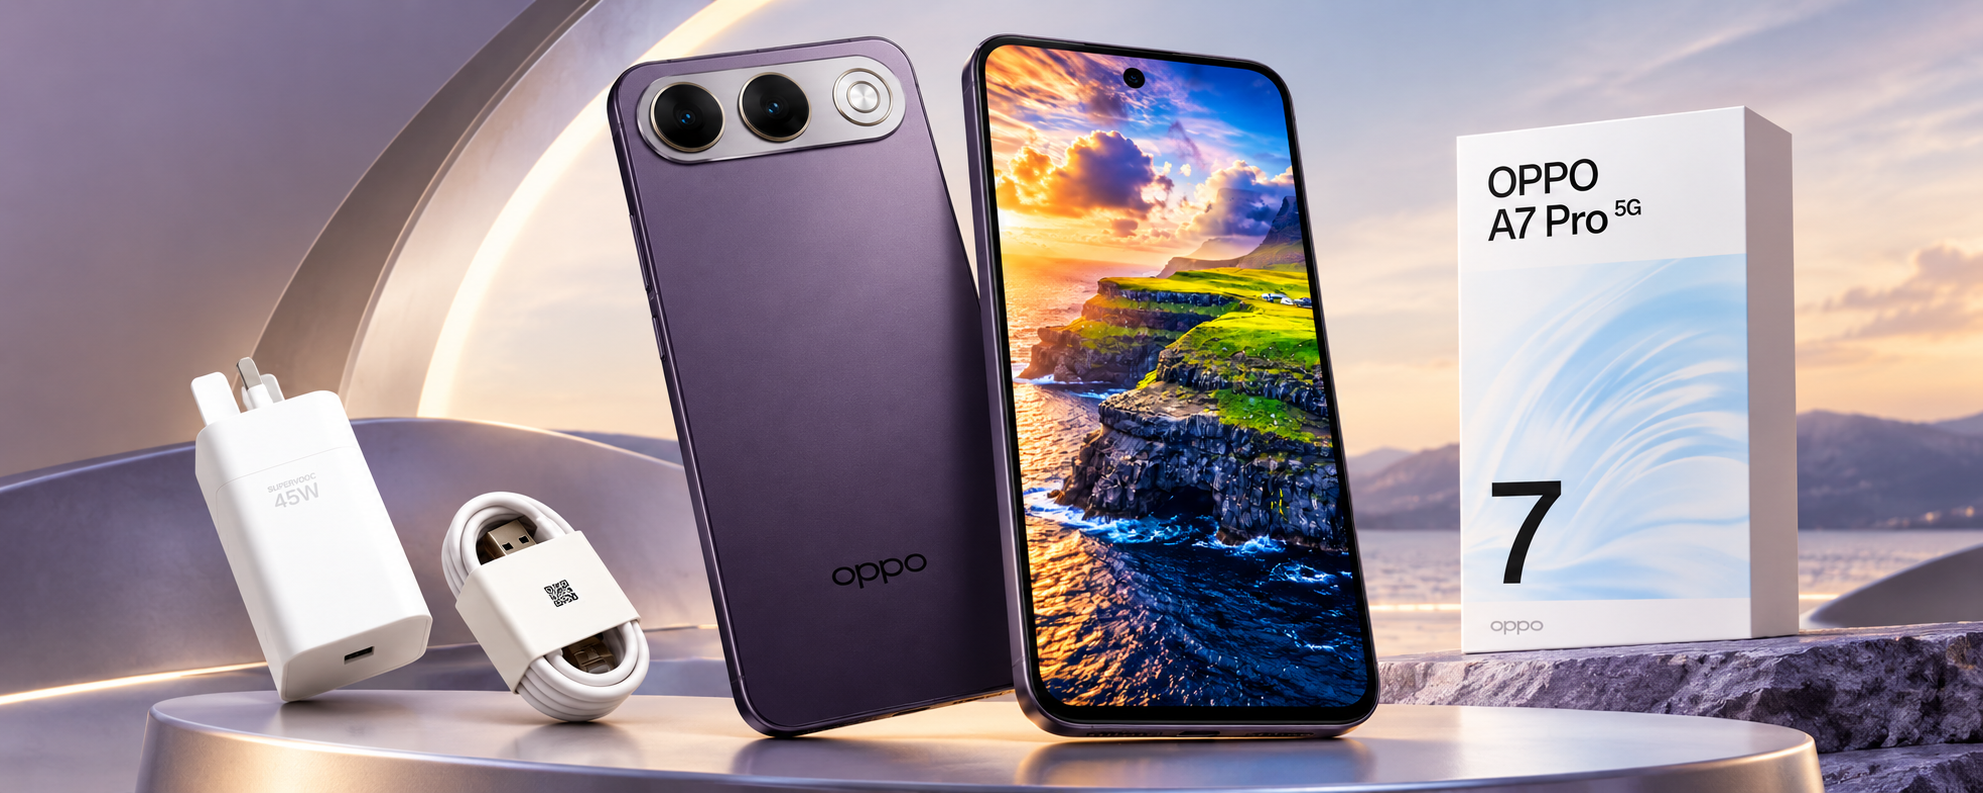
With an 8,000mAh battery, dual 50MP cameras, IP69K protection and a five-year smoothness promise, OPPO’s latest A Series smartphone makes a strong case for devices designed around longer-term ownership.
Smartphone launches have traditionally revolved around faster processors, increasingly sophisticated cameras and, more recently, AI. With the A7 Pro 5G, OPPO is putting another consideration firmly into the conversation: how well a smartphone can hold up over time.
At the centre of that proposition is an enormous 8,000mAh battery. Large-capacity batteries are becoming increasingly common, but what is interesting about the A7 Pro 5G is how little the battery dictates the physical character of the phone.
Despite the capacity, the device does not immediately look or feel like a rugged smartphone. The Shine Titanium review unit has an understated finish, while the alternative Surfing Blue introduces a more distinctive Dynamic 3D Wave Texture.
That relatively conventional appearance hides some serious durability credentials.
Built for longer ownership
The A7 Pro 5G carries IP69K dust and water resistance alongside military-grade shock resistance. Rainstorm Touch is designed to keep the display responsive even when used in heavy rain.
The longevity argument extends to the battery itself. OPPO says it can retain more than 80% of its rated capacity after 2,000 complete charging cycles, underpinning the company’s six-year battery durability proposition.
This matters because battery degradation remains one of the most noticeable compromises as smartphones age. Increasing capacity solves part of that equation; maintaining useful capacity several years into ownership potentially solves another.
Reverse wired charging also allows the A7 Pro 5G to supply power to another connected device, adding some practical value to that substantial battery reserve.
Selfies get the 50MP treatment
OPPO has also placed considerable emphasis on the front-facing camera.
The 50MP Ultra-Wide AI Zoom Selfie Camera offers a 100-degree field of view and can automatically move between 1x and 0.6x framing when additional people enter the shot.
It is a useful approach for group photographs, travel and increasingly video-led social content, where a wider front camera can make considerably more sense than simply increasing resolution. Ultra-steady video has also been included to improve handheld recording.
At the rear is another 50MP camera, using a larger 1/2-inch sensor that OPPO says captures 70% more light than its predecessor.
AI Portrait Glow, AI Popout and AI Remix Collage bring the increasingly familiar layer of computational editing into the camera experience, allowing users to manipulate images without moving immediately to third-party applications.
Five years of smoothness?
Underneath, the A7 Pro 5G is powered by the MediaTek Dimensity 6360 MAX, accompanied by OPPO’s NetworkBoost Chip S1 and AI LinkBoost 4.0.
A 4,300mm² Glacier VC Vapor Chamber handles cooling, while software-based resource and memory management is designed to maintain responsiveness as workloads increase.
Perhaps more interesting than outright performance figures is OPPO’s 5-Year Smoothness Protection. The company says the device has passed its five-year smoothness testing, reflecting a wider attempt to position performance around consistency rather than simply launch-day speed.
Naturally, five-year performance cannot be established during a conventional review period, but the emphasis itself is notable. Smartphone replacement cycles are lengthening, making sustained performance, battery health and software optimisation increasingly relevant purchasing considerations.
AMOLED keeps the experience contemporary
The front houses a 6.57-inch FHD+ AMOLED display with a 120Hz refresh rate, up to 1,400 nits of brightness and a 92.8% screen-to-body ratio.
The combination provides the fluid scrolling and vibrant presentation expected from a contemporary AMOLED smartphone, while complementing a device otherwise heavily focused on practical considerations.
Warranty coverage also extends across the GCC, Pakistan, India and Bangladesh, potentially useful for users who regularly travel between these markets.
The 8,000mAh battery will inevitably attract most of the initial attention, but the A7 Pro 5G becomes more interesting when viewed as a complete package. OPPO is combining battery capacity with physical durability, thermal management, connectivity enhancements and longer-term performance optimisation. At the same time, it has avoided turning the device into something that visually resembles a specialist rugged phone.
BY: SRIJITH KN
A different definition of smartphone performance that may ultimately be the A7 Pro 5G’s more relevant proposition. Rather than asking how much faster a smartphone can become every year, OPPO is increasingly asking another question: how much longer can it remain useful?
Nearly every enterprise believes its AI agents are properly scoped. Only a third have actually made sure of it.
Today, new research from Cequence Security, the leader in application, API, and agentic AI protection, and Enterprise Management Associates (EMA) found that 94% of enterprise IT and security leaders are confident their AI agents do not have more access than they need, yet only 33% actually provision agents with least-privilege access. The remaining two-thirds run on broad standing permissions that are reviewed periodically, rarely reviewed, or never reviewed at all.
That gap between confidence and practice is already showing up in production, not a theoretical risk, but as incidents enterprises are living with right now. Among the organizations surveyed:
65% have experienced an AI agent take an action outside its intended scope, including 29% with measurable business impact, including data exposure, financial loss, operational disruption, or reputational damage. Another 36% caught a near-miss before it caused damage.
Only 32% can detect and contain an out-of-scope agent action within minutes through automated means; 55% need hours and manual steps to respond.
In approximately 4% of organizations surveyed, the first sign of trouble came from a customer or outside partner, not an internal system.
The findings point to one clear story. Governance has not kept pace with the speed of agentic AI deployment, and that gap is showing up at every stage of the agent lifecycle, from how agents are provisioned, to how their actions are authorized, to how they are decommissioned once a pilot ends. Other key findings from the report include:
Enterprises Have Moved Past the Pilot Stage
The scale of deployment makes the gap more urgent. 46% of organizations report they are already scaling agentic AI across multiple departments and production workflows, and 79% are running generative and agentic AI simultaneously. Further, more than 92% report an increase in AI and bot-driven traffic targeting customer-facing applications and APIs.
Authorization is Checked at the Wrong Time, Or Not At All
That governance gap extends to how access is enforced in the moment an agent acts. Only 34% of organizations evaluate an AI agent’s authorization at the moment it attempts a specific action. The majority rely on periodic policy reviews or standing permissions set once at provisioning and never revisited, meaning an agent’s access can quietly outlive the task it was originally granted for, and keep working long after anyone signed off on it.
Abandoned Pilots Are Leaving Live Credentials Behind
Additionally, there’s an increasing risk in how enterprises manage agents that don’t make it to production. 31% of agentic AI pilots have been paused indefinitely, discontinued, or abandoned. Many were real deployments with real system access and credentials that were never cleaned up. Every abandoned pilot with live credentials is exposure nobody is actively watching.
External Connectivity Carries the Same Risk
14% of organizations allow AI agents to connect to outside tools and data sources via the Model Context Protocol (MCP) without restriction. Among the majority who do limit those connections to an approved list, fewer than half, just 49%, have a dedicated team actively maintaining and auditing that list on a regular basis.
Christopher M. Steffen, CISSP, CISA, VP of Research at EMA, said: “This research shows enterprises have moved well past experimentation with agentic AI right into production, and governance has not kept pace with that shift. The gap isn’t a lack of awareness; most organizations have policies in place and express real confidence in them. The gap is between what’s written down and what’s enforced when an agent takes an action nobody approved. That disconnect shows up most clearly in how organizations authorize agent actions and monitor them once they’re live, and it’s the reason incidents are happening at a rate the industry hasn’t fully reckoned with.”
Shreyans Mehta, Co-founder and CTO at Cequence, said: “The number that jumped out to me is the 92% being confident in their governance frameworks. Confidence like that is a trap; it’s exactly why organizations stop looking for problems, stop investing in monitoring, and let authorization checks lapse until an incident forces the conversation. This is the exact blind spot Cequence is built to close, giving security teams real-time visibility into what AI agents are actually doing and enforcing authorization at the moment an agent acts, not after the fact.”
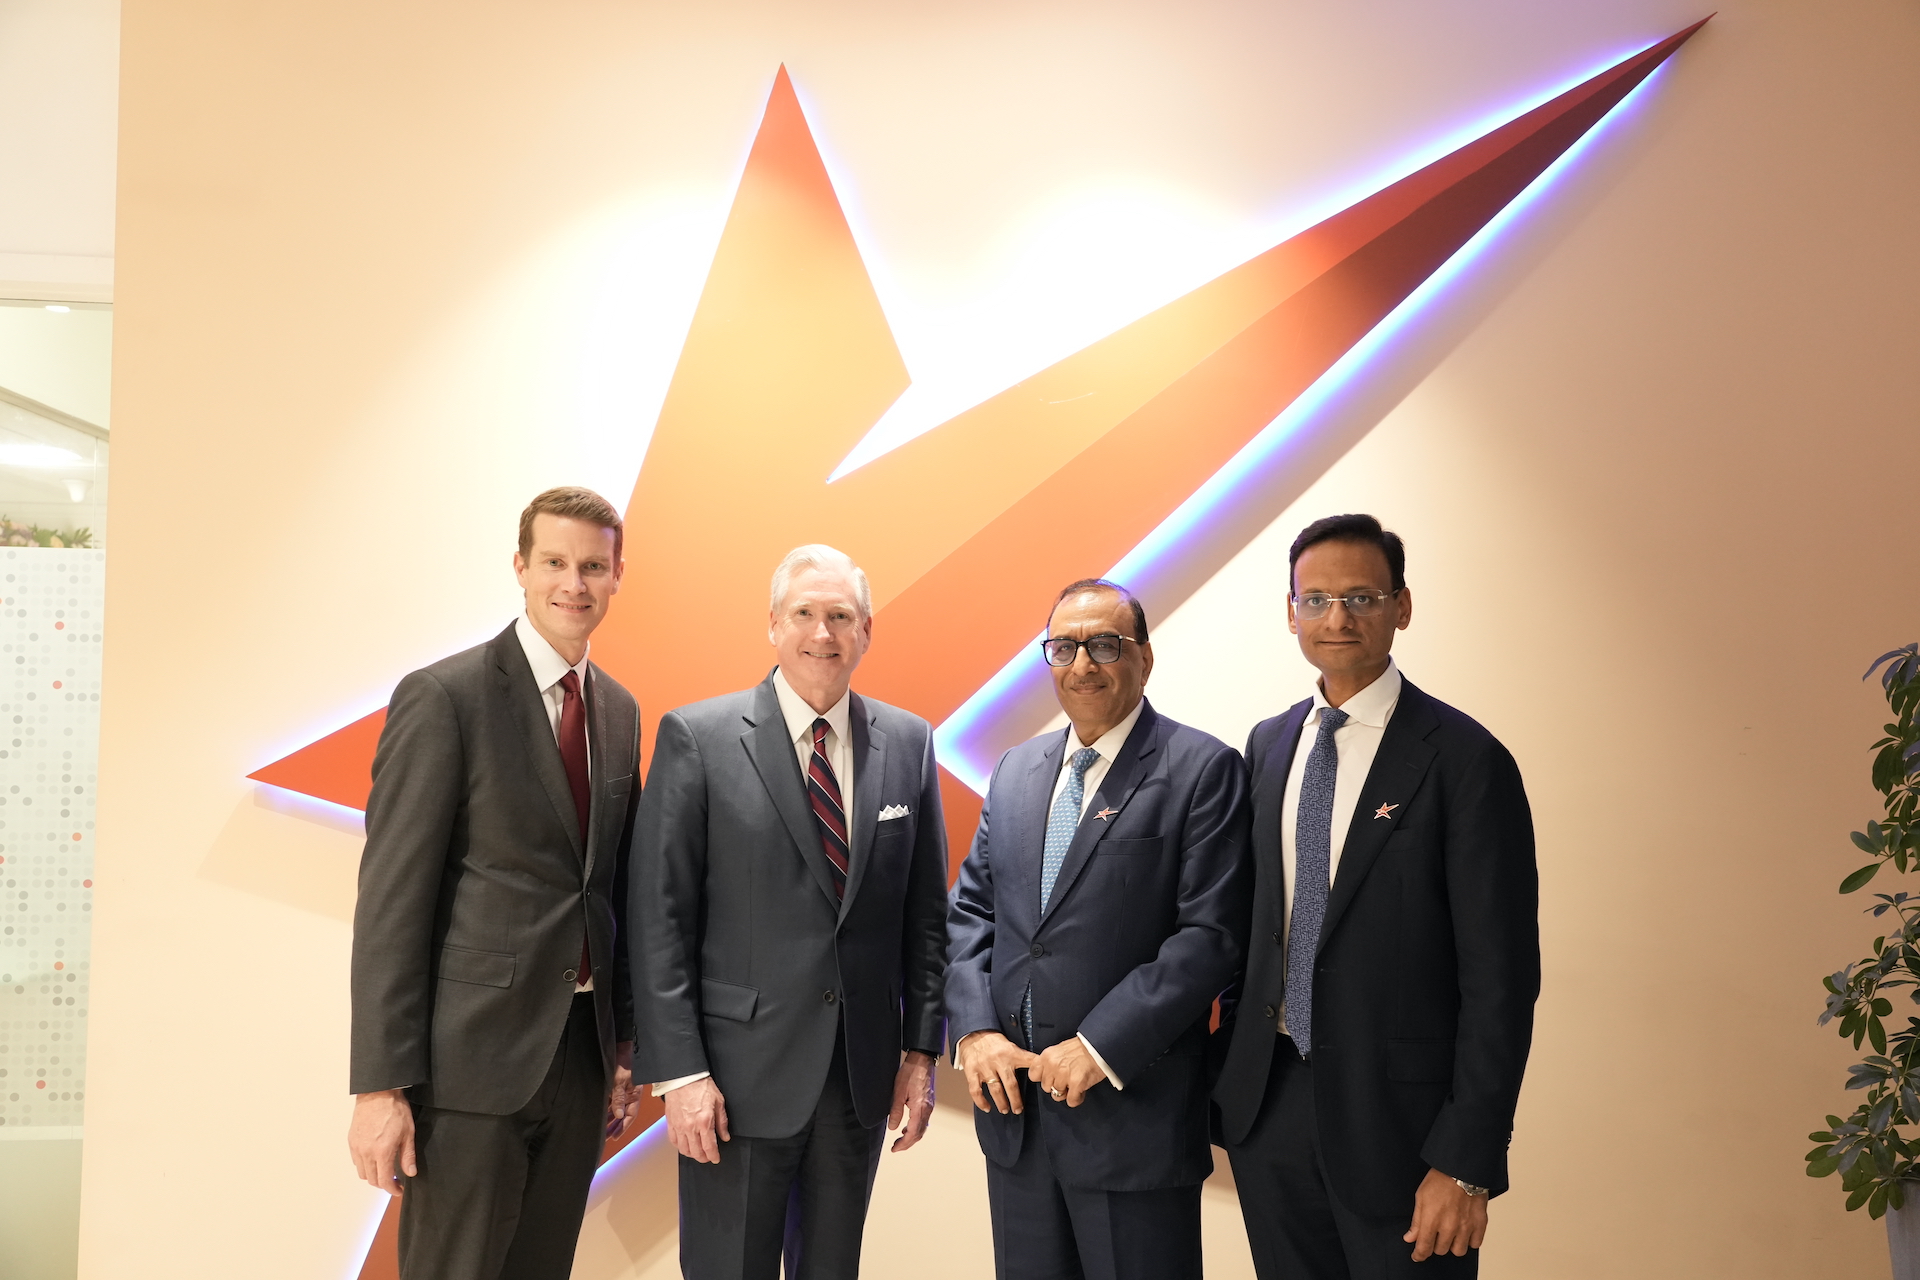
Dhruva will adopt the Ryan brand across the UAE and Saudi Arabia by the end of 2026, uniting the practice with Ryan’s global identity and international platform.
Dhruva, a leading tax consultancy firm in the Middle East, and Ryan, a leading global tax services and software provider, today announced that Dhruva will transition to the Ryan brand across the United Arab Emirates (UAE) and the Kingdom of Saudi Arabia. The rebranding will be completed by the end of 2026, bringing the practice under Ryan’s global identity and reinforcing its position as part of the world’s leading global-scale specialist in business tax.
The transition marks the next phase of the strategic joint venture announced in 2025 and reflects the continued integration of Dhruva’s regional capabilities with Ryan’s global platform, technology, and international resources. Clients across the Middle East will continue to benefit from the same trusted advisory teams, enhanced by access to Ryan’s worldwide expertise and service capabilities.
“The Middle East has been a strategic growth market for us for many years, and we have built a strong advisory practice founded on deep client relationships, technical excellence, and local market understanding,” said Dinesh Kanabar, Founder, Chairman, and CEO, Dhruva Advisors and Vice Chairman, Ryan.
“The transition to the Ryan brand marks a significant milestone in our journey and reflects the strength of our partnership. By combining our regional expertise with Ryan’s global scale, technology, and international capabilities, we are creating an even stronger platform to support clients across the region as they navigate an increasingly dynamic and evolving tax landscape.”
“The Middle East is one of the most important growth markets for tax advisory services globally, and we are investing in the region with a long-term view,” said Tom Shave, President of Ryan’s European and Asia-Pacific Operations. “Uniting under the Ryan brand strengthens how we serve clients across the UAE, Saudi Arabia, and Europe—bringing seamless access to our global expertise, technology, and international resources through one trusted platform. This transition marks an important milestone in our integration and reinforces our commitment to the region’s future.”
Ryan will continue to invest in its Middle East operations, expanding its team, capabilities, and regional presence across key markets, including Dubai, Abu Dhabi, and Riyadh. The practice provides comprehensive tax advisory services spanning corporate tax, value-added tax (VAT) and indirect tax, transfer pricing, mergers and acquisitions (M&A) tax structuring, research and development (R&D), and cross-border compliance.
“The response from our clients over the past year has been the clearest validation of this partnership,” said Nimish Goel, Leader, Middle East, Dhruva, a Ryan Affiliate. “From the outset, our teams have been integrating Ryan’s global capabilities in technology, specialized expertise, and best practices into the work we already lead in the region. Adopting the Ryan brand is the natural next step. It is the same people and the same trusted relationships, now carrying the name of the largest Firm in the world dedicated exclusively to business taxes.”
The rebranding will be implemented in phases during the second half of 2026, with signage, visual identity, and digital properties transitioning to the Ryan brand across the region.
What could follow the December deadline is an assessment cycle, not a filing cycle.
By Manish Bansal, Associate Partner, Dhruva Advisors, A Ryan Affiliate, Saudi Arabia
For most of the past five years, inter-alia, one of the major topics of tax conversation in Saudi boardrooms has been e-invoicing. Are we on the Fatoora platform? Which wave are we in? Has the ERP been configured or do we go with a third-party e-invoicing solution? Will we make the deadline?
Those were the right questions for the period we have just left. They are not necessarily the right questions for the period we are entering.
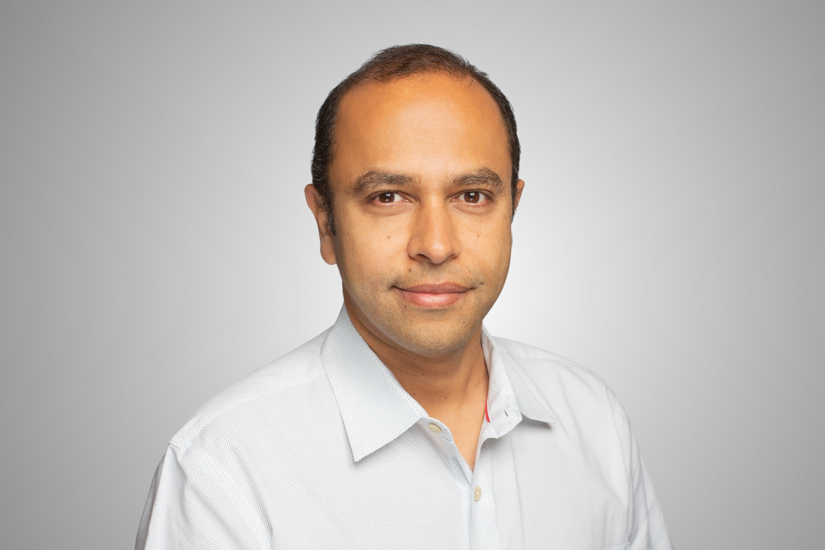
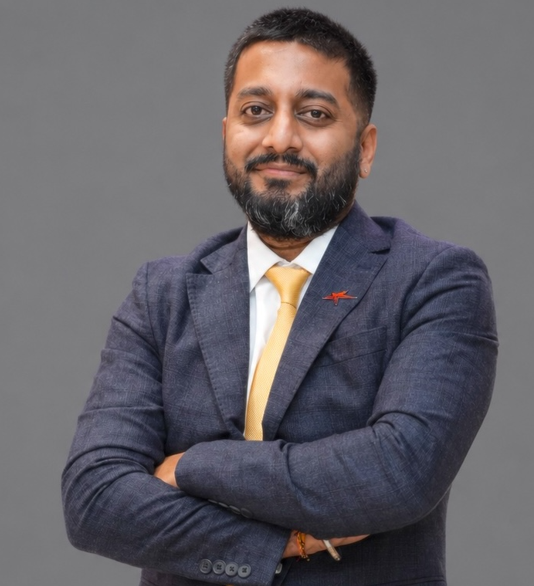
Manish Bansal
On 29 June 2026, the Zakat, Tax and Customs Authority (“ZATCA”), acting on a decision of the Minister of Finance, extended the Cancellation of Fines and Exemption of Financial Penalties initiative for a further six months, running from 1 July to 31 December 2026. It covers excise tax, value added tax, real estate transaction tax, withholding tax and corporate income tax. That much has been widely reported.
Less widely noticed is a condition set out in the accompanying guideline. If the Authority extends the initiative again past December, that further extension will not reach returns that fell due after 30 June 2026.
The Authority has not simply granted more time. It has informed the market, in advance, where the relief eventually stops. Whatever is announced in December, the clean-up window for historical positions is being drawn shut. For a tax administration, that is about as clear a statement as one can give.
What the regulator already sees
The reason this matters now, rather than in some indeterminate future, is that the Authority’s information position has changed fundamentally.
Wave 24 of the e-invoicing Integration Phase closed on 30 June 2026. Announced in September 2025, it captured every taxpayer whose VAT-subject revenues exceeded SAR 375,000 in 2022, 2023 or 2024. That figure is not arbitrary: it is the mandatory VAT registration threshold. In effect, the wave brought the entire registered population into scope.
And the direction has not stopped there. On 24 July 2026 – ZATCA published the criteria for Wave 25, halving the threshold to SAR 187,500 of VAT-subject revenue in 2022, 2023, 2024 or 2025, with integration required by 1 February 2027.
Under the Integration Phase, standard business-to-business invoices are cleared by ZATCA before they reach the buyer, and simplified business-to-consumer invoices are reported within twenty-four hours. Invoices must be issued in a prescribed structured format, carrying a cryptographic stamp and a unique identifier.
The Authority is therefore no longer reliant on what appears in a filed return. It holds the underlying transactional record, in structured form, close to real time, across the whole economy.
This is the shift most finance functions have not yet absorbed. For years, the Saudi assessment process began with an information request. In an environment of structured, near-live data, it begins instead with an anomaly the system has already identified. The taxpayer’s first substantive contact with the process is not a request for documents. It is a proposition to be answered.
Key exposure areas to be mindful of
In our experience, the following key areas could be more visible and exposed to assessment risk in the Kingdom once transactional data can be cross matched against declarations.
The first is permanent establishment risk arising from project delivery. Groups routinely deploy technical staff, secondees and subcontracted specialists into Saudi projects while treating the arrangement as an offshore supply. Given that most KSA government portals are inter-linked, careful monitoring of in-Kingdom presence is critical, in particular, employees of non-resident companies undertaking fly-in/fly-out assignments in the Kingdom. It is worth noting that the current tax law has no de minimis threshold for the creation of a permanent establishment. Accordingly, even a single day of presence in the Kingdom could potentially give rise to a permanent establishment, although in practice, the ZATCA may apply a more facts-based approach when assessing whether a permanent establishment exists.
Second is related-party pricing, and here a change that took effect two years ago is still under-appreciated. Following amendments to the Transfer Pricing By-Laws, the transfer pricing provisions apply to zakat payers as well as taxpayers for financial years beginning on or after 1 January 2024, and Advance Pricing Agreements became available to both. For a Saudi family group with decades of intercompany arrangements built for operational convenience rather than for documentation, this is a material change in obligation, and one that many such groups have not yet worked through.
Lastly, needless to state that VAT audits are likely to get much more sophisticated with real time data and the data analytics and AI tools available.
What the amnesty covers, and what it does not
Many companies are counting on this window. It is worth being precise about what it covers.
The initiative covers late registration, late payment and late filing fines, penalties on the amendment or correction of a VAT return, and other financial fines imposed under Article 45 of the VAT Law, including field detection and e-invoicing violations. To benefit, a taxpayer must register where registration is required, submit the outstanding returns, and either pay the amounts due or obtain ZATCA’s approval for an instalment plan.
Two limits deserve emphasis. The initiative does not extend to penalties relating to tax evasion violations. And it operates on fines for returns falling due up to 30 June 2026.
There is also a point that no guideline states because it does not need to. The initiative waives penalties. It does not validate a technical position. A voluntary disclosure that corrects an arithmetic omission is a straightforward matter. A voluntary disclosure that reveals a contestable tax treatment is a different exercise entirely, because it puts a position on the record that will be read. The analysis must come before the filing, not after it.
Fewer than four months
For most groups, what remains to be done before 31 December is a short list. It is also, notably, not a systems exercise. The e-invoicing platforms are already built and connected. The work now is reviewing the positions those systems have been reporting all along.
Reconcile first. Take VAT/ Tax/ Zakat returns, customs declarations, withholding tax filings and audited financial statements for the open years and reconcile them against one another before ZATCA’s systems do it. Where the numbers do not tie, understand why, and document the reason contemporaneously rather than reconstructing it under assessment.
Then sort. Separate the genuine errors, which the current window is designed to resolve, from the judgement positions, which need to be assessed on their merits and defended with evidence that pre-dates the query.
Finally, treat documentation as a deliverable with a deadline. Substantiation assembled after an assessment notice arrives carries markedly less weight than substantiation prepared when the transaction occurred.
A regulator that publishes wave criteria six months ahead, that notifies taxpayers directly, that issues guidance with worked examples, and that tells the market in advance where relief will end, is behaving like the administration of a mature investment destination. That predictability is an asset for serious businesses, and it is what long-term capital looks for.
But predictability runs in both directions. The Kingdom has been clear about what it expects and when. The businesses that will move through the coming assessment cycle with least disruption are those that use the next few months to answer the questions before they are asked.
Disclaimer: This article is intended for general information only and does not constitute tax, legal, accounting or other professional advice. It reflects the tax rules in force as of the publication date, and the described regulatory landscape continues to develop. Readers should obtain professional advice appropriate to their own facts and circumstances before acting on any matter discussed.
 Have a question? +971 56 404 0503







 Trending11 months ago

 Tech News2 years ago

 Automotive2 years ago

 Tech News1 year ago