 Have a question? +971 56 404 0503

Financial News
Empowering UAE’s Women to Achieve Financial Literacy and Inclusion

By Akshay Sardana, VP – Strategy & International Development, The Continental Group
Many studies over the years have established financial literacy as a determinant of socioeconomic conditions. Multi-generational financial literacy and planning have propelled many toward the upper echelons of the world. In contrast, the lack thereof continues to constrain several others in vicious cycles of debts, inevitable dependencies, and monetary uncertainties. As often as not, in the absence of financial literacy, women get the short end of the stick because of certain entrenched gender inequalities and other distinct factors. That explains the UAE’s growing efforts to advance women’s financial literacy. Over the recent months, many apex bodies have orchestrated financial literacy campaigns aimed at empowering women. The Dubai Government-owned National Bonds(1) has been at the forefront of such initiatives, recently partnering with the Arab Women Authority for a program to empower women with financial skills and tools. Such top-down efforts are timely and consequential in light of increasing complexities in financial markets, volatile economic cycles, and the indomitable need for gender equality across all walks of life. Evidence indicates that closing the financial-literacy gaps between men and women could have macroeconomic implications for a nation. The impact corresponds to the timeless quote, “if you empower a woman, you empower a nation.”
The following are the five probable positive outcomes.
Savings for a rainy day
In recent years, especially following the pandemic and subsequent inflationary cycles, people are increasingly provisioning for all possible contingencies. Increased online self-learning platforms and educational videos related to finance can be linked to that spike in interest and intent. Women have expanded their financial horizons, venturing beyond household accounts. Their primary objective is to build a corpus fund — a considerable amount of money kept aside for unforeseen emergencies — whose necessity continues to mount due to concerns of a recession. While the scope for growth is limited in emergency funds, the liquidity they offer can be useful. The ability of people to fend for themselves during large-scale, unprecedented situations is a hallmark of a competitive economy.
Decoupling from dependencies
A study found that, on average, women in the UAE retire with just 69% of the wealth of their male counterparts. Such abject wage disparities can be addressed only through structural changes in the corporate culture. Until then, women must continue to explore ways to secure their long-term financial interests without factoring in spousal or familial support. Decoupling from dependencies is important because women tend to live longer than men, requiring them to hone their financial skills for times ahead. However, savings alone will not suffice. With higher financial literacy, women can effectively plan their retirement by achieving risk-adjusted returns through strategic allocations of specific capital into savings, fixed-income products, equities, and insurance.
Inculcating financial discipline
A few cross-sectional surveys seeking to demystify parental roles in money habits have found that children mostly take after their mothers’ approaches to finance. Such findings place a significant onus on women to enhance their financial literacy. When financial discipline is inculcated early on, the strong foundations will define children’s monetary decision-making and related success. Besides money, women’s financial literacy sets good precedents for children to uphold the virtues of gender equality and the importance of patience and pragmatism in investments. No amount of money can parallel a legacy of financial discipline that mothers can bestow on their progeny.
Dodging curveballs
While there is no denying that women’s societal challenges have witnessed considerable legal recourse in recent years, it’s a long road before one can afford to be complacent. As often as not, women cannot break free from abusive marriages or families due to financial dependencies. In hindsight, about 59% of widows and divorcees wished they had been more involved in long-term financial decisions(3). At times, even seemingly natural circumstances such as childrearing can take their toll on a woman’s finances through career setbacks, etc. Financial literacy will ensure different employment pathways and promise a way out when marital circumstances become untenable.
Market Participation
Wealth creation stagnates when money is restricted to low-risk products such as savings accounts, fixed deposits, bullion, and provident funds. Statistics suggest that women tend to favour such asset classes due to a deep-seated aversion to risk — a by-product of less financial literacy. Some studies also suggest that women often edge out their male peers when participating in equity markets. The reasoning is that women are innately more pragmatic and grounded, which creates successful investors when coupled with high financial literacy. So, UAE policymakers hope to unlock an untapped segment in the financial market by supporting women’s financial education. It’s a righteous pursuit primed for long-term rewards.
Financial
PATRIZIA appoints Hassan Awada as Senior Executive Officer to lead and accelerate Middle East expansion

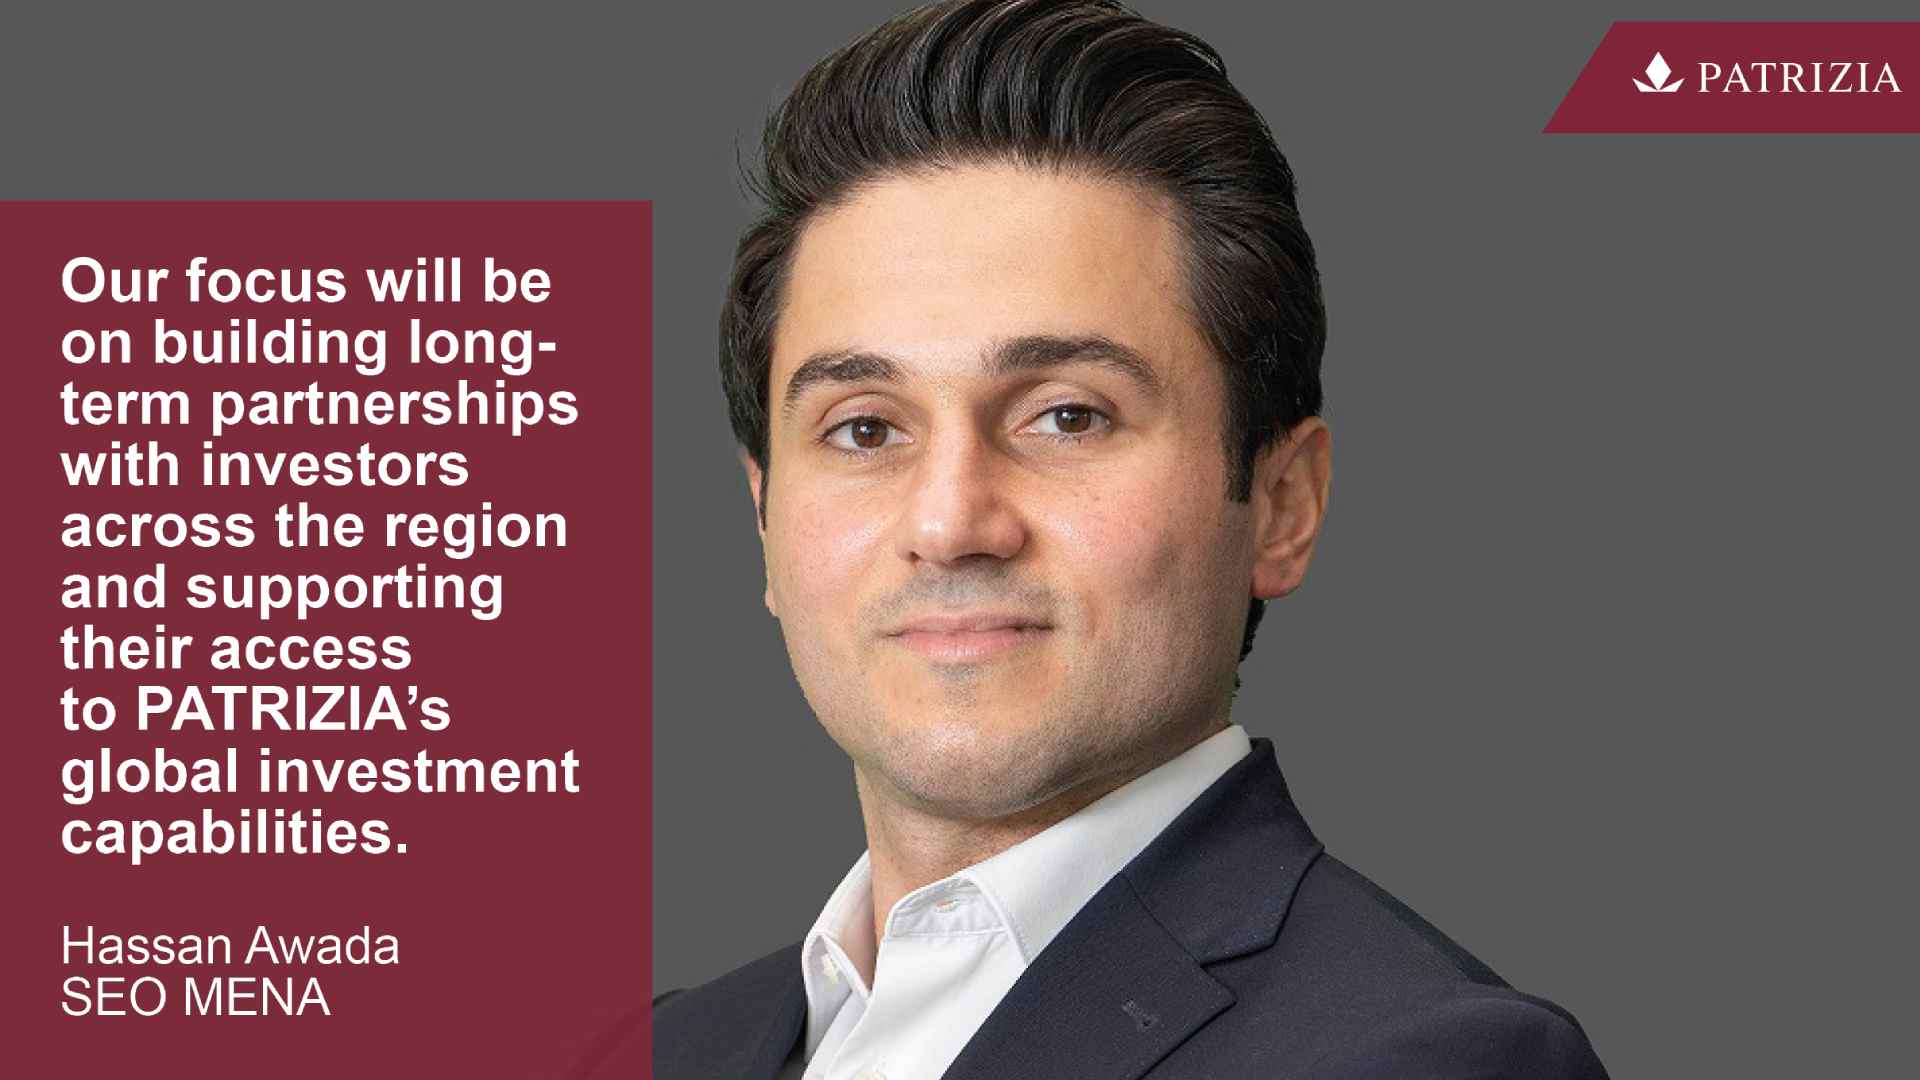
PATRIZIA, a global investment manager in real assets, has announced the appointment Hassan Awada as Senior Executive Officer (SEO), MENA. Based in ADGM, the international financial centre of the UAE’s capital, Abu Dhabi, Awada will lead the continued growth of PATRIZIA’s business across the MENA region, with a focus on deepening relationships with institutional investors and strategic partners and providing access to PATRIZIA’s international real assets investment platform.
Awada brings over 20 years of experience advising institutional investors across the full investment lifecycle, including origination, structuring, execution and asset management. Prior to joining PATRIZIA, he held senior roles at Kroll, Cornerstone Capital, Gleacher Shacklock, PwC and EY.
Konrad Finkenzeller, Head of Client Division at PATRIZIA, commented: “The Middle East is a key strategic region for PATRIZIA, and we continue to see strong demand from investors for direct exposure to high-quality real estate and infrastructure opportunities globally. Hassan’s appointment strengthens our presence on the ground and enhances our ability to deepen relationships with regional investors and connect them with PATRIZIA’s global investment platform.”
Hassan Awada, SEO MENA at PATRIZIA, added: “Real assets have long underpinned Middle Eastern economies and will continue to play a central role in the region’s growth. Meeting increasingly sophisticated investor needs requires tailored, strategic solutions. With its global platform and 42-year track record, PATRIZIA is well positioned to deliver. Our focus will be on building long-term partnerships with investors across the region and supporting their access to PATRIZIA’s global investment capabilities, aligned with their strategic priorities and long-term objectives.”
Arvind Ramamurthy, Chief Market Development Officer, ADGM, said: “This appointment reflects the firm’s strong growth trajectory in the Middle East and its commitment to expanding from Abu Dhabi. It also underscores ADGM’s role as a leading international financial centre, enabling firms to establish and scale their regional presence from the capital.”
With EUR 17.5 billion in Living assets under management, PATRIZIA is one of Europe’s largest residential investment managers and continues to grow its platform across major urban markets. The firm is currently delivering new housing across a number of European markets, including Germany, UK & Ireland, Spain and Belgium, reflecting the scale of its European platform. Alongside Living, PATRIZIA is expanding its infrastructure platform across energy, digital and smart city assets, supporting the transition to low-carbon and connected economies while delivering long-term, resilient returns for investors.
Financial
Fimple adds five GCC financial institutions in first year, targets doubling regional customer base
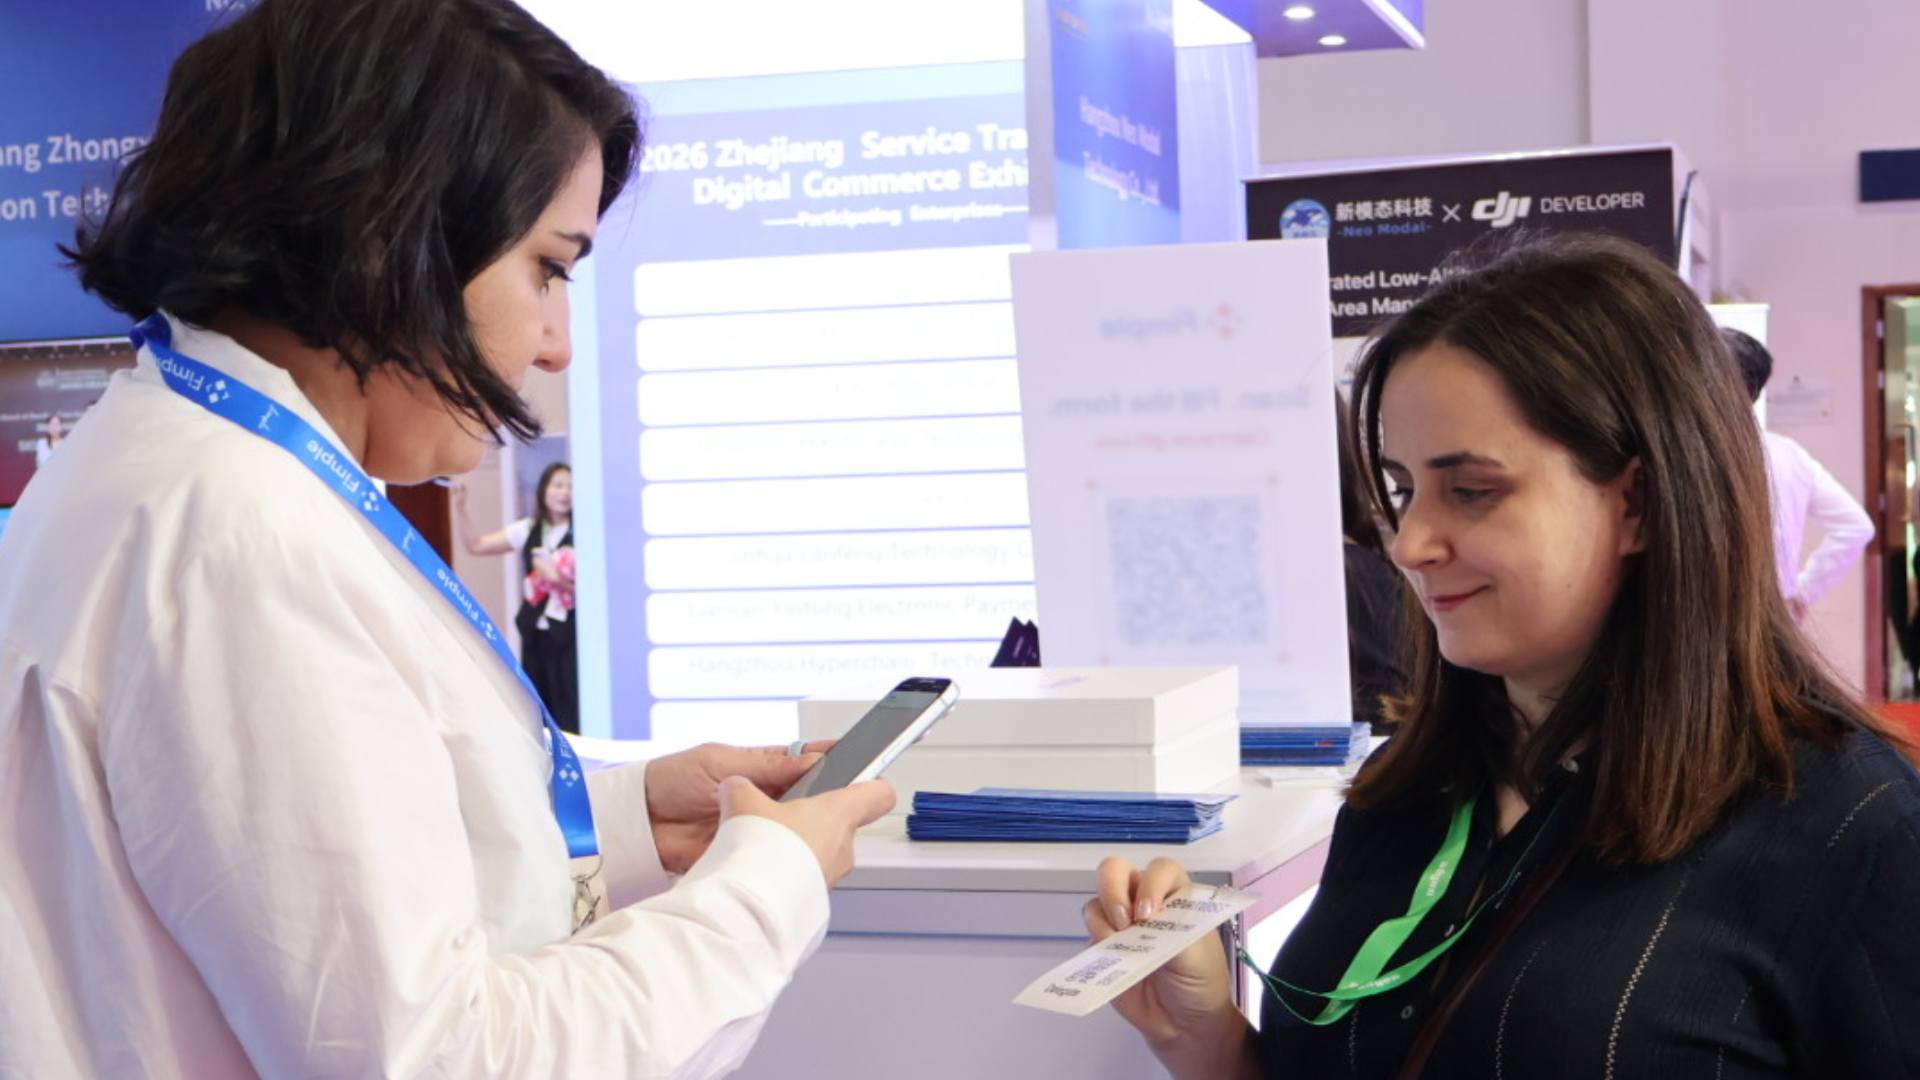
Fimple, an AI-native, API-first, composable financial platform, has signed five financial institutions across the GCC within its first year in the region and plans to double its regional customer base.
Fimple established its Dubai presence in October 2025 and has grown from zero to five GCC customers in 12 months. The region now accounts for close to a fifth of its global customer base of more than 35 financial institutions across 10 countries, making it the company’s fastest-growing region.
The company has also opened an office in Riyadh and plans to expand its customer and delivery presence across the GCC, serving institutions with teams based within the region.
Fimple’s regional growth comes as the UAE continues to advance its ambitions across Islamic finance and financial technology. Under the UAE Strategy for Islamic Finance and Halal Industry, the country aims to increase local Islamic bank assets from AED 986 billion to AED 2.56 trillion by 2031. (Source: UAECabinet.ae)
Dubai is also advancing its ambitions in AI-enabled financial services, with the Dubai International Financial Centre (DIFC) announcing plans in 2026 to become the world’s first AI-native financial centre. (Source: Dubai Media Office/DIFC)
“The UAE is an important market for Fimple because financial institutions here are moving quickly on both Islamic finance and new technology,” said Amr Kandel, GCC Country Manager and Product Director at Fimple. “Banks want to launch products faster, respond to local market needs and modernise without having to change everything at once. The growth we’ve seen in our first year shows there is real appetite for that.”
Islamic finance is a key driver of Fimple’s growth in the GCC. The platform enables financial institutions to run conventional and Islamic finance within the same system, with a range of Sharia-compliant financing and investment structures built into its product engine.
Fimple’s regional customers include Mawarid Finance, a UAE Islamic finance provider that entered into a strategic agreement with Fimple in June 2026.
As banks look to move AI from pilot projects into wider use, Fimple says the underlying core banking infrastructure is becoming increasingly important.
“Banks are already experimenting with AI, but the systems underneath need to be ready for it,” Kandel said. “If the core can’t provide the right data or connect easily with new technology, AI can get stuck at the pilot stage. That’s why the core matters.”
Fimple has built three banking AI agents covering independent audit report processing, customer intelligence from official notices and risk screening across official sources. The agents operate on the Fimple platform with human approval required for each action and full traceability. Further agents are planned as part of the company’s 2026–2027 roadmap.
According to Fimple, it implements a full working core in three to six months on average. Its composable architecture also enables financial institutions to connect selected modules to existing systems rather than replacing their entire core infrastructure at once.
“The GCC has become our fastest-growing region in just one year, and we expect to double our customer base here,” said Mücahit Gündebahar, CEO and Co-founder of Fimple. “We are growing our team and presence in the region so we can support customers locally as we expand across the GCC.”
Fimple will participate as a Gold Sponsor of Seamless Middle East 2026, taking place from Sept. 22–24 at Dubai World Trade Centre. The company will exhibit at stand G64, with Kandel delivering the session “Beyond the AI Hype: Why the Future of Banking Depends on an AI-Ready Core” on Sept. 23 at Stage 1, Fintech Forum.
Financial
Al Masraf and Moody’s Sign Strategic Agreement to Strengthen Risk Intelligence and Credit Capabilities
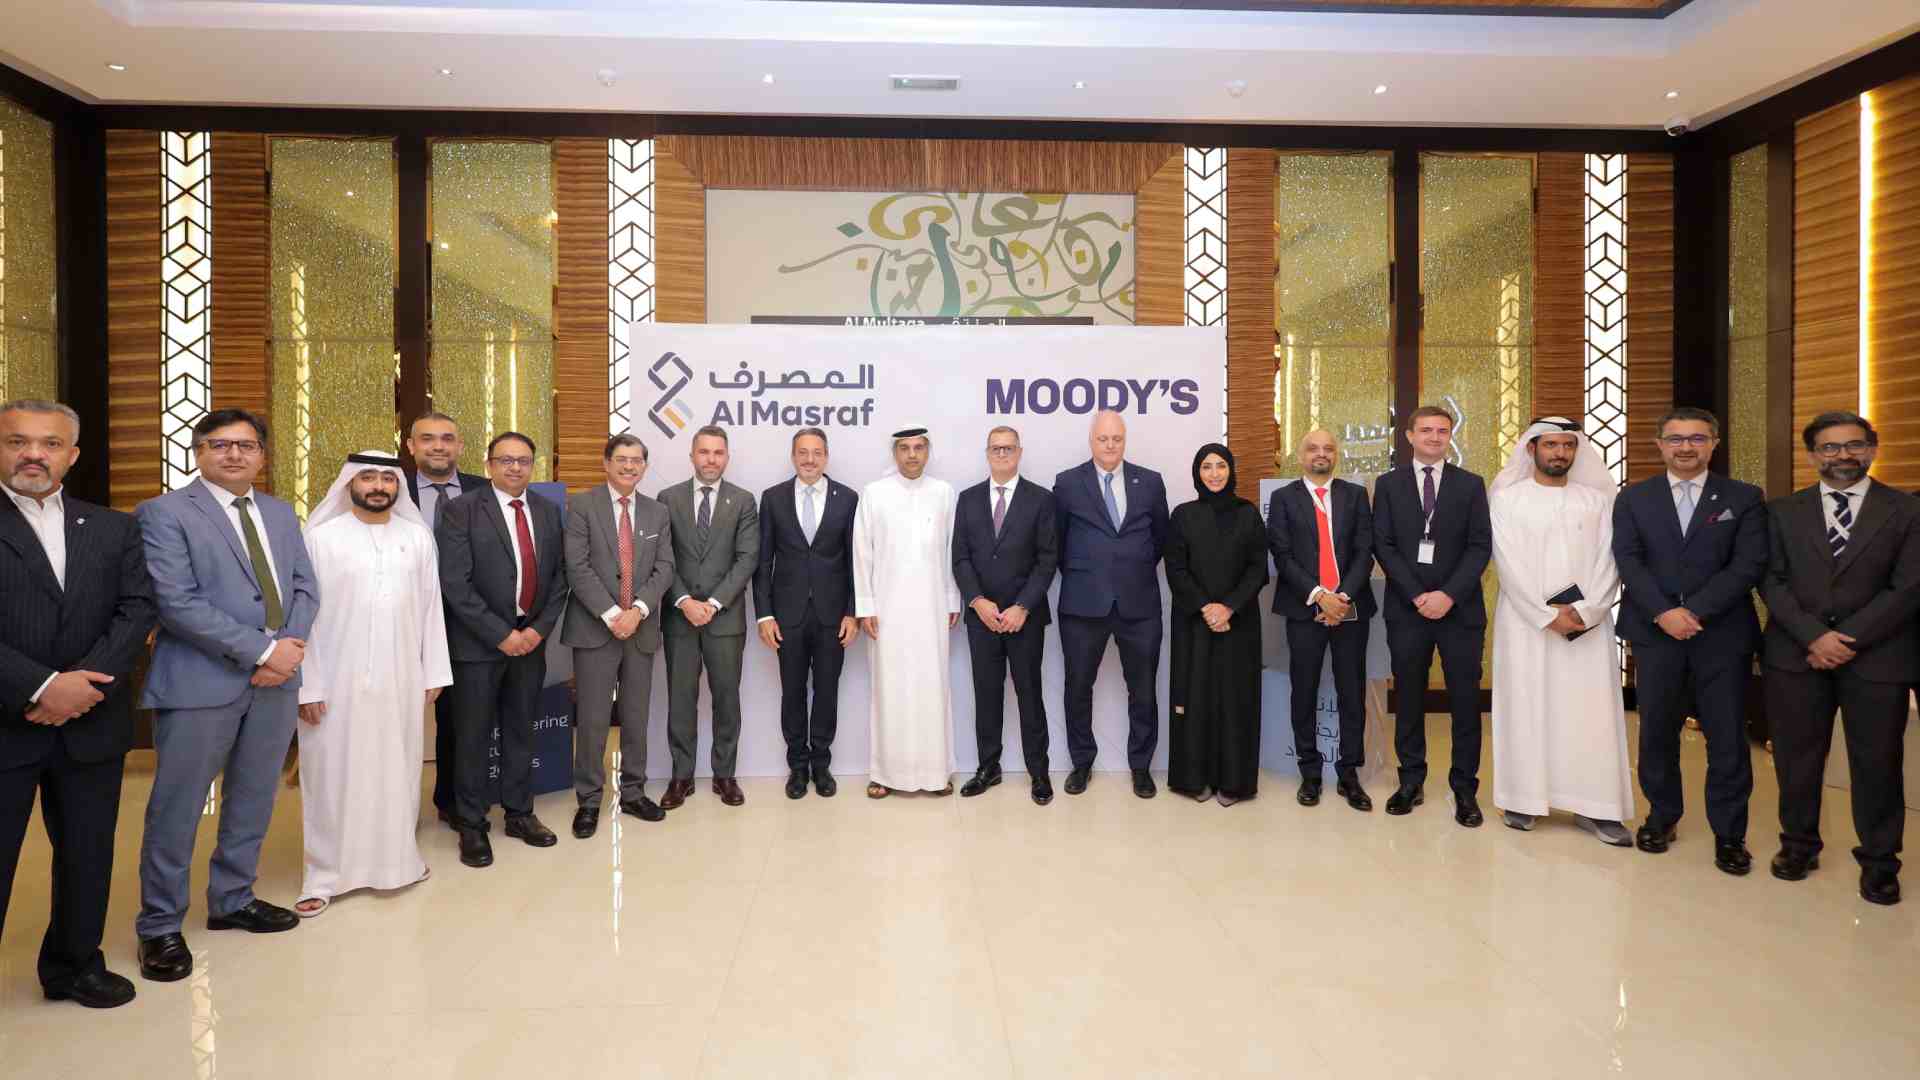
Al Masraf has signed a strategic agreement with Moody’s, a global provider of financial intelligence and risk assessment, marking an important step in strengthening the Bank’s risk management and credit capabilities through enhanced data, insights and technology.
The agreement was formalized during a signing ceremony held in Abu Dhabi, bringing together senior leadership from Al Masraf and Moody’s. The collaboration reflects both organizations’ commitment to leveraging advanced intelligence and risk expertise to support informed, data-driven decision-making in an increasingly complex financial environment.
As risks become increasingly interconnected and the financial landscape continues to evolve, access to timely, reliable and actionable intelligence is becoming essential for financial institutions. Through its combination of data, intelligence, risk expertise and technology, Moody’s helps organizations better understand interconnected risks.
The partnership will further support Al Masraf’s continued focus on strengthening its risk management framework, enhancing credit decision-making and building resilient, forward-looking capabilities that support sustainable growth.
Commenting on the occasion, Fuad Mohamed, CEO of Al Masraf, said: “At Al Masraf, we believe that sustainable growth is built on the strength of our ability to understand risk, anticipate change and make informed decisions. Our collaboration with Moody’s represents an important step in advancing our risk and credit capabilities through deeper intelligence, data and technology.”
He continued: “As the financial landscape continues to evolve, partnerships of this nature enable us to strengthen our resilience, enhance decision-making and create greater value for our customers and stakeholders. We look forward to building on this collaboration as we continue to shape a more agile, intelligent and future-ready Al Masraf.”
“We are delighted to partner with Al Masraf on an important step in modernizing its corporate lending operations. By bringing greater automation, efficiency, and insight to the credit journey, Moody’s is helping the bank build a future-ready operating model that enables faster, better-informed lending decisions, strengthens governance, and enhances risk management.” said Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East at Moody’s.
Senior representatives from both organizations attended the signing ceremony.
Representing Al Masraf were Fuad Mohamed, Chief Executive Officer; Moataz Khalil, Chief Wholesale Banking Officer; Safeya Almarzooqi, Chief Credit Officer; Mirel Baila, Acting Chief Operating Officer; Rohit Kumar, Chief Risk Officer; and senior representatives from the Bank’s Wholesale Banking, Credit, Risk, Information Technology, Islamic Banking, Corporate Banking, Project Management and Business Management functions.
Representing Moody’s were Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East; Brendan Gavaghan, Senior Director, Middle East; Raghavendra Katagade, Director, UAE; Blaine Connan, Director, UAE; Ali Abdullah, Director, UAE; and Anand Thirunellai Radhakrishnan, Senior Director, Middle East & Europe.
The agreement underscores Al Masraf’s commitment to continuous innovation and adopting advanced capabilities that strengthen its ability to navigate an evolving risk environment, while supporting the Bank’s broader ambition to deliver sustainable growth and enhanced value to its customers and stakeholders.
International Coffee Day Gets UAE-Made Twist with Rashtions’ Brazilian Coffee Truffle

Why Curation Matters More Than Ever in Fashion Retail

Keeta Marks First Anniversary in the UAE, Celebrating Nationwide Growth and Local Impact


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai