 Have a question? +971 56 404 0503

Financial
THE INFORMATION PARADOX IN MODERN MARKETS: WHY MORE DATA DEMANDS BETTER JUDGEMENT

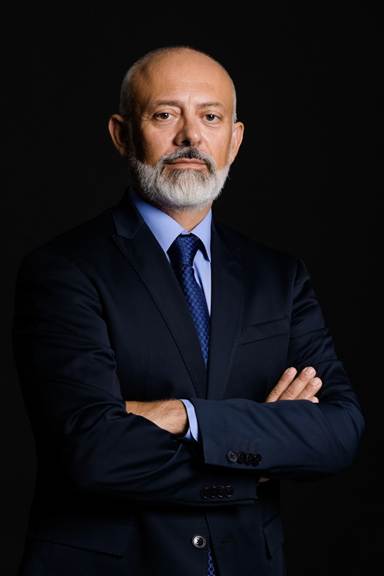
By Roberto d’Ambrosio – CEO at Axiory
Financial markets in 2026 are producing more information than at any point in history. Earnings data, geopolitical alerts, AI-generated analysis, social media commentary, and real-time price feeds reach investors continuously, relentlessly, and from every direction. The conventional assumption is that this abundance is empowering. More data, the argument goes, means better-informed decisions. From my experience across more than three decades in financial services, the reality is considerably more complicated, and for many investors, the opposite is closer to the truth.
Access to information is not the same as the capacity to process it. When data exceeds the ability of the individual to filter, interpret, and act on it with clarity, the result is not better decision-making. It is hesitation, reactive behaviour, and a false sense of confidence that having seen the data is the same as having understood it. Research published by the Board of Governors of the US Federal Reserve has confirmed what practitioners have long observed: information overload is associated with lower trading volumes and measurably higher risk premia, as investors demand greater compensation for holding assets in an environment where they can no longer reliably distinguish signal from noise. The effect is not marginal. It is structural, and it worsens precisely when markets are most volatile and when clear thinking matters most.
This is particularly relevant for the Middle East. The GCC’s retail investment sector has expanded rapidly, with neo brokerages and digital trading platforms now comprising a market valued at approximately $1.2 billion. The UAE’s regulatory framework, spanning the Securities and Commodities Authority, the Dubai Financial Services Authority, and the Financial Services Regulatory Authority, sets meaningful standards for disclosure and investor suitability. Yet the sheer volume of unfiltered data reaching individual investors through apps, alert systems, and AI-driven content is outpacing the governance infrastructure designed to protect them. Earlier this year, UAE-based retail platforms reported a sharp spike in commodity trading volumes following geopolitical alerts linked to regional energy infrastructure. The pattern was instructive: investors were not responding to analysis. They were reacting to the noise itself.
In my opinion, the real competitive advantage in today’s markets has shifted decisively. It is no longer about who has access to data, because everyone does. It is about who has the discipline, the frameworks, and the human capacity to determine what that data means and what it does not. This is fundamentally a risk management challenge, not a technology challenge.
Consider the consequence chain. When platforms deliver thousands of data points, alerts, and AI-generated recommendations without adequate curation, they create an illusion of informed participation. Investors who lack the training or advisory support to contextualise this information face two symmetrical risks: paralysis, where conflicting signals prevent any decision at all, and impulsive reaction, where a single alarming headline triggers an unexamined trade. Both degrade portfolio outcomes. Both increase transaction costs, erode returns through poorly timed decisions, and expose investors to risks they have not consciously chosen to take.
This raises an uncomfortable question for data providers and platform operators. The business model of much of the fintech and financial information industry is built on engagement, meaning more alerts, more content, more interaction. But engagement is not the same as service, and information delivery without responsibility for its quality, context, and potential impact on decision-making is not a neutral act. It carries consequences, and regulators are beginning to recognise this.
The European Union’s AI Act, whose high-risk obligations for financial services take effect in August 2026, will require providers of AI-driven systems used in credit scoring, risk profiling, and investment decision-making to meet strict standards around transparency, human oversight, and auditability. The EU’s proposed Financial Data Access regulation extends similar principles to data sharing across the financial sector. These frameworks signal a clear direction: those who provide financial data and algorithmically generated analysis will increasingly bear responsibility for how that information is presented, contextualised, and governed. For the GCC, where regulators have consistently demonstrated a commitment to adopting and adapting international best practice, the trajectory is evident. Data provision is moving toward becoming a compliance-intensive activity, and firms operating in or serving the region should prepare accordingly.
But regulation alone will not solve the information paradox. Compliance frameworks establish floors, not ceilings. The deeper challenge is cultural and organisational. Investors, whether institutional or individual, need not just data but the capacity to interpret it within a coherent risk framework. Before acting on any data point, alert, or algorithmically generated recommendation, the prudent investor asks three questions: what is the source, what context is missing, and does this information warrant action or merely attention? This discipline is not intuitive in a market designed to reward speed, but it is essential. It means investing in financial literacy, in advisory relationships grounded in trust and expertise, and in governance structures that ensure decisions are informed by judgement rather than driven by impulse.
Ultimately, this is a human capital challenge. Algorithms can process data at scale, but they cannot replace the informed professional who understands context, identifies what is missing from the data, and exercises the judgement to act, or equally important to refrain from acting, when conditions are uncertain. Organisations and platforms that invest in experienced risk professionals, in robust advisory capability, and in the governance to ensure quality over quantity will build durable competitive advantages. Those that continue to prioritise data volume over decision quality will find that the market eventually prices that negligence in.
In a market flooded with information, the scarcest resource is not data. It is the judgement to know what to do with it.
Financial
Al Masraf and Moody’s Sign Strategic Agreement to Strengthen Risk Intelligence and Credit Capabilities

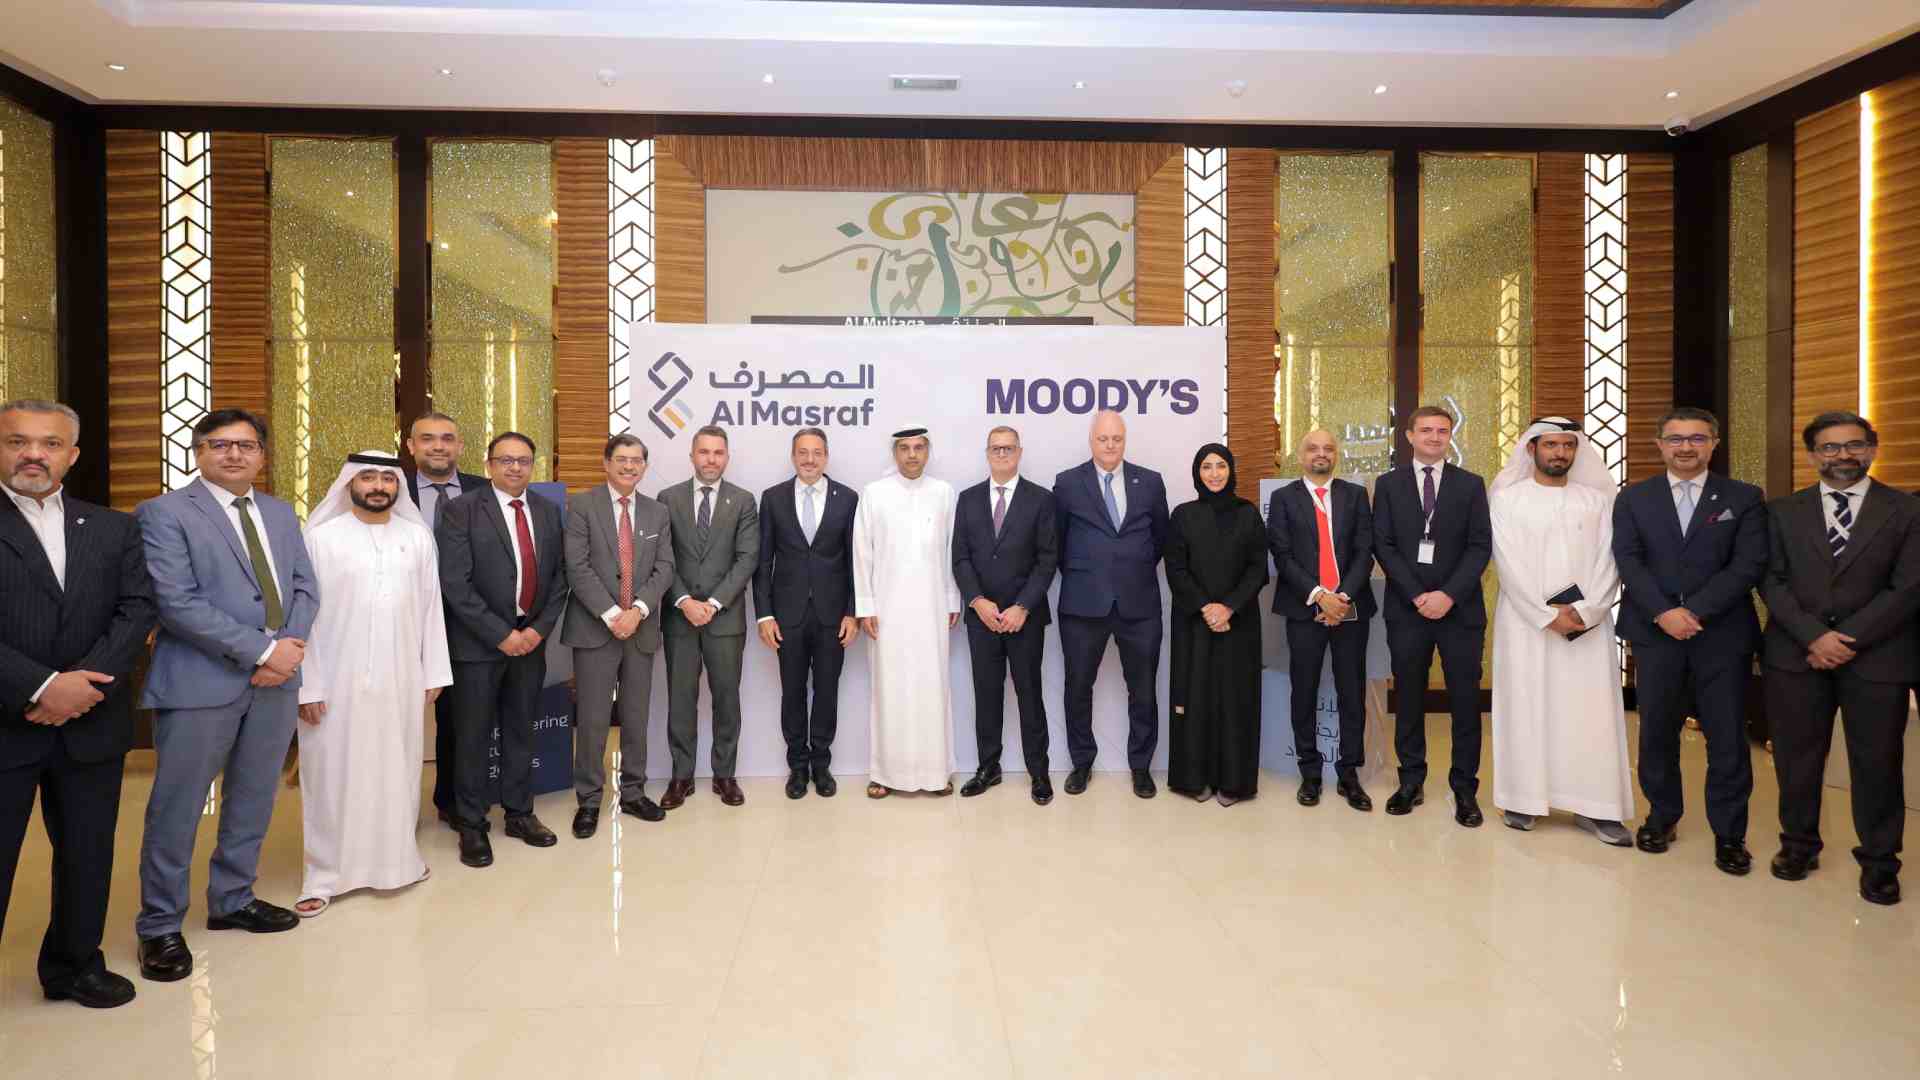
Al Masraf has signed a strategic agreement with Moody’s, a global provider of financial intelligence and risk assessment, marking an important step in strengthening the Bank’s risk management and credit capabilities through enhanced data, insights and technology.
The agreement was formalized during a signing ceremony held in Abu Dhabi, bringing together senior leadership from Al Masraf and Moody’s. The collaboration reflects both organizations’ commitment to leveraging advanced intelligence and risk expertise to support informed, data-driven decision-making in an increasingly complex financial environment.
As risks become increasingly interconnected and the financial landscape continues to evolve, access to timely, reliable and actionable intelligence is becoming essential for financial institutions. Through its combination of data, intelligence, risk expertise and technology, Moody’s helps organizations better understand interconnected risks.
The partnership will further support Al Masraf’s continued focus on strengthening its risk management framework, enhancing credit decision-making and building resilient, forward-looking capabilities that support sustainable growth.
Commenting on the occasion, Fuad Mohamed, CEO of Al Masraf, said: “At Al Masraf, we believe that sustainable growth is built on the strength of our ability to understand risk, anticipate change and make informed decisions. Our collaboration with Moody’s represents an important step in advancing our risk and credit capabilities through deeper intelligence, data and technology.”
He continued: “As the financial landscape continues to evolve, partnerships of this nature enable us to strengthen our resilience, enhance decision-making and create greater value for our customers and stakeholders. We look forward to building on this collaboration as we continue to shape a more agile, intelligent and future-ready Al Masraf.”
“We are delighted to partner with Al Masraf on an important step in modernizing its corporate lending operations. By bringing greater automation, efficiency, and insight to the credit journey, Moody’s is helping the bank build a future-ready operating model that enables faster, better-informed lending decisions, strengthens governance, and enhances risk management.” said Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East at Moody’s.
Senior representatives from both organizations attended the signing ceremony.
Representing Al Masraf were Fuad Mohamed, Chief Executive Officer; Moataz Khalil, Chief Wholesale Banking Officer; Safeya Almarzooqi, Chief Credit Officer; Mirel Baila, Acting Chief Operating Officer; Rohit Kumar, Chief Risk Officer; and senior representatives from the Bank’s Wholesale Banking, Credit, Risk, Information Technology, Islamic Banking, Corporate Banking, Project Management and Business Management functions.
Representing Moody’s were Wael Jadallah, Managing Director, Head of Asia Pacific and Middle East; Brendan Gavaghan, Senior Director, Middle East; Raghavendra Katagade, Director, UAE; Blaine Connan, Director, UAE; Ali Abdullah, Director, UAE; and Anand Thirunellai Radhakrishnan, Senior Director, Middle East & Europe.
The agreement underscores Al Masraf’s commitment to continuous innovation and adopting advanced capabilities that strengthen its ability to navigate an evolving risk environment, while supporting the Bank’s broader ambition to deliver sustainable growth and enhanced value to its customers and stakeholders.
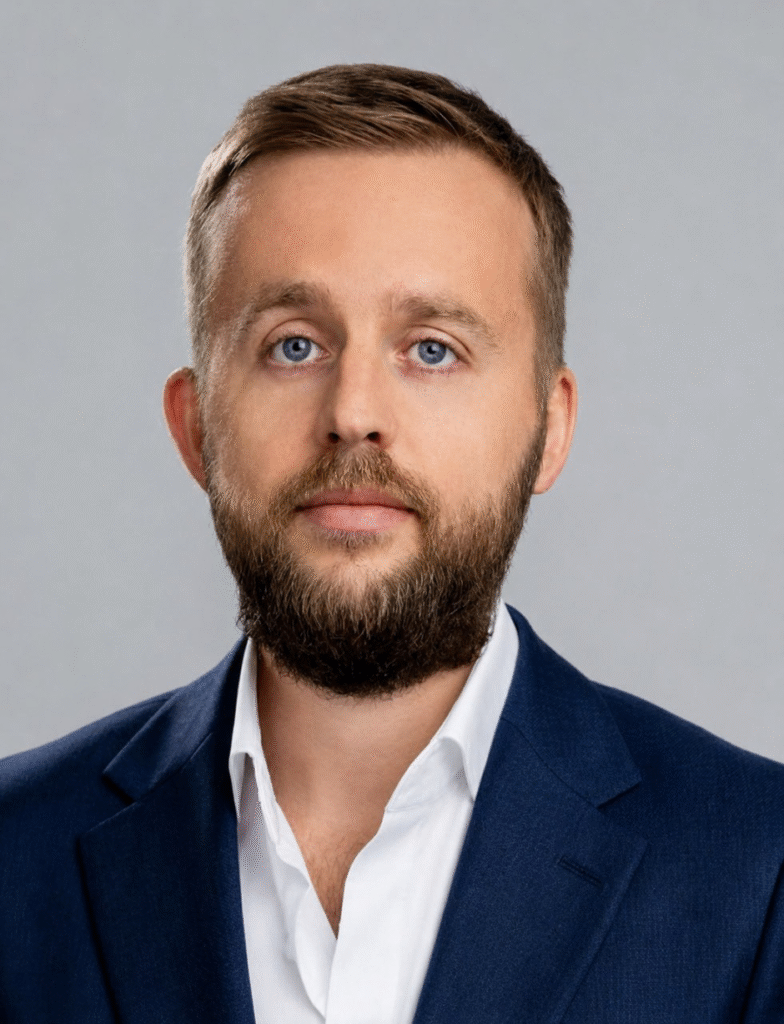
With the dirham pegged to the US dollar and UAE investors exposed to global markets, decisions made by the Federal Reserve and the US government can influence local borrowing costs, liquidity, and investment
sentiment. Michael Smirnow, Chief Investment Officer, Arabian Capital Gulf
After the global financial crisis, U.S. authorities tried to stimulate the economy primarily through monetary measures: the Federal Reserve cut interest rates to zero and launched quantitative easing (QE) for the first time, purchasing assets to provide market participants with liquidity. As a result, the Fed’s balance sheet grew to USD 8 trillion by 2021. However, between 2008 and 2020, the U.S. economy did
not experience rapid growth, and inflation regularly remained below the target level. Everything changed in 2020, when the government entered the stimulus fray for the first time in many years. While the Fed’s accommodative monetary policy primarily helped large banks and market participants, at the onset of
the pandemic the U.S. government began distributing money to households and increasing budget expenditure across nearly all areas. Compared with monetary measures, these fiscal stimulus measures proved to be a significantly more powerful tool for stimulating the economy; however, they increased
government debt by the aforementioned 61%. Against this backdrop, we expect the next few years to be shaped primarily by fiscal stimulus, with
government action, rather than the Federal Reserve, becoming the key factor for investors. Indeed, while the private sector ran large deficits before 2008, the deficit now lies with the government, while private-sector indebtedness is declining. In the years following the pandemic, the largest government deficits coincided with the strongest growth in financial markets. This is unsurprising, since a public-sector deficit becomes private-sector income. This dynamic enabled the U.S. economy to remain resilient in 2023-2024 despite the Fed’s record pace of interest-rate increases. Whichever U.S. political party is in power will continue along this path;
Trump is also doing the same through legislation known as the “Big Beautiful Bill.” As long as inflation in the United States remains under control, this race will continue.
The current balance between monetary and fiscal stimulus vividly illustrates this argument. On the one hand, the U.S. Federal Reserve is adopting an increasingly neutral stance and is clearly in no hurry to cut interest rates or introduce new stimulus programmes. On the other hand, the Treasury is entering the fray: as yields on long-term U.S. bonds confidently exceed 5%, the Treasury has launched a program to buy back its long-term debt. In effect, this gives the bond market the same kind of stimulus the Fed previously delivered.
Thus, the balance of power is changing, but the direction remains the same: the United States still needs accommodative monetary conditions. If these are not achieved through monetary measures, they will be achieved through fiscal ones.
(Arabian Gulf Capital (AGC) holds a Category-1 Investment Firm license issued by the Central Bank of Bahrain and provides tailored investment solutions to individual, corporate, and institutional clients.)
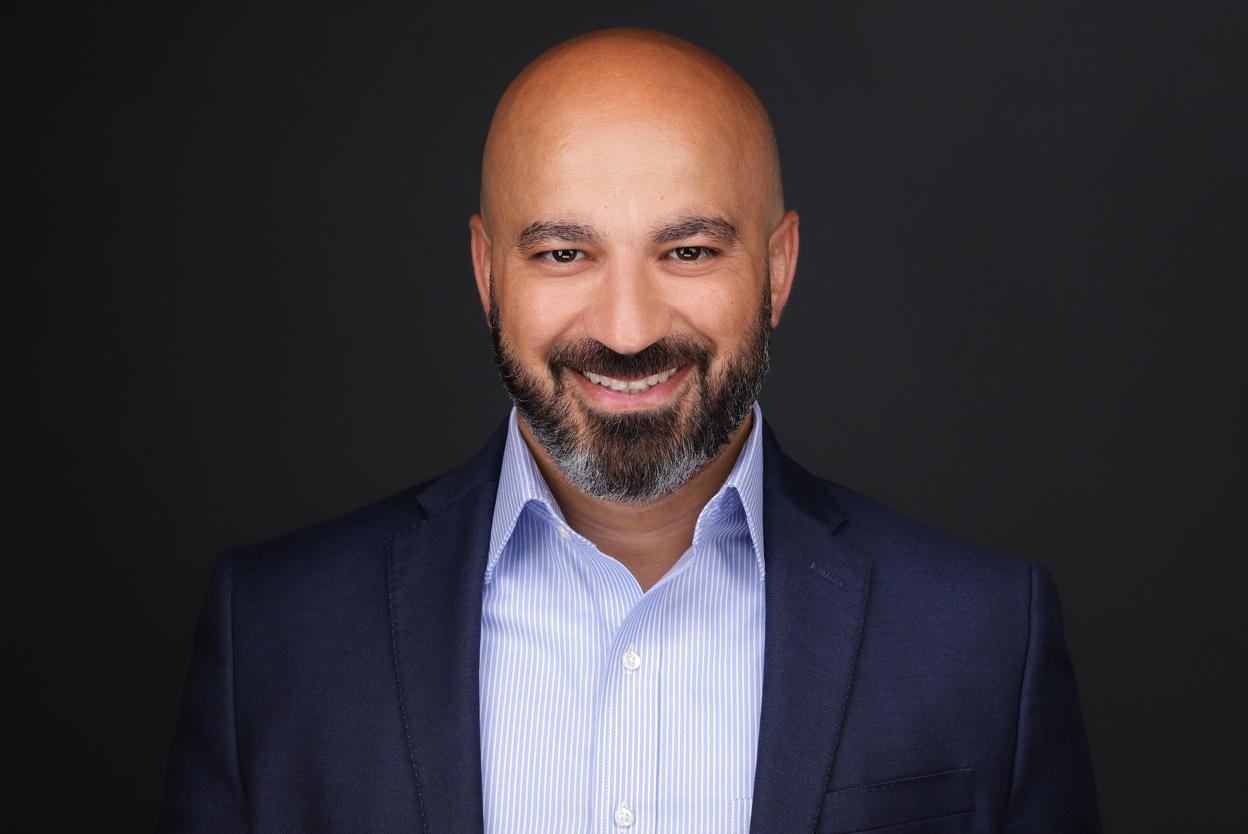
As GCC businesses expand into new markets and increasingly complex supply chains, traditional credit assessment is giving way to a more predictive approach. In this interview with Mohamad Jomaa, CEO and Country Manager for GCC and Egypt at Coface, we explore how real-time data, AI and early-warning intelligence are helping CFOs anticipate payment risk, protect working capital and make more confident decisions across customers, suppliers and markets.
What is driving the shift from relationship-based credit decisions to predictive credit intelligence among CFOs in the GCC?
Relationships remain fundamental to business in the GCC and will continue to be. What has changed is the speed at which companies are expanding into new sectors, markets, and supply chains. As organizations grow beyond their traditional networks, finance leaders need additional tools to assess customers, suppliers, and partners they may not know well.
Today’s CFOs are increasingly complementing business relationships with data-driven insights. They need greater visibility not only into credit risk, but also into supply chain dependencies, corporate ownership structures, payment behavior, and potential vulnerabilities across their ecosystem.
Predictive intelligence provides that forward-looking perspective. It helps businesses make faster and more informed decisions, strengthen due diligence processes, identify opportunities, and anticipate risks before they impact cash flow, operations, or growth plans.
What trends are you currently seeing in payment delays and corporate defaults across the UAE and Saudi Arabia?
The overall economic outlook in both the UAE and Saudi Arabia remains positive, supported by ambitious investment programs and continued economic diversification. At the same time, businesses continue to face uneven market conditions across sectors.
Drawing on Coface’s unique experience as a global trade credit insurer, we monitor payment behavior, claims activity, and credit events across millions of companies worldwide. What we are seeing today is not necessarily a significant increase in corporate failures, but rather signs of pressure on working capital in specific industries.
Payment delays have become more common in sectors exposed to longer project cycles, margin pressure, or supply chain disruptions. For finance leaders, the challenge is distinguishing between temporary liquidity constraints and deteriorating credit quality. This is where access to real-time payment data and early warning indicators becomes particularly valuable.
How can better credit intelligence improve cash flow, working capital, and overall financial resilience?
Better intelligence enables businesses to make more informed decisions across the entire customer and supplier lifecycle. By combining financial information, payment behavior, sector analysis, ownership data, Country Risk Assessments, Sector Risk Assessments, and ongoing monitoring, organizations gain a much clearer view of both risk and opportunity.
This has a direct impact on cash flow and working capital. Businesses can identify signs of financial stress earlier, reduce exposure to overdue accounts, prioritize collections efforts, and allocate credit more effectively. Access to real-time information and early warning indicators allows companies to act before issues translate into cash flow challenges.
Increasingly, however, financial resilience is not only about customer risk. It is also about understanding vulnerabilities across the supply chain. A disruption involving a key supplier, contractor, or logistics partner can have a significant impact on operations, costs, and liquidity. Better intelligence provides greater visibility into these critical dependencies, helping organizations identify concentration risks, assess the financial health of strategic partners, and strengthen business continuity planning.
As companies expand into new markets and engage with new customers, suppliers, and partners, they need confidence in who they are doing business with. Access to reliable data on ownership structures, financial health, payment behavior, sector outlooks, and country risk helps organizations make better-informed decisions and reduce uncertainty when entering new commercial relationships.
. What warning signs should finance leaders monitor before extending credit to new customers or entering unfamiliar markets?
Financial statements remain important, but they only tell part of the story. Finance leaders should also evaluate payment behavior, ownership structures, management stability, sector outlooks, supplier concentration, and exposure to geopolitical or regulatory risks.
One of the most valuable early warning indicators is a deterioration in payment behavior. In many cases, companies begin showing signs of financial stress long before it becomes visible in published financial statements.
Similarly, supply chain concentration risks should not be overlooked. A business may appear financially sound while remaining highly dependent on a small number of customers, suppliers, or projects. Understanding these dependencies is an increasingly important component of due diligence.
Effective credit decisions require a broader assessment of the business ecosystem rather than focusing solely on traditional financial metrics.
This is why a combination of company information, payment behavior, Country Risk Assessments, Sector Risk Assessments, and supply chain intelligence is increasingly becoming an essential part of the decision-making process.
How are AI and predictive analytics changing the way organizations assess credit risk and make financing decisions?
Financial statements remain important, but they only tell part of the story. Finance leaders should also evaluate payment behavior, ownership structures, management stability, sector outlooks, supplier concentration, and exposure to geopolitical or regulatory risks.
One of the most valuable early warning indicators is a deterioration in payment behavior. In many cases, companies begin showing signs of financial stress long before it becomes visible in published financial statements.
Similarly, supply chain concentration risks should not be overlooked. A business may appear financially sound while remaining highly dependent on a small number of customers, suppliers, or projects. Understanding these dependencies is an increasingly important component of due diligence.
Effective credit decisions require a broader assessment of the business ecosystem rather than focusing solely on traditional financial metrics.
This is why a combination of company information, payment behavior, Country Risk Assessments, Sector Risk Assessments, and supply chain intelligence is increasingly becoming an essential part of the decision-making process.
What sectors in the GCC are showing the strongest opportunities, and where are the highest risks based on your data?
Our outlook combines insights from Coface’s payment experience data, claims observations, Country Risk Assessments and Sector Risk Assessments. Together, these provide a comprehensive view of the opportunities and vulnerabilities shaping the business environment across the GCC.
We continue to see attractive opportunities in sectors supported by economic diversification strategies, digital transformation, infrastructure investment, logistics development and the energy transition. These areas are benefiting from sustained investment, strong policy support and growing regional demand.
At the same time, businesses operating in sectors facing tighter margins, elevated input costs, project execution challenges or longer payment cycles require closer monitoring. What is important to remember is that risk is rarely uniform across an entire sector. Performance can vary significantly from one company to another depending on its financial strength, competitive positioning, customer base and exposure to broader supply chain dynamics.
Looking ahead, how do you see the role of predictive intelligence evolving within corporate finance over the next three to five years?
Over the next three to five years, predictive intelligence will become an integral component of decision-making across finance, procurement, sales, treasury, compliance, and risk management functions.
We expect companies to move beyond using intelligence solely for credit assessments and begin embedding it throughout the business. This includes supplier selection, customer onboarding, supply chain management, compliance checks, investment decisions, and strategic planning.
The organizations that will be most successful are those that can combine technology, data, and human expertise to obtain a holistic understanding of their business ecosystem.
In an increasingly interconnected world, success will depend not only on knowing who you do business with, but also on understanding the risks and opportunities across the entire value chain. Access to reliable, forward-looking intelligence will therefore become a key competitive advantage, helping companies grow confidently while remaining resilient in a rapidly changing environment.

Al Bustan Centre & Residence concludes successful participation at Arabian Travel Market 2026

From 350+ Applications to One Champion: School of Cyber Defense Final Stage at GISEC GLOBAL 2026

Half a billion people live with arthritis: MEAF puts early action at the heart of World Arthritis Day 2026


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai