 Have a question? +971 56 404 0503

Financial News
RAKBANK more than doubles its quarterly Net Profit at AED 450M for Q1’23

RAKBANK delivered a Net Profit increase of 105% for Q1 2023 driven by a robust and diversified growth on both sides of the balance sheet. This was underpinned by strong sales momentum and lower cost of funds.

Raheel Ahmed – CEO of RAKBANK
- Total Income performance was supported by a strong net interest income of AED 788.8M, up 46.0% YoY. Net interest margins increased to 4.9% against 3.8% (Q1’22) and continues to be among the highest in the Industry. Q1’23 non-interest income of AED 284.4M, up 52.5% YoY. The growth in non-interest income was driven by higher forex and derivative income.
- Gross loans & advances at AED 38.7B, reflecting a 1.4% increase compared to 31 December 2022 on the back of a changing balance sheet mix in line with the strategic direction of the bank.
- Customer deposits stood at AED 46.4B, an increase of 3.3% compared to 31 December 2022. The Bank has a strong Current & Saving Account (CASA) franchise with the CASA ratio of 70.5%.
- Cost of Risk remained low due to the Bank’s diverse business mix and resilient UAE economic environment, leading to a 30.9% reduction in impairments as against Q4’22. Impaired Loan provision coverage ratio increased to 192.1% against 137.8% in Q1’22, remaining one of the strongest in the industry.
The Bank achieved balanced growth across all Business Segments:
Personal Banking:
- Gross loans & advances at AED 19.1B are up 1% YoY and +2% against FY’22 driven by the sales momentum across products with balance sheet for Auto loans +6%, Mortgages +5% and Personal loans +0.3%.
- Customer deposits of AED 16.7B, are up 22% YoY and +6% during the quarter driven by higher Term deposits +30% & CASA +0.3%.
- Q1’23 income supported by net interest income of AED 229M, +19.0% YoY and non-interest income of AED 123M, +1% YoY.
Business Banking:
- Gross loans & advances of AED 9.3B, are up 12% YoY and +3% against FY’22 mainly through higher volumes for Rak business loans +5%.
- Customer deposits of AED 19.7B, are up 14% YoY and +7% during the quarter driven by higher CASA deposits +7% & Term deposits +2.7%.
- Q1’23 income supported by net interest income of AED 337M, +57.0% YoY and non-interest income of AED 77M +6% YoY.
Wholesale Banking & Others:
- Gross assets (including lending to banks) of AED 19.8B, are up 13% YoY and +1% against FY’22 mainly driven by higher FI bank lending +2%.
- Customer deposits of AED 9.9B, are up 13% YoY and +7% during the quarter.
- Q1’23 income supported by net interest income of AED 224M, +68.0% YoY and non-interest income of AED 84M against a loss of 8Mn in Q1’22.
RAKBANK delivered strong shareholder returns with ROE of 19.4% and ROA of 2.8%, and remained highly liquid and well capitalized.
- The Bank’s Capital Adequacy Ratio (CAR) was at 16.8%.
- The regulatory eligible liquid asset ratio at 14.8%, compared to 12.8% as at 31 December 2022, and the advances to stable resources ratio stood comfortably at 81.8% compared to 79.7% at the end of 2022.
- Cost-income ratio improved to 36.2% driven by strong cost discipline, automation and digitization.
- The Bank’s non-performing loans ratio improved to 3.0% against 3.6% in Q1’22.
Raheel Ahmed, CEO of RAKBANK said, “Delivering on our multi-year strategy, we accelerated our growth and achieved a record net profit of AED 450M and a record total income of AED 1,073M for the quarter. In addition to this impressive growth, I am very pleased with the progress we are making in laying the foundation for sustainable growth.
In diversifying our income sources, we achieved robust growth on both sides of the balance sheet, across interest and fee incomes, and in all our segments. In terms of building deeper customer relationships, we achieved strong growth in digitally active customers with digital transactions growing by 12% YoY. Our high CASA ratio in our deposit base of 70.5% despite the high interest rate environment is a testament of the strong relationships we built with our customers and clients. We enhanced our operational leverage and improved our cost-income ratio through our strong cost discipline, and our cost of risk reduced via diversifying our business mix. The Bank remains well capitalized and liquid with a Capital Adequacy Ratio of 16.8% and an Eligible Liquid Asset Ratio of 14.8%. As a result of our progress, we achieved an ROE of 19.4% and ROA of 2.8%.
Being one of the largest SME banks in the UAE, we continue to back entrepreneurs and start-ups by opening more than 4,000 business accounts in Q1 2023, of which 1,600 accounts were opened for start-ups. Similarly, we disbursed AED 571M in business loans, out of which AED 394M were disbursed for new business loan customers.
As we grow, we are investing heavily in technology while maintaining cost discipline to digitize customer journeys, upgrade core data architecture, and revamp compliance and risk infrastructure. This investment will enable RAKBANK’s journey to provide a superior customer experience that is characterized by its hyper-personalization and relevance. The recent launch of our first fully digital accounts opening capability with straight-through processing is a good example of how we are digitizing our customer journeys.
Continuing from Q4 2022, we are focusing on expanding strategic hires to lead our growth, and we remain committed to and supporting the career aspirations and ambitions of our colleagues. Special attention is drawn to developing our Emirati talents as we align ourselves to the UAE leadership’s mission of growing and nurturing local talent.
As one of the nation’s leading financial institutions, RAKBANK recognizes our responsibility to support the ‘UAE Net Zero by 2050’ initiative. The team is actively engaged with RAK Government on COP28 submissions, working on financial inclusion and reducing emissions. We continue to support financial inclusion and accelerate digital remittances through our wages protection system partner and the United Nations Capital Development Fund.
Lastly, our outlook for FY 2023 remains positive yet cautious, with the buoyant UAE economy and uncertain global macro set up as backdrops. While we closely monitor the headwinds of inflation, rising interest rates, geopolitical developments, we will continue building on the Bank’s strengths and remain committed to delivering on our strategy.”
| Digital Transactions
+12% YoY |
Card Spends
|
Payment through our rails (In/Out) +9% YoY |
Digitally Active Customers
+15% YoY
|
Financial Highlights for Q1 2023
| Income Statement Highlights | Quarter Results | Variance | |||
| (AED Mn) | Q1’23 | Q4’22 | Q1’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Net Interest Income and net income from Islamic financing | 788.8 | 733.1 | 540.4 | 46.0% | 7.6% |
| Non-Interest Income | 284.4 | 261.6 | 186.5 | 52.5% | 8.7% |
| Total Income | 1,073.2 | 994.8 | 726.9 | 47.6% | 7.9% |
| Operating Expenditures | (389.0) | (371.4) | (372.4) | (4.5%) | (4.7%) |
| Operating Profit Before Provisions for Impairment | 684.2 | 623.3 | 354.6 | 93.0% | 9.8% |
| Provisions for Impairment | (233.9) | (338.7) | (134.5) | (73.9%) | 30.9% |
| Net Profit | 450.3 | 284.6 | 220.1 | 104.6% | 58.2% |
| Balance Sheet Highlights | Results as at | Variance | |||
| (AED Bn) | Mar’23 | Dec’22 | Mar’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Total Assets | 68.9 | 66.4 | 60.0 | 14.8% | 3.8% |
| Gross Loans & Advances | 38.7 | 38.1 | 37.2 | 4.1% | 1.4% |
| Deposits | 46.4 | 44.9 | 39.8 | 16.4% | 3.3% |
| Key Ratios | Quarter Ratios | Variance | |||
| Percentage | Mar’23 | Dec’22 | Mar’22 | Q1’23 | Q1’23 |
| vs Q1’22 | vs Q4’22 | ||||
| Return on Equity* | 19.4% | 12.5% | 10.5% | 8.9% | 6.9% |
| Return on Assets* | 2.8% | 1.7% | 1.5% | 1.3% | 1.1% |
| Net Interest Margin* | 4.9% | 4.5% | 3.8% | 1.1% | 0.4% |
| Cost to Income | 36.2% | 37.3% | 51.2% | 15.0% | 1.1% |
| Impaired Loan Ratio | 3.0% | 3.0% | 3.6% | 0.6% | 0.0% |
| Impaired Loan Coverage Ratio | 192.1% | 181.7% | 137.8% | 54.3% | 10.4% |
| Total Capital Adequacy Ratio Basel III** | 16.8% | 16.4% | 16.5% | 0.3% | 0.4% |
| * Annualized | |||||
| **After application of Prudential Filter | |||||
Profitability Growth supported by Income momentum and improvement in Provisions
- Net Profit increased by 104.6% to 450.3M (vs Q1’22 104.6% and Q4’22 58.2%).
- Net Interest Income and Income from Islamic products net of distribution to depositors increased by 46.0% to AED 788.8M (vs Q4’22 7.6%).
- Interest income from conventional loans and investments increased by 79.7%, while interest costs on conventional deposits and borrowings increased by 300.5%. Net income from Sharia-compliant Islamic financing increased by 7.8%.
- Non-Interest Income increased by 52.5% to AED 284.8M (vs Q1’22 52.5% and Q4’22 8.7%), primarily due to forex and derivative income booked in Q1 2023.
- Total Income increased by 47.6% (vs Q4’22 7.9%), benefiting from the balance sheet growth momentum.
- Operating Expenditure was AED 389.0M (vs Q1’22 AED 372.4M), reflecting a 4.5% increase compared to the same period in 2022, and a 4.7% increase compared to Q4 2022, due to the Bank’s growth investments.
- Operating Expenses increased mainly due to higher staff costs, card expenses, and other operating expenses. However, these were partly offset by lower IT expenses, occupancy costs, depreciation, and communication expenses.
- Cost-to-Income ratio for the bank decreased to 36.2% (vs Q1’22 51.2% and Q4’22 37.3%).
- Provision for credit loss increased by 73.9% to AED 233.9M for Q1 2023 compared to Q1 2022, due to prudent precautionary measures in anticipation of expected developments. However, compared to Q4 2022, the provision for credit loss decreased by 30.9% for Q1 2023.
- Net Credit Losses to average loans and advances closed at 2.5% (vs Q4’22 3.4%).
Balance Sheet crosses AED 68.9B with a strong uptick across all customer segments.
- Balance sheet crosses AED 68.9B as the Total Assets increased by AED 2.5B compared to 31 December 2022, reflecting a growth of 3.8%, with an increase in Cash/Central Bank balances by AED 929.2M, Investments by AED 805.8M, Gross Loans and Advances by AED 551.9M and Lending to Banks by AED 480.3M as compared to 31 December 2022.
- Business Banking portfolio increased by AED 264M, Retail Banking by AED 286.2M and Wholesale Banking segment (including bank lending) increased by AED 211M compared to 31 December 2022.
- Business Banking recorded 2.9% growth compared to 31 December 2022 with Business Loans growing by 5.3% and an increase of 1.5% on the Trade and Working Capital Loans portfolio.
- Retail Banking reflected a growth of AED 286.2 M supported by a strong sales momentum across products with Mortgages growing by 4.8% and Auto Loans by 6.4%.
- Non-performing Loans and Advances to Gross Loans and Advances ratio remained same at 3.0% as at 31 March 2023 compared to 31 December 2022.
Robust Growth in Customer Deposits as we continue to be the main bank for most of our customers
- Q1’23 Customer deposits increased by 3.3% compared to 31 December 2022, mainly due to an increase of AED 1,089.5M in CASA deposits and AED 404.7M in time deposits, endorsing the trust our customers place in RAKBANK’s solutions and services. RAKBANK has built a strong CASA franchise with a CASA ratio of 70.5 % as at 31 March 2023.
Strong Capital and Liquidity position
- The Bank’s Capital and Liquidity ratios remained strong.
- With a Total Capital Ratio as per Basel III, after the application of prudential filter, at 16.8% compared to 16.4% at the end of 2022.
- The regulatory eligible liquid asset ratio at the end of 31 March 2023 at 14.8%, compared to 12.8% as at 31 December 2022, and the advances to stable resources ratio stood comfortably at 81.8% compared to 79.7% at the end of 2022.
Healthy Cash Flows from operating activities
- Cash and cash equivalent as at 31 March 2023 were AED 4.7B compared to AED 4.3B as at 31 December 2022.
- Net cash generated from operating activities was AED 1.2B, AED 819.8M was used in investing activities and AED 4.7M used in financing activities.
Impact of Projected Capital Expenditure and Development
- The Group incurred AED 37.3M in capital expenditure in Q1 2023.
- RAKBANK will carry on advancing its investment towards customer-centric technology transformation.
Ratings
RAKBANK gets continuously rated by leading rating agencies with their latest ratings shown in the table below. This rating reflects the institutional strength of the Bank that is backed up by trust and transparency in financial reporting.
| Rating Agency | Last Update | Deposits | Outlook | |
| Moody’s | November 2022 | Baa1 / P-2 | Stable | |
| Fitch | April 2023 | BBB+ / F2 | Stable | |
| Capital Intelligence | August 2022 | A- / A2 | Positive | |
Financial
Pay10 Announces Strategic Partnerships at Dubai FinTech Summit 2026, Advancing the UAE’s Digital Payments Ecosystem

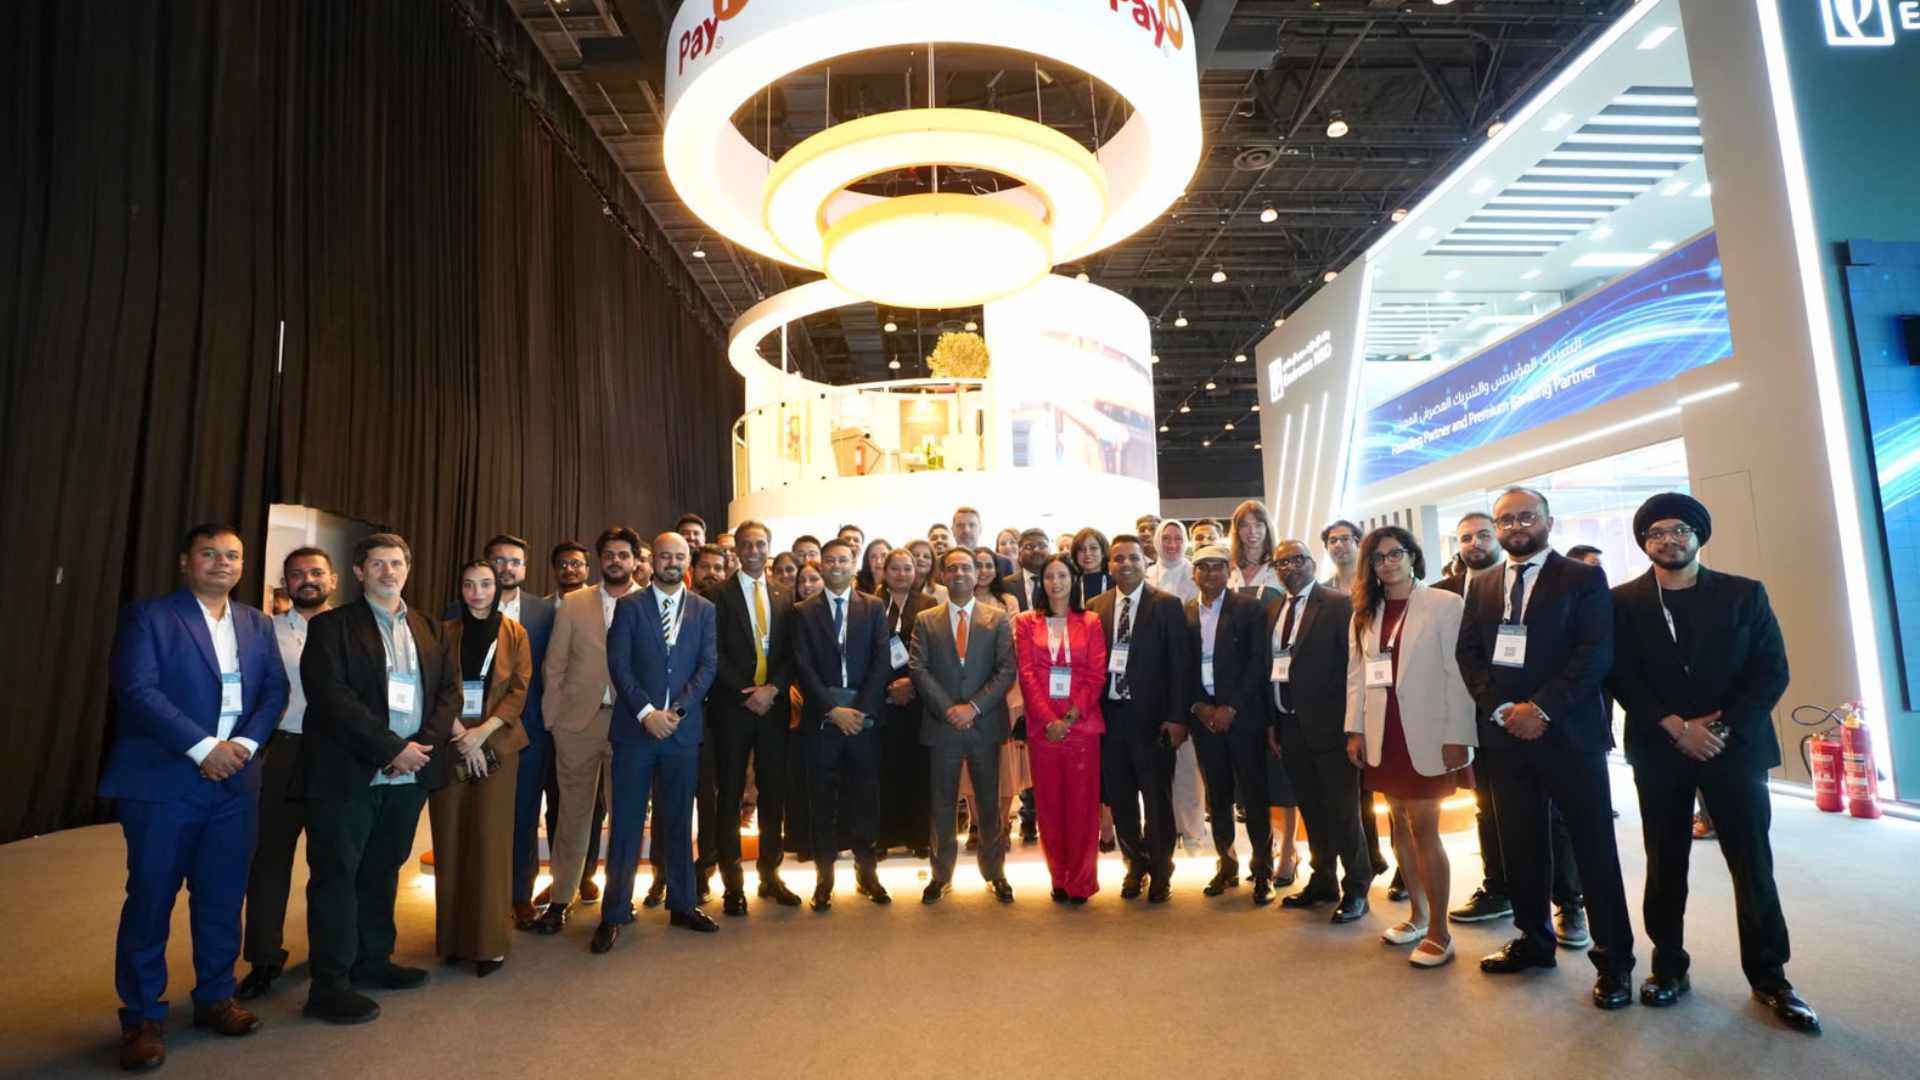
Pay10, a UAE-regulated financial technology company, today announced a series of strategic partnerships, commercial agreements and Memoranda of Understanding (MoUs) at Dubai FinTech Summit 2026. The announcements mark a step towards expanding digital payment choices and supporting the UAE’s transition towards real-time, interoperable and account-based payments, in alignment with the Central Bank of the UAE’s Financial Infrastructure Transformation (FIT) Programme.
Pay10’s partnerships with leading brands, including GEMS, Jumbo Electronics, Bikanervala, Allday, Just Gold and Save In Gold, span education, retail, food and beverage and specialised commerce. With live deployments already in place at GEMS, Bikanervala, Allday and Just Gold, Pay10 is extending its payment ecosystem across everyday consumer and business transactions.
Building a Connected Payments Ecosystem
Pay10 brings together instant payments, Open Finance, digital accounts, domestic card infrastructure and merchant payment acceptance through an integrated platform.
Directly integrated with Aani, Pay10 enables instant payments and supports account-based payment experiences. Its Open Finance capabilities allow consumers to securely connect supported bank accounts, access consolidated financial information and monitor spending through one application. Its Jaywan issuance capabilities also enable eligible wallet customers to access domestic card payments across POS terminals, ATMs and e-commerce channels.
For merchants, the platform offers multiple payment acceptance options, including Pay by Pay10, Pay by Bank, card acceptance, interoperable QR payments, payment links and digital payouts. Its proprietary POS application, QR and soundbox solutions are supported by an in-house Terminal Management System.
Through supported account-based payment methods, merchants can access funds in real time, helping improve cash flow and reduce payment acceptance costs, with potential savings of up to 70% in applicable use cases. Pay10 also reports transaction success rates of over 90% across its integrated technology infrastructure.
Strategic Partnerships and Collaborations
The partnerships with GEMS and Jumbo Electronics aim to expand digital payment choices and improve collection efficiency across education and consumer retail. Existing deployments with GEMS, Bikanervala, Allday and Just Gold demonstrate the application of Pay10’s payment solutions across different commercial environments.
Allday, a leading convenience chain in the region, presents an opportunity to explore the impact of digital payment solutions across high-frequency, small-value transactions.
Pay10 also announced several MoUs to explore emerging financial use cases. Its partnership with Yalla Financial Solutions, part of Fintra Holding, will explore bank-account-based wallet funding through Open Finance.
Additionally, our collaboration with TotalPay will enable TotalPay to access Pay10’s merchant payment acceptance capabilities through its technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
Dr. Waleed Sadek, Founder & CEO of Yalla Financial Solutions, said: “We are pleased to explore this strategic collaboration with Pay10, reflecting our shared vision of building a more connected and accessible financial ecosystem. Through Open Finance and account-based wallet funding, we aim to unlock new opportunities for seamless digital payments and enhance the financial experience for businesses and consumers across the region.”
Supporting the UAE’s Financial Infrastructure
Pay10’s strategy aligns with the Central Bank of the UAE’s FIT Programme through the adoption of domestic payment infrastructure, including Aani, Jaywan and Open Finance. By investing in direct infrastructure connectivity and proprietary technology, the company aims to support greater interoperability, financial inclusion and more efficient payment experiences.
Harry Gill, Founder & Chairman, Pay10, said: “The UAE has laid the foundations for the future of finance, and our goal is to make it accessible to everyone. Pay10 is building a UAE-based alternative payment ecosystem that brings together domestic payment infrastructure, Open Finance, accounts, cards and merchant solutions. Our partnerships with GEMS, Jumbo Electronics, Bikanervala, Allday and Just Gold reflect growing confidence in this vision. We remain committed to advancing the UAE’s financial ambitions through a connected, interoperable ecosystem built to scale globally.”
Our collaboration with TotalPay will enable it to access Pay10’s payment acceptance capabilities for merchants through TotalPay’s technology platform and integrations. The partnership aims to expand merchant payment choices and simplify the adoption of emerging payment solutions.
With further agreements, product launches and integrations in development, Pay10 aims to expand its consumer and merchant capabilities across the UAE and international markets.
Henry Dannell, a specialist cross-border credit adviser, has announced its expansion into the Middle East with the opening of a representative office in Dubai International Financial Centre (DIFC), marking a significant milestone in the firm’s international growth strategy.
The move reflects rising demand for specialist advice among internationally mobile individuals whose financial interests increasingly span multiple jurisdictions, asset classes, and lending structures. As Dubai continues to strengthen its position as a global wealth and investment hub, attracting entrepreneurs, family offices, investors, and high-net-worth individuals from around the world, the complexity of managing wealth across borders has increased significantly. Many of these individuals now live, work, invest, and hold assets internationally, creating borrowing requirements that often extend beyond conventional lending frameworks.
Henry Dannell’s expansion into Dubai is designed to bring the firm’s specialist expertise closer to the region’s growing network of wealth advisers, family offices, tax specialists, legal professionals, and internationally connected clients.
Founded in 2019, Henry Dannell has built a reputation for delivering bespoke credit and lending solutions for clients with highly sophisticated financial circumstances. The firm’s advisers support a broad spectrum of clients, from business owners and entrepreneurs to ultra-high-net-worth individuals, helping them navigate complex borrowing scenarios that frequently involve multiple jurisdictions, unconventional income structures, and international assets. Unlike traditional mortgage providers, Henry Dannell operates as a specialist advisory business focused on structuring tailored credit solutions and working alongside trusted professional advisers to address complex financing requirements.
The establishment of the DIFC representative office represents the first phase of the company’s broader regional growth ambitions and will serve as a hub for relationship-building, market engagement, and collaboration with professional advisory communities across the Middle East.
Kem Kemal, CEO and Co-Founder of Henry Dannell, said: “Over the last decade, we have seen a fundamental shift in how wealth is created, managed, and deployed. Successful individuals are increasingly global in their outlook. They may operate businesses in one country, hold investments in another, and seek opportunities across several markets simultaneously. Yet lending has not always evolved at the same pace.”
He explained that too often, highly accomplished individuals with substantial assets and strong financial positions encounter challenges because their circumstances fall outside conventional frameworks. “Our role is to understand the complete picture and design bespoke solutions that reflect the realities of modern international wealth.”
“Dubai has become one of the most important centers for global capital, entrepreneurship and wealth advisory services,” he added. “Establishing a presence within DIFC allows us to be closer to the professional advisers and internationally connected clients we serve, while strengthening relationships across a region that continues to play an increasingly influential role in global finance.”
With over 165 years of combined industry experience across its advisory team, Henry Dannell has developed specialist expertise across residential, commercial, and specialist lending transactions. Through its Dubai presence, Henry Dannell aims to deepen engagement with the region’s professional advisory ecosystem while contributing to discussions around international wealth, investment, and cross-border financial planning.
Financial
The UAE’s Net Wealth Reaches $3.6 Trillion in 2025 and is Expected to Approach $6 Trillion by 2030, BCG Report Finds
The UAE’s net wealth grew by 12.7% between 2024 and 2025, rising from $3.2 trillion to $3.6 trillion, according to Boston Consulting Group’s (BCG) Global Wealth Report 2026: The Great Reordering. Total Net wealth is forecast to reach $6 trillion by 2030, with a CAGR of 10.6%. This represents an increase of more than $2.3 trillion over the next five years. The projected growth points to the UAE’s long-term wealth creation potential.
Financial wealth, including both investable and non-investable wealth, grew by 12.3% between 2024 and 2025, rising from $1.2 trillion to $1.4 trillion and is set to rise to $2.1 trillion by 2030 at a CAGR of 8.7%. Real assets reached $2.4 trillion in 2025 from $2.2 trillion in 2024, with projected growth to $4.2 trillion by 2030.
The findings show the resilience of the UAE wealth market amid a volatile global environment and heightened geopolitical uncertainty. “The ongoing conflict has introduced short-term volatility across Middle Eastern markets, with investor sentiment shaped by geopolitical uncertainty and oil-price movements,” said Lukasz Rey, Managing Director and Partner at BCG. “However, the region’s wealth development story remains structurally resilient over the five-year projection horizon. While we anticipate slightly lower growth over the next one to two years, a rebound is expected toward the latter part of the decade, supported by sovereign wealth strength, economic diversification agendas, family-business liquidity events, and continued private capital activity. We expect wealth managers to remain cautious in the near term; however, the long-term wealth opportunity in the Middle East remains intact.”
The report identifies a broader reordering underway across the global wealth-management industry, spanning geographic shifts, emerging-market wealth creation, intergenerational succession, and AI-driven operating model transformation.
Shifting Wealth Concentration Across UAE Population Segments
According to the report, the UAE’s financial wealth remains concentrated among high-net-worth individuals, with the composition of wealth expected to evolve by 2030 as more wealth accumulates within the lower high-net-worth segment. There are approximately 500 ultra-high-net-worth (UHNW) individuals, those with more than US$100 million in assets, in 2025, and they are expected to increase to around 800 by 2030, while their share of total financial wealth rises marginally from 26.3% to 26.5%. The upper high-net-worth segment (US$20–100 million) is forecasted to grow from approximately 2.7K to 4.2K individuals, with its share of wealth broadly stable at 7.4% in 2025 to 7.6% in 2030.
In contrast, the lower high-net-worth segment (US$1–20 million), which comprises approximately 200K individuals, is expected to increase its share of financial wealth from 29.3% in 2025 to 31.5% in 2030. The affluent segment (US$0.25–1 million) is expected to expand from approximately 500K to 600K individuals in 2030, while its share of wealth declines from 15.5% to 14.6% as wealth disperses across a larger base. The mass segment (below US$0.25 million) remains the largest by population, growing from roughly 8.6M to 9M individuals, but its share of financial wealth decreases from 21.5% to 19.8%.
The key UAE findings of BCG’s proprietary analysis are:
- Financial wealth reaches $1.4 trillion in 2025, with strong projected growth to $2.1 trillion by 2030 (CAGR: 8.7%)
- Real assets rose to $2.4 trillion in 2025 and are expected to hit $4.2 trillion by 2030 (CAGR: 11.5%)
- Liabilities climbed to $220 billion in 2025 from $210 billion in 2024, with projections indicating $340 billion by 2030 (CAGR: 8.9%)
- Cross-border financial wealth belonging to UAE residents and booked outside the UAE surged by 9.4% between 2024 and 2025 in the UAE, reaching $468.4 billion. It is forecasted to grow to $678.2 billion by 2030 with a CAGR of 7.7%.
- Separately, the UAE continues to strengthen its position as a global wealth booking center, with cross-border wealth belonging to international clients and booked in the country reaching $721 billion in 2025, up 11.1% year-on-year.
- Currency & Deposits, valued at $471.8 billion in 2025, is projected to grow to $778.9 billion by 2030, with a CAGR of 10.5%
- Bonds are expected to reach $27.8 billion by 2030 from $15.9 billion in 2025, with a CAGR of 11.8%
- Equities, valued at $419.4 billion in 2025, are expected to reach $591.9 billion by 2030 at a CAGR of 7.1%
- Life Insurance & Pensions are valued at $26.6 billion in 2025 and projected to grow to $48.4 billion by 2030 (CAGR: 12.7%)
AI Is Reshaping the Economics of Wealth Management
BCG’s report finds that AI is beginning to reshape wealth-management economics and operating models. AI-powered tools are already drafting financial plans, automating compliance documentation, generating portfolio rationales, and predicting client churn. According to BCG analysis, AI-first wealth managers could unlock 25%–30% capacity gains across key workflows while increasing revenue per advisor by 15%–20%. The report argues that the industry is approaching a structural divide between firms redesigning workflows around AI agents and those layering AI tools onto legacy processes.
“The UAE’s wealth pool is set to grow by more than $2 trillion over the next five years, and the constraint on capturing that growth is advisor capacity rather than client demand,” said Mohammad Khan, Managing Director and Partner at BCG. “Firms that are redesigning their workflows around AI agents are creating the headroom to serve a larger client base without diluting the quality of advice. Those layering AI onto legacy processes are paying for the technology without changing their economics, and that gap widens the longer it is left.”
Wealth managers face a choice between adapting incrementally and committing to an AI-first future, with the report identifying the latter as the more sustainable approach. Key priorities include:
- Map value chain exposure: Identify rules-based, templatized processes most vulnerable to automation. Distinguish truly bespoke, relationship-dependent work from structured, repeatable tasks to guide investment decisions.
- Attack high-cost workflows: Scale AI now in financial planning, portfolio management, and compliance, automated drafting, AI-generated rationales, knowledge assistants.
- Rebuild the advisor experience around AI: Integrate next-best-action prompts, retention alerts, automated documentation, and personalized outreach into a unified system.
- Encode institutional knowledge into agents: Pair top practitioners with engineers to build and refine AI agents. Embed advisor judgment into today’s agents, without centralized ownership and outcome-based evaluation, differentiation erodes.
- Prepare the tech stack for agents. Introduce a decoupled data layer separating operational systems from data consumption, delivering real-time, API-accessible data while maintaining deterministic control through transaction systems and rules engines.

Qatar Airways Unveils Onboard Signature Music Created in Partnership with Award-Winning Composer Hans Zimmer

Laura Hammett Expands to the Middle East with New Studio in Dubai
RAF ABU DHABI ADDS STARZPLAY AS DISTRIBUTION PARTNER ACROSS MENA


-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai