 Have a question? +971 56 404 0503

Financial
From AI to Instant Settlements: Boosting Acceptance, Fighting Fraud, Maximizing Revenue!


Financial Integrator sat down with Remo Giovanni Abbondandolo, General Manager for MENA at Checkout.com, which is at the forefront of the digital payments revolution, offering a diverse range of payment methods tailored to global and regional needs. Supporting over 145 currencies, its technology helps businesses boost acceptance rates, combat fraud, and optimize revenue. With innovations like AI-powered Intelligent Acceptance and Flow, Checkout.com enhances transaction efficiency while maintaining compliance with regulatory standards. The company is also addressing the growing demand for cross-border payments in MENA, where e-commerce is surging.
What range of payment methods does Checkout.com offer to meet diverse customer needs, and how do these solutions address varying preferences and requirements?
Checkout.com processes payments for thousands of companies that shape the digital economy. Our global digital payments network supports over 145 currencies and delivers high performance payment solutions across the world, processing billions of transactions annually. With flexible and scalable technology, we help enterprise merchants boost acceptance rates, reduce processing costs, combat fraud, and turn payments into a major revenue driver.
Our global suite of connected payment methods enhances payment performance and makes it easy for customers to shop how they prefer, wherever they are. By partnering with us, merchants can access these tools to drive loyalty and conversions across markets. In addition to popular payment methods like major credit and debit cards and digital wallets such as Apple Pay and Google Pay, we provide a variety of region- and country-specific solutions. In the MENA region, this includes local options like Mada in KSA, KNET in Kuwait, Benefit in Bahrain, Qpay in Qatar, Omannet in Oman and wallets such as STC Pay. We also support alternative payment methods tailored to diverse use cases, such as Tabby and Tamara for Buy Now Pay Later (BNPL) options.
Our extensive range of options gives businesses the flexibility to implement payment methods that align with their target markets and specific needs. Leveraging our local expertise and global reach, our partners can expand more easily by facilitating cross-border transactions and enhancing customer experiences. By meeting customers where they are and supporting their preferred payment methods, we help businesses thrive in the digital economy. Whether enabling seamless cross-border transactions for global brands or empowering merchants to serve niche markets, our solutions are designed to adapt to evolving demands while ensuring top-tier payment performance and compliance.
Can you share insights on the innovations Checkout.com is implementing to enhance convenience, personalization, and overall user experience for end-users?
At Checkout.com, we’re constantly innovating to enhance convenience, personalization, and user experience for end-users. For example, our AI-powered Intelligent Acceptance tool is setting a new standard in payment performance by analyzing real-time data to maximize transaction approval rates. Running millions of optimizations per day, it has helped customers unlock $9bn in additional revenue, using AI trained on billions of transaction data points originating from the entire Checkout.com merchant portfolio.
In addition, Flow, our customizable payment interface, further simplifies the payments process for merchants by dynamically presenting the most relevant payment methods based on user preferences, market demands, and regulatory requirements. It has built-in optimizations that aim to streamline the payment experience for consumers. This flexibility enables businesses to seamlessly expand into new markets while adhering to compliance standards such as PCI, GDPR, and card scheme regulations.
We also prioritize user experience by designing intuitive, mobile-optimized payment flows that ensure accessibility across devices. Our real-time fraud detection systems have prevented over $2 billion in fraudulent activity, ensuring the highest level of trust for both merchants and consumers.
Checkout.com also launched the Checkout Business Account last year, designed to help businesses optimize cash flow management and reduce the time and cost of money in transit. For merchants, faster access to cash is critical, hence the company provides same-day settlements before receiving funds from Visa or Mastercard. Further rollouts are anticipated in 2025, including competitive yields on balances and seamless expense management.
By combining advanced technology with user-first design, Checkout.com helps businesses deliver payment experiences that are not just fast and secure but also personalized to meet the evolving expectations of today’s customers worldwide.
What factors are driving the increasing demand for cross-border payments, and how does Checkout.com address the complexities associated with this growing requirement?
The rising demand for cross-border payments is driven by key trends highlighted in our “State of Digital Commerce in MENA 2024” report. E-commerce growth has dramatically reshaped the region, with the number of daily digital shoppers in MENA surging by 80% since 2020. Saudi Arabia leads this digital transformation with an impressive 180% growth in consumers shopping online at least once a week, followed by the UAE and Kuwait, which have each seen a 140% increase. As consumer trust in online transactions grows, preferences are shifting rapidly – cash-on-delivery usage has halved since 2020, dropping to just 10% in the UAE and Saudi Arabia.
These evolving consumer behaviors underline the demand for secure, seamless, and efficient payment experiences. The report also reveals strong preferences for cross-border shopping, particularly in Qatar and Kuwait, where 41% and 40% of respondents, respectively, cited cross-border shopping as a key motivator for e-commerce. Saudi Arabia remains at the forefront of this trend, driven by its status as the largest regional market for cross-border transactions.
These trends underscore the vast opportunities for merchants to capitalize on the economically resilient MENA market while catering to its diverse consumer preferences. However, the varied shopping behaviors across sectors and regions add layers of complexity to meeting customer needs in an increasingly globalized landscape.
At Checkout.com, we simplify these challenges with a comprehensive portfolio of innovative products and services, bolstered by deep regional expertise. Our localized acquiring solutions optimize transaction efficiency by reducing costs and enhancing approval rates, all while improving payment performance, supported by a strong network of partnerships across the region.
How are advanced payment solutions, such as AFT’s, enhancing the ecommerce experience for businesses and consumers?
Advanced payment solutions like Account Fund Transfers (AFTs) are revolutionizing e-commerce by addressing inefficiencies in traditional payment systems and unlocking new opportunities for businesses and consumers.
For businesses, AFTs enable faster cash flow by reducing settlement times from days to seconds, enhancing liquidity and operational efficiency. This real-time processing allows companies to reinvest funds quickly, scale operations, and expand into new markets. Beyond e-commerce, AFTs are transforming industries such as remittance, enabling seamless cross-border transfers that are faster and more cost-effective. They are also supporting the rapid growth of digital wallets by allowing instant top-ups, meeting the demands of a digital-first economy. The innovative partnership between Visa, Checkout.com, and Stake serves as a strong example of how AFTs can facilitate seamless global transactions, simplifying cross-border payments and reducing costs.
For consumers, AFTs provide the speed, convenience, and security required in today’s fast-paced digital world. Whether it’s transferring funds, topping up wallets, or making purchases, AFTs ensure instant, reliable transactions. As seen in the UAE real estate sector, AFTs also enable global users to access opportunities previously hindered by traditional payment complexities, offering seamless and secure investment capabilities.
By combining speed, efficiency, and security, AFTs transform how businesses and consumers interact with digital payment systems, fostering trust, innovation, and growth across a variety of use cases in the global economy.
What is Checkout.com’s perspective on the future of the payment industry over the next 5-10 years, particularly in the context of the MENA region’s evolving digital economy?
At Checkout.com, we envision the future of payments as one characterized by seamless, secure, and efficient transactions, driven by continuous innovation and evolving consumer expectations. Our commitment is to provide businesses and consumers with cutting-edge payment solutions that simplify and enhance the digital economy.
We are focused on empowering businesses with advanced solutions like Account Fund Transfers (AFTs), which improve cash flow by enabling faster, more predictable settlements. AFTs help businesses streamline operations, reduce costs, and expand into new markets, providing a clear advantage in an increasingly globalized economy. By optimizing payment performance, we enable merchants to enhance approval rates, minimize payment failures, and maximize revenue potential.
For consumers, we ensure instant, frictionless transactions that meet the demands of a fast-paced digital world. With real-time processing and advanced fraud detection, we deliver a seamless and secure experience that fosters trust in digital commerce platforms.
At Checkout.com, flexibility, agility, and performance are at the core of everything we do. Our localized acquiring solutions and deep regional expertise enable us to optimize transaction efficiency, enhance approval rates, and support merchants in their growth. As we continue to innovate, we remain dedicated to shaping the future of payments and driving the digital economy forward with secure, efficient, and customer-centric solutions that improve payment performance across the board.






Exclusive Interview with Nasir Khan, Co-Founder, Synovo
The MENA startup ecosystem is shifting from growth at all costs to sustainable business models. What has changed, and what does it take to build a financially resilient startup from the outset?
I think the biggest change is that investors have become less willing to finance a business model indefinitely while founders work out the economics. A few years ago, a compelling growth story could carry a lot of weight. Today, people want to know what each additional customer costs, when that customer becomes profitable and how much cash the company needs to get there.
For me, resilience starts with knowing the difference between revenue, profit and cash. Having worked across telecom distribution, factoring and healthcare ventures, I’ve seen businesses look healthy on paper while working capital quietly becomes their biggest problem.
My advice is to start small enough to test your assumptions, know your margins well and build a business that can survive a slow month, not just celebrate a good one.
Raising capital is only one step towards building a successful business. What financial mistakes do startups commonly make after securing investment, and how can they avoid them?
The most common mistake is treating money in the bank as proof that the business has succeeded. Suddenly there is a bigger office, a larger team and three new markets on the roadmap, before the original model has really been proven. Fixed costs rise quickly, and reversing them is much harder.
I prefer to see founders tie each stage of spending to a milestone: demonstrating repeat purchases, shortening the sales cycle, improving gross margin or reaching a defined number of paying customers.
I’d also keep a fallback plan in case the next round takes twice as long as expected. Fundraising buys time, but what matters is what you prove during that time.
Drawing on your experience in structured finance, how should MENA founders choose between equity, debt and other financing options at different stages of growth?
I spent years in factoring and structured finance, and one lesson has stayed with me: match the type of financing to the risk you are financing.
Equity makes sense when the product, market or revenue model is still uncertain, because investors are sharing the risk of finding out whether the business works. Debt is better suited to predictable cash flows or identifiable assets. Once a business has reliable receivables, trade finance or factoring can fund working capital without giving away more ownership.
But debt is not a cure for an unprofitable business. It creates a payment obligation whether the next contract arrives or not. Founders should also watch for currency mismatches and personal guarantees. The cheapest-looking capital is not always the safest.
Access to capital varies across MENA markets. How should founders in emerging startup hubs approach financial planning differently from those in established ecosystems such as the UAE and Saudi Arabia?
First, I would resist treating MENA as a single market. Access to investors is only one difference. Collection cycles, currency exposure, regulation, customer purchasing power and the availability of experienced hires all change from country to country.
In a smaller funding ecosystem, I would plan for a longer fundraising process and keep costs as variable as possible. A local commercial partnership is often more useful early on than opening a fully staffed operation.
Even in the UAE or Saudi Arabia, access to capital does not mean every startup is fundable. Founders still have to show that they understand their own market. Expansion should follow customer evidence, not a regional map in a pitch deck.
Cash flow is critical to a startup’s survival. Which financial metrics should founders monitor, and how can they maintain cash flow discipline while pursuing growth?
I would start with five things: cash in the bank, monthly net burn, runway, gross margin and the time between invoicing a customer and actually collecting the money.
For subscription businesses, retention and customer acquisition cost matter enormously. For businesses selling to corporates or governments, receivables ageing can be just as important as revenue growth.
A simple weekly cash forecast looking 13 weeks ahead can prevent a lot of unpleasant surprises. I also like a monthly downside scenario: what happens if collections are delayed, or sales come in 25% below plan?
These are not glamorous exercises, but I’ve seen how quickly a growing business can run into trouble when sales rise faster than the cash needed to deliver them.
What makes a startup truly investor-ready today, particularly in terms of financial reporting, governance, unit economics and operational discipline?
Investor readiness is not a beautiful data room put together two weeks before a meeting. It is the discipline with which the business has been run over the previous year.
Can the founder explain the margin on a customer? Reconcile revenue to cash received? Show who owns the company, what obligations exist and which assumptions sit behind the forecast? Do they know how much of their revenue depends on a handful of customers?
In healthcare ventures such as Synovo, which I co-founded, financial planning also has to reflect clinical evidence, regulatory requirements and hospital procurement cycles. Ignore those realities and even an attractive forecast becomes meaningless.
Investors understand that early-stage businesses will not have perfect systems. What worries them is when founders cannot explain their numbers or become defensive when challenged. Being candid about risks usually strengthens investor confidence rather than weakening it.
How can MENA founders balance growth with profitability and reduce dependence on repeated funding rounds? When should they rethink their strategy if new investment fails to materialise?
Profitability does not need to arrive on day one, but the route to it should be visible. The test I use is whether growth improves the economics or simply increases the losses. If every new customer makes the funding gap bigger, scale is not solving the problem.
I would review the plan well before the runway becomes critical. If investment is uncertain, narrow the product range, protect the best customers, reduce fixed commitments and concentrate on revenue that turns into cash.
Sometimes a smaller, profitable core is the right foundation for a much larger company. Waiting until the last three months of cash to make those decisions usually leaves very few good options.
Through your involvement with the London Business School MENA Startup Competition, what distinguishes genuinely scalable startups from those with compelling pitches, and what will define the next generation of successful MENA businesses?
The competition reminded me that a polished pitch and a scalable business are two different things. The founders who caught my attention were not necessarily the ones with the grandest projections. They were the ones who could explain what customers had actually done, what they had learned from being wrong and what the next round of capital would achieve.
Our shortlisted teams were mentored by LBS alumni and volunteers, and it was encouraging to see founders willing to challenge their own assumptions rather than defend them.
I think the next generation of strong MENA businesses will combine regional ambition with local execution, sensible capital structures and the ability to earn customer trust.
Winning a competition can open doors. What founders build after the applause is what ultimately counts.
Dr. Nasir Khan is a medical doctor, entrepreneur and Sloan Fellow from London Business School. He has been building businesses since 2001 across telecom distribution, financial services, medtech and process manufacturing, and has co-founded ventures including Synovo, a UK-based digital health platform. He has also served as a judge for startup induction at the Punjab Information Technology Board’s incubation programme in Lahore and is Co-President of the LBS Entrepreneurship Club, MENA.
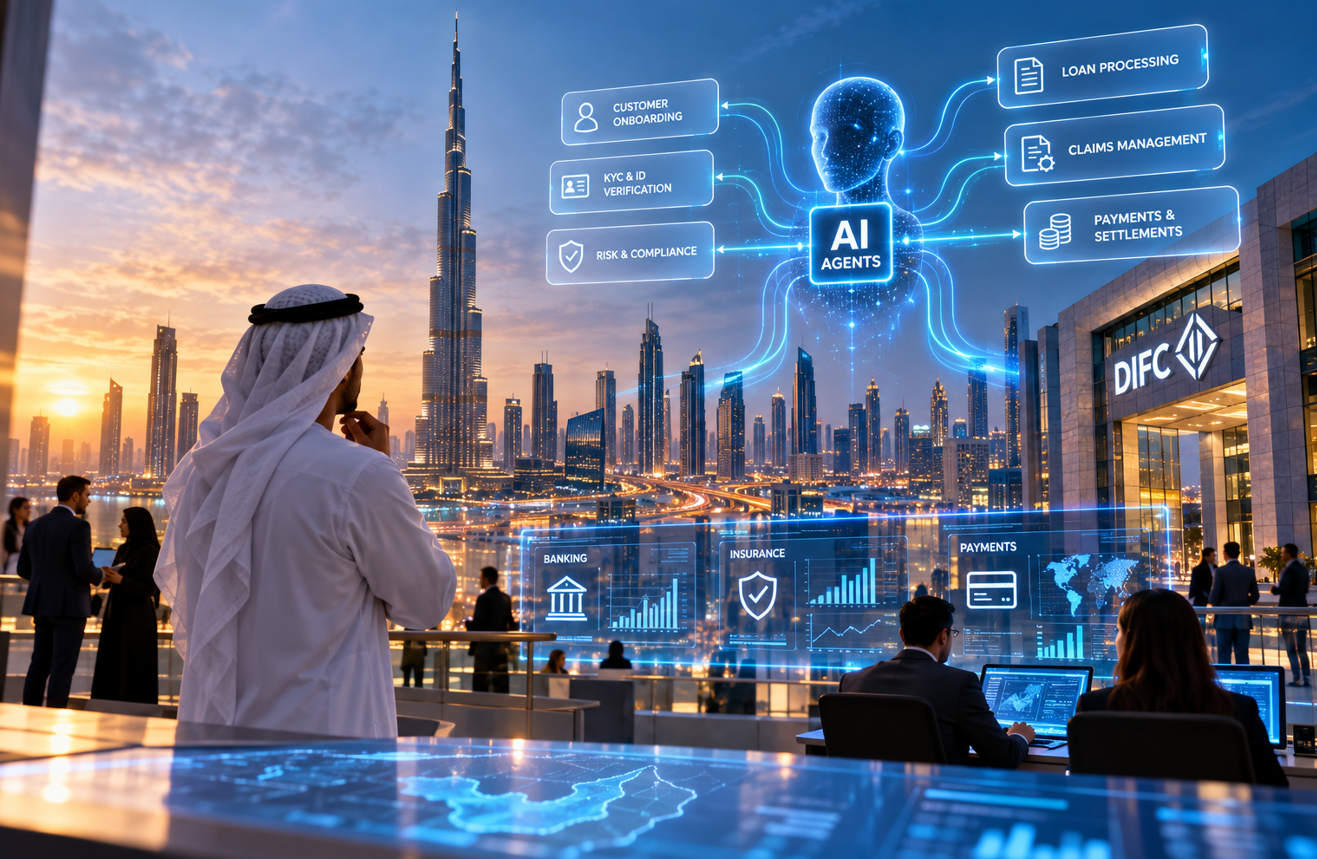
With Dubai fast-tracking agentic AI and AI use among DIFC financial firms rising sharply, Samir Akel, Regional Vice President, Emerging Markets at Nintex, sets out how orchestration turns agentic AI into results for UAE banks and insurers.
This week, much of the region’s technology community has gathered in Abu Dhabi for AI Everything, and the question on the show floor has moved on. A year ago, banks and insurers asked whether to deploy AI agents; today they want to know how to make those agents deliver results across an entire customer journey.
Government is setting the pace. On 5 October, the Dubai Future Foundation launched an agentic AI accelerator covering 33 government entities and more than 300 public-facing use cases, building on the federal target to run half of government services and operations on agentic AI within two years. Few countries have put a number and a deadline on agentic AI. The UAE has done both.
Finance is keeping up. The Dubai Financial Services Authority’s survey of 661 DIFC firms found that 52% now use AI, up from 33% a year earlier, while generative AI use rose by 166%; the regulator also noted that, for many firms, adoption is still at an early stage. UAE finance has AI in many places. The value comes when those pieces work together.
Work in financial services is fragmented
Follow a corporate account opening at a typical UAE bank. The application lands in a portal or a relationship manager’s inbox; documents and identity are checked, sanctions screening runs in a separate tool, a risk team reviews the file, a committee signs it off and operations sets up the account in core banking. That’s six steps, six systems and one waiting customer.
AI agents speed up individual steps: an agent can extract a trade licence in seconds or draft a risk summary in minutes. Then the file sits in a queue for a reviewer who has no idea it is ready. The task gets faster, while the journey stays as slow as its slowest handoff.
That gap is the coordination tax, made up of the hours lost chasing approvals, re-keying data and fielding “where is my application?” calls. In banking, insurance and payments, where one journey can cross half a dozen teams, it is often the largest cost nobody actually measures.
Process is the foundation
Institutions that turn AI into outcomes start by understanding how work actually runs, and regulated firms have a head start here because they already document their processes for supervisors. The task is to map those processes as they really operate (workarounds and exceptions included) and give each step to the right worker.
Steps that must run identically every time, such as sanctions checks and payment releases, suit rules-based workflow. Reading documents and reasoning over unusual cases suit AI agents. Judgement belongs to people. With the Central Bank’s AI guidance for the sector placing clear emphasis on human oversight, deciding where people sit in a process is now part of designing it.
Orchestration makes AI operational
Once the process is clear, orchestration connects it. It coordinates people, systems, data and agents across a whole journey, deciding who or what acts next and routing exceptions to the right person before they become delays.
Think of an airport, where more aircraft add capacity only when air traffic control sequences them. AI agents work in the same way.
For a bank or insurer, orchestration brings one view of every application, claim or payment. Core banking and policy platforms keep their role while work flows between them, and each orchestrated journey becomes a template for the next, so the tenth deployment goes live faster than the first.
A 90-day starting point
Finance can borrow the government’s 90-day rhythm. Pick one journey that crosses at least three systems and two departments, such as SME lending or a motor claim, and map it as it runs today. Count the handoffs and measure the time lost between them; that figure is your coordination tax. Then assign each step to a rule, an agent or a person, orchestrate the whole journey and track time to decision. Reuse what works.
The orchestrators will lead
At the accelerator launch, Digital Dubai’s Director General said the future of digital government depends on an integrated ecosystem that brings expertise, data and capabilities together. The same holds inside every bank.
Over the next year, the number of AI agent use cases across UAE banking and government will grow rapidly. The institutions that pull ahead will be those with a platform to orchestrate and govern those agents, taking them from pilot to production at scale, while keeping people in control. In the AI era, operational advantage belongs to the orchestrators.
Henry Dannell, a specialist cross-border credit adviser, has announced its expansion into the Middle East with the opening of a representative office in Dubai International Financial Centre (DIFC), marking a significant milestone in the firm’s international growth strategy.
The move reflects rising demand for specialist advice among internationally mobile individuals whose financial interests increasingly span multiple jurisdictions, asset classes, and lending structures. As Dubai continues to strengthen its position as a global wealth and investment hub, attracting entrepreneurs, family offices, investors, and high-net-worth individuals from around the world, the complexity of managing wealth across borders has increased significantly. Many of these individuals now live, work, invest, and hold assets internationally, creating borrowing requirements that often extend beyond conventional lending frameworks.
Henry Dannell’s expansion into Dubai is designed to bring the firm’s specialist expertise closer to the region’s growing network of wealth advisers, family offices, tax specialists, legal professionals, and internationally connected clients.
Founded in 2019, Henry Dannell has built a reputation for delivering bespoke credit and lending solutions for clients with highly sophisticated financial circumstances. The firm’s advisers support a broad spectrum of clients, from business owners and entrepreneurs to ultra-high-net-worth individuals, helping them navigate complex borrowing scenarios that frequently involve multiple jurisdictions, unconventional income structures, and international assets. Unlike traditional mortgage providers, Henry Dannell operates as a specialist advisory business focused on structuring tailored credit solutions and working alongside trusted professional advisers to address complex financing requirements.
The establishment of the DIFC representative office represents the first phase of the company’s broader regional growth ambitions and will serve as a hub for relationship-building, market engagement, and collaboration with professional advisory communities across the Middle East.
Kem Kemal, CEO and Co-Founder of Henry Dannell, said: “Over the last decade, we have seen a fundamental shift in how wealth is created, managed, and deployed. Successful individuals are increasingly global in their outlook. They may operate businesses in one country, hold investments in another, and seek opportunities across several markets simultaneously. Yet lending has not always evolved at the same pace.”
He explained that too often, highly accomplished individuals with substantial assets and strong financial positions encounter challenges because their circumstances fall outside conventional frameworks. “Our role is to understand the complete picture and design bespoke solutions that reflect the realities of modern international wealth.”
“Dubai has become one of the most important centers for global capital, entrepreneurship and wealth advisory services,” he added. “Establishing a presence within DIFC allows us to be closer to the professional advisers and internationally connected clients we serve, while strengthening relationships across a region that continues to play an increasingly influential role in global finance.”
With over 165 years of combined industry experience across its advisory team, Henry Dannell has developed specialist expertise across residential, commercial, and specialist lending transactions. Through its Dubai presence, Henry Dannell aims to deepen engagement with the region’s professional advisory ecosystem while contributing to discussions around international wealth, investment, and cross-border financial planning.
A REIMAGINED PRIME68 RETURNS TO JW MARRIOTT MARQUIS DUBAI ALONGSIDE ION, A NEW “NEIGHBOURHOOD IN THE SKY”
Radisson Blu Hotel Dubai Deira Creek Invites Guests to Celebrate Diwali with Family, Flavour and Festive Stays
Trust Is the New Speed – AI, Lexis+ with Protégé and the future of legal work in the Middle East


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR10 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai