 Have a question? +971 56 404 0503

Financial
Emerging Trends Shaping Financial Empowerment and Inclusion in the UAE Workforce

By Claudio Di Zanni, Managing Director, Edenred Middle East
One of the most critical issues faced by low-income employees across the UAE and the broader Gulf region is achieving true financial empowerment. In the UAE, over 60% of the workforce comprises low-income migrant workers earning less than AED 5,000 per month. These employees are the backbone of the nation’s key industries, yet many still struggle to access the benefits of a fully digital financial ecosystem.
While the UAE’s Wage Protection System (WPS) was introduced to safeguard workers’ rights—ensuring salaries are paid accurately, on time, and through traceable digital channels—the banking system’s minimum salary requirement prevents a large portion of the workforce from opening traditional accounts. This creates a structural gap that payroll solutions are designed to fill, enabling compliant salary payments and basic access to digital finance.
As the Middle East accelerates its digital transformation and workforce reforms, how workers are paid and supported financially has become as important as how they contribute to growth. This shift has put a renewed spotlight on the systems managing their wages and day-to-day financial needs. For low-income employees, these systems determine not just how they are paid, but how securely they live—affecting access to savings, remittances, and their ability to handle emergencies.
When Digital Pay Isn’t Enough
The introduction of the Wage Protection System marked a turning point in the UAE’s journey toward fair and transparent wage practices. Today, nearly all employees are paid through digital channels, ensuring salaries are disbursed accurately and on time. Yet despite these advances, a significant percentage of wages are still withdrawn in cash each month, showing that digital pay does not automatically translate into digital financial inclusion.
For many employees, limited digital literacy, mistrust of financial systems, and unfamiliarity with digital tools prevent them from engaging fully with the digital economy. As a result, the very system designed to protect and empower workers can feel more like a compliance obligation than an opportunity for empowerment.
This is where payroll providers play a critical role. Too often, the industry stops at compliance—ensuring wages are delivered digitally—without addressing the human factors that determine whether employees can truly benefit from financial technology. Empowerment comes not from the transfer itself, but from helping workers understand, trust, and use digital money confidently. Only then can payroll innovation translate into lasting financial well-being and equal access to economic opportunity across the UAE.
Digital salary management platforms have already transformed how employees receive and manage their earnings. Mobile apps and prepaid cards now give workers immediate access to their wages, allowing them to make purchases, send remittances, and track expenses in real time. Many solutions integrate seamlessly with the WPS, enabling even unbanked employees to participate in the digital economy for the first time. A recent study found that organizations implementing mobile-accessible payroll solutions report up to 25 percent higher employee satisfaction, underscoring the clear business value of digital inclusion.
Empowering Through Education
Financial literacy programs are equally critical in helping employees make informed decisions about saving, budgeting, credit, and long-term planning. In the UAE, less than 31 percent of the population demonstrates basic financial literacy, highlighting a major opportunity to empower workers through education.
From workshops to mobile-based learning tools, such programs can equip employees with the practical skills to use digital salary systems effectively, avoid debt traps, and build savings or plan remittances. Employers that distribute salary cards directly at worker accommodations and provide multilingual support during onboarding see much higher adoption rates, as these field-level activations build trust and make digital tools easier to use.
Employers who take financial education seriously often see a clear business impact. Companies that invest in onboarding sessions and field engagement consistently report higher digital adoption rates. These activations not only build trust but also transform digital payroll from a compliance task into a tangible employee benefit.
When workers understand and trust digital tools, they gain control over their finances—and that stability shows at work. Financial stress is one of the most common challenges among low-income employees, limiting their ability to manage urgent expenses and affecting productivity, retention, and overall well-being. In sectors such as construction, this stress can even impact concentration and safety, as employees distracted by financial worries are less able to perform at their best.
Partnerships between employers and fintechs like Edenred are expanding this approach, combining digital wage tools with financial education programs that improve confidence, satisfaction, and long-term well-being.
The Next Phase of Financial Empowerment
Employers remain central to driving inclusion. By choosing payroll partners that provide multilingual support, education, and easy mobile access, companies can reduce disputes, strengthen retention, and improve overall workforce stability.
A growing number of organizations are now exploring earned wage access programs, which allow employees to access a portion of their earned income before payday. Surveys show that most low-income workers value this flexibility to cover urgent expenses, medical bills, or family emergencies—without resorting to high-interest loans or informal borrowing. When paired with education and budgeting tools, earned wage access can provide not just relief in emergencies but also encourage more responsible money management.
This flexibility can increase employees’ sense of financial security, yet it should complement—not replace—broader financial literacy and planning initiatives. The most successful models combine accessible financial products, user education, and ongoing engagement, ensuring workers have both the tools and the confidence to manage their finances effectively.
As technology evolves, artificial intelligence and data analytics will make financial support more personalized and accessible. Predictive models can help employers identify employees under financial strain, while new digital products can guide users toward healthier financial behaviors. But technology alone will not close the gap.
Real progress will depend on collaboration between fintechs, employers, and regulators to build an ecosystem that blends technology, education, and empathy. Businesses increasingly recognize that supporting workers in their financial journeys fosters a more engaged and loyal workforce, directly impacting productivity and retention. Selecting payroll partners that combine compliance with education, multilingual support, and mobile accessibility helps companies reduce payroll disputes and improve satisfaction.
The trajectory of financial empowerment for low-income employees in the UAE is promising. The next stage will depend on how effectively stakeholders align innovation with understanding—ensuring every salary payment becomes an opportunity for inclusion and growth. When that happens, financial empowerment will move from aspiration to reality.






Financial
UAE Ranks First Globally in Citizen Satisfaction with Government Digital Services at 89%, BCG Survey Finds

The UAE ranks first globally in citizen satisfaction with government digital services, with 89% of respondents rating them highly, according to Boston Consulting Group’s (BCG) sixth annual edition of its 2026 Digital Government Citizen Survey Report, which was launched on the first day of AI Everything Abu Dhabi, titled “After a Decade of Digital Gains, AI Is Reshaping Citizens’ Expectations in the GCC[SM1] [GU2] .” The finding underscores the strength of the UAE’s digital government experience and provides a strong foundation for the next phase of AI-enabled public services.
The survey, conducted across 44 countries, also highlights the depth of the UAE’s digital engagement, with the country ranking first globally in government digital service usage at 53%. More than three-quarters (76%) of UAE respondents say their latest online government transaction delivered a better experience than their typical private-sector interaction, reinforcing the strength of the country’s digital government ecosystem.
This strong digital foundation is increasingly extending into AI adoption, where 82% of UAE respondents reported using AI weekly. High levels of usage are accompanied by relatively positive attitudes toward AI in government, with 53% of UAE respondents believing its benefits outweigh the risks, compared with 49% across the GCC and 36% globally. At the same time, greater exposure to AI is bringing a broader set of considerations into focus for citizens. While GCC citizens remain more optimistic about AI in government than their global peers, overall optimism has declined by 21% since 2024.
This evolution points toward a more hybrid model of service delivery. GCC citizens increasingly favor AI for simpler services while retaining human involvement for more complex interactions, which assures a shift that reflects greater awareness of both the opportunities and considerations associated with AI. At the same time, only around 4% of GCC respondents prefer human-only services with no AI support, compared with almost one in ten globally.
“The UAE’s strong digital government experience reflects years of investment in making public services more accessible, seamless, and responsive to citizens’ needs,” said Rami Mourtada, Partner & Director, Digital Transformation, BCG. “As AI becomes more embedded in public services, governments have an opportunity to build on this foundation with more AI-enabled experiences and process re-engineering to continue focusing on quality and convenience. This next phase will be about deploying AI where it creates clear value, while maintaining human expertise for more complex citizen needs.”
GCC Citizens Embrace the Next Generation of AI-Enabled Services
The BCG report also reveals strong appetite among GCC citizens for the next generation of AI-enabled government services. The region is the most AI-receptive globally, with 79% of citizens open to AI-centered government interactions, compared with 66% globally. Notably, three of the four most strongly supported AI applications in government are agentic use cases, signaling a healthy launchpad for governments to explore services that can move beyond providing information to supporting or completing actions on citizens’ behalf.
This openness is already evident across practical applications: 82% are comfortable with AI providing 24/7 access to information and services; 81% with AI supporting government customer-service agents; 79% with AI detecting fraud and automatically following up; and 78% with AI identifying services citizens qualify for and taking action on their behalf. [SM3] [GU4] Yet citizens are not calling for AI alone. Preference for “AI for simple services, people for complex ones” has risen nine percentage points to 50% over the past two years, reinforcing a hybrid model that combines AI-enabled speed and availability with human judgment for more complex or higher-stakes interactions.
This opportunity builds on a strong track record in digital government service quality. In 2026, the GCC remained the only surveyed region where a majority of citizens rated government digital services above those of the private sector, at 72%. However, private-sector experiences are gaining ground: the net share of GCC respondents rating government services above private-sector services declined from 75% in 2024 to 69% in 2026. The shift creates both a learning opportunity and an impetus for governments to continue innovating as citizen expectations evolve.
As governments move toward more advanced AI-enabled services, citizen AI literacy will be equally important. GCC respondents with expert-level AI proficiency are around four times more likely than those without AI experience to believe that the benefits of AI in government outweigh the risks. At the same time, greater familiarity with AI is sharpening citizens’ expectations around how it is deployed. Job loss (33%) and accuracy (28%) now rank as the leading concerns, underscoring the importance of pairing AI literacy with safeguards that are visible and relevant to citizens.
“The GCC has a strong opportunity to translate its digital leadership into the next generation of AI-enabled government services,” said Dr. Lars Littig, Managing Director & Senior Partner, BCG. “As citizens become more familiar with AI, building literacy and trust will be critical to sustained adoption. The opportunity is to move forward with AI in ways that reflect how citizens want to engage, expanding automation and agentic capabilities where they create value, while retaining human judgment and embedding responsible safeguards where they matter most.”
Six Priorities for the Next Generation of Digital Government
To build on the region’s digital progress and maximize the potential of AI in government services, BCG’s report outlines six priorities for GCC governments:
- Rethink core services with AI, redesigning them end to end rather than layering AI onto existing processes.
- Learn from private-sector innovation as digital experiences improve and citizen expectations evolve.
- Embed responsible AI through governance, testing, and safeguards that strengthen citizen trust.
- Build the hybrid model citizens want, using AI for simpler interactions while retaining human expertise for complex or high-stakes needs.
- Expand agentic AI services beyond information toward services that can support complete journeys and act on citizens’ behalf.
- Advance AI literacy to build citizen understanding, confidence, and informed adoption.
Together, these priorities can help GCC governments build on a decade of digital progress and translate citizens’ openness to AI into the next generation of public services. By combining strong digital foundations with responsible AI adoption and continued access to human expertise, the region is well positioned to deliver services that are more proactive, personalized, and responsive to citizens’ evolving needs — while sustaining the trust that will be critical to long-term adoption
To access the full BCG Digital Government Citizen Survey2026, visit the link here.
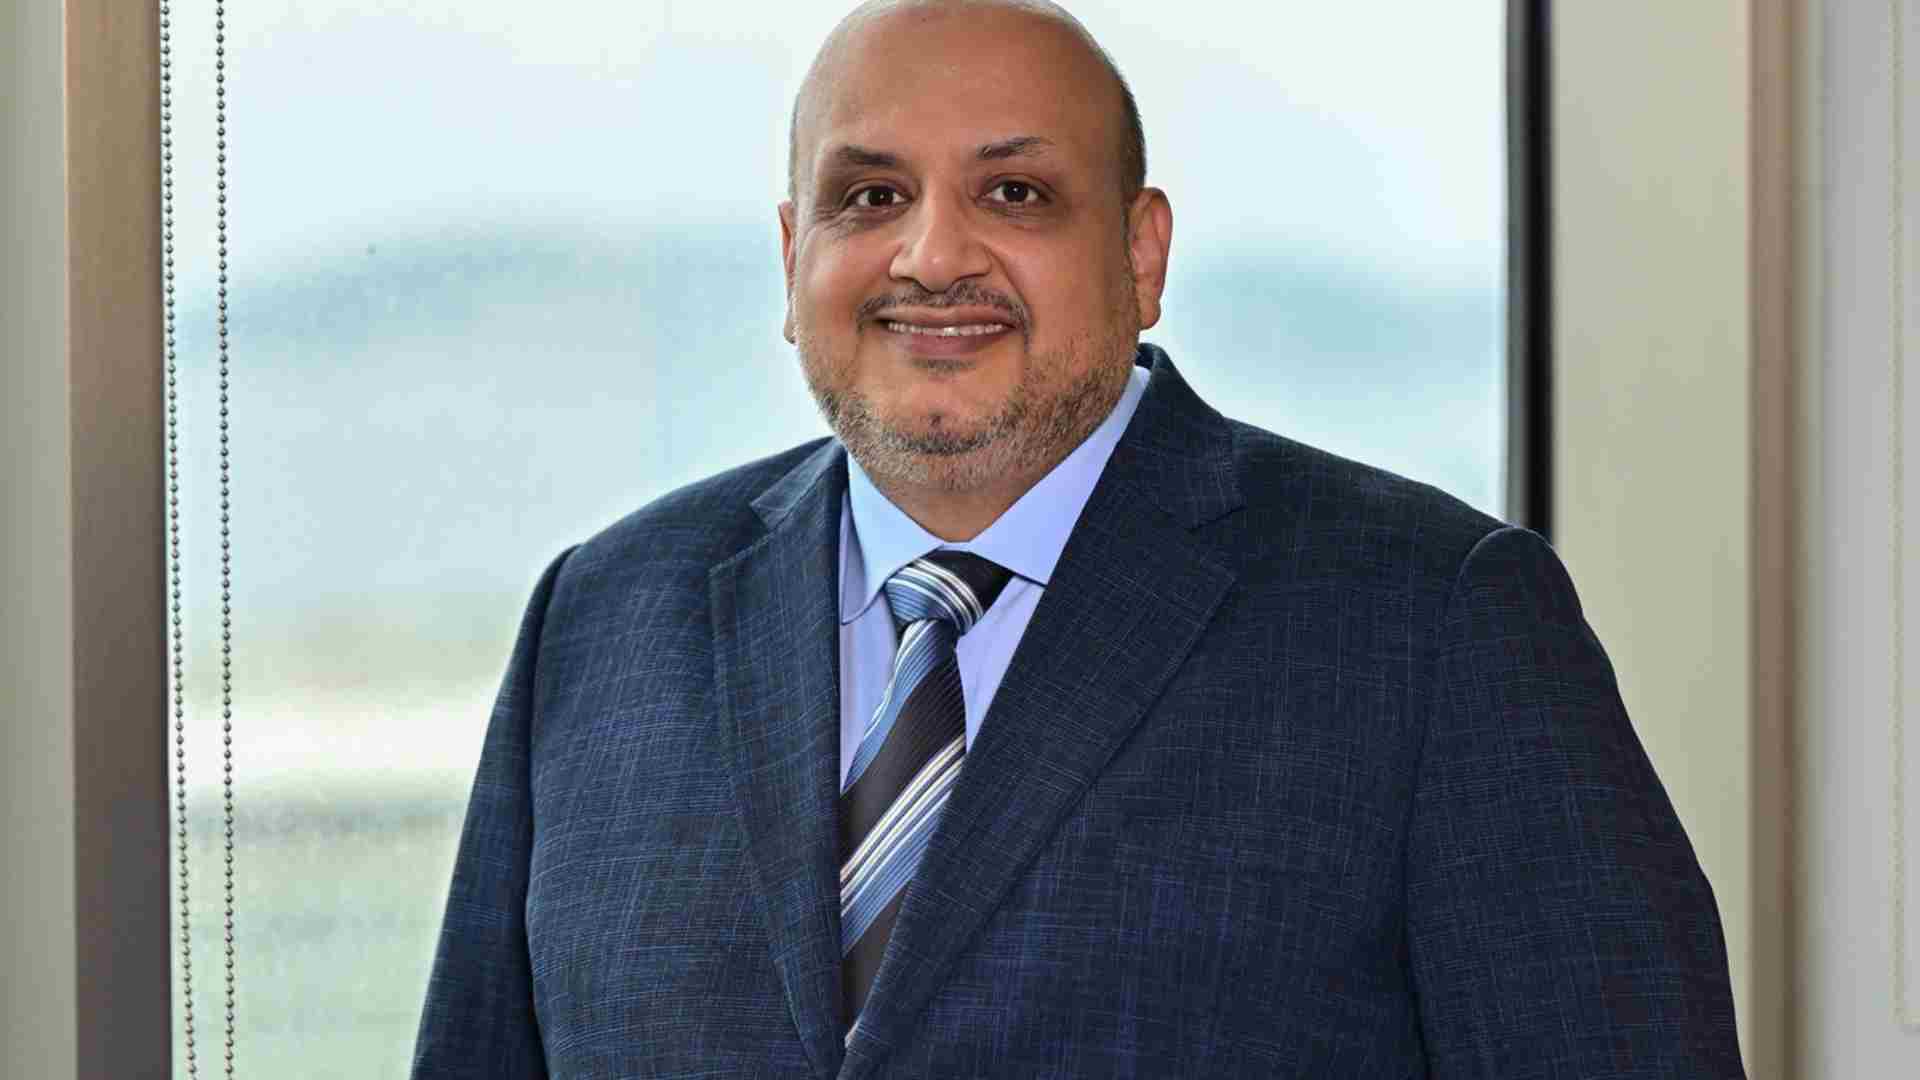
Responses attributed to Amr Kandel, GCC Country Manager and Product Director, Fimple
How is the shift towards cloud-native core banking changing the way financial institutions in the GCC approach technology modernisation?
The biggest change is that banks are moving away from the idea that modernisation has to mean replacing everything at once.
In the GCC, we’re seeing more interest in a progressive approach, introducing new products, capabilities or customer journeys while continuing to use existing systems where they still make sense. Cloud-native and composable architecture makes that much more practical.
Unlike systems that are simply moved from on-premises infrastructure into the cloud, cloud-native architectures are designed so that capabilities can be deployed, updated and scaled more independently. This allows institutions to upgrade selected areas without having to tie every change to a large transformation programme.
GCC institutions also have to consider regulatory requirements, data governance and local market needs. It is not simply about moving systems to the cloud. Banks need to decide where data and capabilities should sit, how they are governed and how the overall environment remains resilient.
What are some of the key technology limitations of legacy core banking systems that GCC banks are looking to overcome today?
There are a few challenges that come up quite consistently.
The first is speed. Many legacy platforms were designed around batch processing, so getting a current view of the customer or making decisions in real time can be difficult.
The second is fragmented data. Customer information and banking capabilities can sit across different systems for deposits, lending, payments, cards and other services. That creates complexity and makes it harder to deliver a consistent customer experience.
The third is product agility. With heavily customised and hard-coded systems, launching a new product or changing an existing one can take months.
And finally, there is integration. When every new fintech, payment provider or ecosystem partner requires another point-to-point integration, the technology environment becomes harder to manage.
For GCC institutions, the challenge is not simply to replace an old system. It is to reduce dependencies and create a more flexible foundation that makes integration, localisation and regulatory change much easier to manage.
Fimple takes an API-first approach to core banking. How does this architecture help financial institutions integrate emerging technologies and third-party services more efficiently?
In an API-first architecture, integration is part of the platform from day one rather than something added afterwards.
At Fimple, core banking capabilities such as accounts and deposits, lending, payments and limits can be accessed through APIs. That makes it much easier for financial institutions to connect channels, fintech partners, wallets, payment providers and other services.
These services are designed to be accessible and reusable. Instead of building a completely different integration every time a new partner comes in, institutions can use the same underlying architecture and governance model.
This approach is particularly relevant in the GCC because every market has its own ecosystem and local requirements. Banks need the flexibility to connect to local payment infrastructures, regulatory services and fintechs without rebuilding their core every time.
As banks increasingly adopt AI and automation, what role does a modern core banking platform play in enabling these technologies at scale?
AI is moving from something that sits around the bank to becoming part of how it operates.
Today, many institutions already use AI for functions like customer assistants, fraud detection, document processing or analytics. However, scaling AI requires a strong foundation underneath it.
AI needs access to accurate and timely data, clearly defined business rules and secure ways to interact with banking capabilities, with the right controls and human oversight.
At Fimple, we see the next step as agentic AI interacting with banking capabilities through secure APIs and controlled workflows. An AI agent could, for example, support an onboarding process, assist with servicing, or work within a lending or payment process while the bank still controls what the agent is allowed to do.
The goal is not simply to make a core banking platform AI-enabled. The real opportunity is to build a platform that is AI-ready by design.
How important is interoperability in the GCC financial ecosystem, particularly as banks, fintechs and digital financial platforms become increasingly connected?
Banks, fintechs, wallets, payment providers and digital platforms across the GCC are becoming more connected, and customers expect their experiences to work together.
For financial institutions, that means the ability to work securely with partners is becoming a business capability, not just an IT requirement.
There is also an important GCC dimension here. The GCC may be viewed as one market from a broader economic perspective, but each country has its own regulatory environment, payment infrastructure and requirements. Institutions need a common foundation that can still accommodate those differences.
This is where composable, API-led architecture can help. Institutions can connect capabilities, launch new propositions and adapt to local requirements without redesigning the entire banking platform each time.
Ultimately, interoperability gives financial institutions the flexibility to participate in the wider ecosystem rather than trying to build everything themselves.
Businesses buying or selling companies in the UAE are finding that the transaction itself, rather than their existing operations, brings them within the global minimum tax. That is the central finding of the latest ‘Deals Decoded’ publication from Dhruva, a Ryan LLC affiliate, on how the rules influence what a business is worth, how a deal is structured and when it should complete.
The global minimum tax, known internationally as Pillar Two, was agreed by more than 140 countries and jurisdictions through the Organisation for Economic Co-operation and Development. It requires the largest international groups to pay at least 15% tax on profits earned in every country where they operate, with any shortfall, known as a top-up tax, becoming payable. The UAE adopted it through Cabinet Decision No. 142 of 2024, effective for financial years beginning on or after 1 January 2025, and collects the shortfall on UAE profits locally rather than ceding it abroad.
The rules apply only to groups with worldwide revenue of at least EUR 750 million, approximately USD 860 million, in two of the previous four years. Many UAE businesses have concluded this places them safely outside. Dhruva identifies four points at which a transaction changes that assessment.
The first is scale. When two groups combine, their revenues are assessed together. A buyer with EUR 500 million of revenue acquiring a business with EUR 300 million enters the regime on completion, though neither neared the threshold alone.
“The threshold test is where most boards are caught out,” said Nimish Goel, Leader, Middle East Dhruva, A Ryan LLC Affiliate. “Two mid-sized businesses, each outside the regime, combine and find themselves inside it from day one. This is routinely delegated to the finance function when it belongs with those setting the price. Established at screening stage, the analysis costs little. Discovered after signing, it is hard to reverse.”
The second is timing. The tax is calculated annually on a country-wide basis and does not divide when ownership transfers, so a business being sold stays within the seller’s figures until legal completion, whenever the buyer assumes commercial risk. Completing on the first day of a financial year removes the problem.
The third is visibility. A group’s UAE companies are assessed together rather than individually, so a target cannot be evaluated in isolation.
“A business has no tax position of its own while it remains inside a seller’s group,” said Bhakti Thakker, Partner, Mergers and Acquisitions and International Tax at Dhruva, A Ryan LLC Affiliate. “The rate is an average across every company the seller holds in that country, so the buyer is pricing something it cannot fully see. Companies in the same country may also be required to settle one another’s liability, which a warranty does not address. The contract needs a defined section on who prepares the calculation, who bears the cost, and how it settles once figures are final.”
The fourth is the acquisition premium. Where a buyer pays more than the accounting value of a business, part of that cost is ordinarily written off over time, reducing taxable profit. The global minimum tax rules largely disregard those write-offs, leaving taxable profit higher than expected.
Two further developments narrow the margin. The allowance groups receive for genuine operations in a country, based on employment costs and physical assets, reduces annually by design, from 9.6% and 7.6% respectively in 2025 to 9.4% and 7.4% in 2026, and 5% each by 2033. A transitional simplification sparing some groups the full calculation ends for financial years beginning on or after 1 January 2027.
Ownership structure is decisive for sovereign wealth funds and private equity investors. Government bodies fall outside the rules, but that status does not extend to the companies they hold, and where investments sit beneath a holding company that is not a government body, the whole group is in scope.
Dhruva recommends four steps ahead of any transaction. Buyers should test the combined revenue threshold when a target is first identified, not during contract negotiation, and model the tax as a cash cost in financial projections, allowing for the reducing allowance. Sellers should prepare tax records for inspection in advance, since a position that cannot be evidenced invites a price reduction. Both should review insurance cover, which frequently excludes a risk already identified during due diligence. “Businesses that address this early are negotiating from a position of information. Those that do not are negotiating on assumption,” concluded Bhakti.
Kenz ‘de’ Rasasi Debuts at Beautyworld Middle East 2026 with a New Expression of Rasasi Heritage

Burjeel Holdings Launches Preventive Cardiac Campaign Across Its UAE Hospital Network for World Heart Day

Abu Dhabi Projects and Infrastructure Centre and PATRIZIA sign strategic partnership to support infrastructure investment and development


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR2 years ago
Samsung Galaxy Z Fold6 vs Google Pixel 9 Pro Fold: Clash Of The Folding Phenoms