 Have a question? +971 56 404 0503

Tech Features
THE RISE OF THE AUTONOMOUS ECONOMY: A 2025 RETROSPECTIVE FROM THE MIDDLE EAST

Kayvan Karim, Assistant Professor at School of Mathematical and Computer Sciences, Heriot-Watt University Dubai
The year 2025 will likely be remembered as the moment the global economy stopped simply automating tasks and started handing over the keys to autonomous agents. For decades, the promise of automation was simple: machines doing repetitive work faster than humans. But the last twelve months have ushered in a fundamental paradigm shift. We have moved from the era of static scripts to the age of “Agentic AI”, systems that don’t just follow orders but perceive, reason, and act to achieve complex goals.
In their 2025 Technology Trends report, Accenture’s analysts have termed the explosion of these capabilities as “The Binary Big Bang”. As generative AI becomes central to enterprise technology, the cost of development has plummeted, leading to a proliferation of new systems where digital agents act autonomously. These systems have given rise to Agentic AI, which acts as a proactive partner rather than a passive interface. These agents are now capable of “Superagency,” a collaboration architecture that orchestrates multi-agent systems to handle complex workflows that require specialised knowledge across different domains.
This shift is nowhere more palpable than in the Middle East. From the giga-projects of Saudi Arabia to the smart logistics hubs of Dubai, the region is leveraging this technological inflection point to decouple its economic future from hydrocarbons and rebuild it on a foundation of silicon and code.
The Economics of Intelligence
The catalyst for this revolution is a dramatic collapse in the cost of cognitive labour. When examining the economics of intelligence, Stanford University reported in its 2025 AI Index Report that the catalyst for this explosion in autonomy is the radical democratisation of computing power. Between late 2022 and late 2024, the inference cost for a system performing at the level of GPT-3.5 dropped over 280-fold. This trend accelerated through 2025, with hardware costs declining by approximately 30% annually and energy efficiency improving by 40% each year.
These economic shifts have lowered the barriers to entry, moving advanced AI from the realm of massive research labs to the operational budgets of mid-sized enterprises. As Menlo Ventures noted in their mid-year update, enterprise spending on model APIs more than doubled to $8.4 billion in the first half of 2025 alone, signalling a decisive shift from experimental “training” budgets to production-grade “inference” budgets.
The Middle East’s Sovereign Pivot
In the Gulf Cooperation Council (GCC), this technological wave is being ridden with strategic intent. The region is not content to merely import Western or Eastern models; it is building its own “Sovereign AI.”
In the UAE, the Technology Innovation Institute (TII) has continued to push boundaries with its Falcon series. As highlighted by ITU in 2025, the Falcon LLM has evolved into a multi-modal framework capable of processing vision and audio, enabling it to interpret complex documents and charts locally without data leaving the country. Similarly, G42’s Inception has solidified Jais’s position as the world’s premier Arabic-centric model. By integrating Jais into the Microsoft Azure Model Catalogue, they have provided generative AI access to over 400 million Arabic speakers, ensuring that the nuances of the region’s language and culture are preserved in the digital age.
Saudi Arabia has matched this ambition with the launch of Humain, a PIF-backed AI champion. According to Reuters reports from late 2025, Humain is not only building massive data centre capacity but is also developing a voice-first operating system designed to replace traditional icon-based interfaces. This aligns with the Kingdom’s broader Vision 2030 goals, where AI is expected to contribute over $135 billion to the economy.
From Automation to Autonomy in Industry
The distinction between “automation” (following rules) and “autonomy” (making decisions) is best illustrated in the region’s critical infrastructure.
In the energy sector, Saudi Aramco and Yokogawa achieved a historic milestone at the Fadhili Gas Plant. As reported by Oilfield Technology, they successfully deployed autonomous control AI agents that utilise reinforcement learning to optimise the Acid Gas Removal unit actively. Unlike traditional systems, these agents adapt to changing environmental conditions without human intervention, reducing chemical and steam consumption by up to 15%.
Similarly, ADNOC partnered with G42 and Microsoft to launch “EnergyAI.” This agentic system automates complex tasks such as seismic analysis and geological modelling, compressing workflows that used to take months into mere days.
In logistics, the shift is physical. DP World has revolutionised container handling at Jebel Ali with the BoxBay system. As described by Marine Insight, this high-bay storage technology stacks containers up to 11 tiers high in a steel rack, allowing fully automated cranes to access any container without having to reshuffle others. This change increases terminal capacity by 300% and creates a safer, more efficient operating environment.
The GenAI Divide: Enterprises vs. SMEs
While giants like Aramco and DP World forge ahead, the picture for Small and Medium Enterprises (SMEs) is more complex. Project NANDA’s 2025 research highlights a “GenAI Divide,” revealing that while 95% of organisations are investing in AI, only 5% are extracting significant value.
For SMEs, the barriers are talent and infrastructure. However, the rise of Low-Code/No-Code platforms is providing a bridge. As reported by Gulf News, Zoho has seen 50% growth in the region, driven by businesses modernising legacy systems without the need for expensive engineering teams.
To further support this sector, the Saudi SME Bank launched Phase II of its Agency Model in 2025. By partnering with crowdfunding platforms like Manafa and Lendo, they have allocated SAR 240 million specifically to finance SME growth and digital transformation.
The Future of Work: A Divergent Path
The impact on the job market is profound. The World Economic Forum’s “Future of Jobs 2025” report predicts a divergent effect: while routine roles in administration and manual labour are declining, demand for AI and big data specialists is surging.
In the GCC, this dynamic intersects with nationalisation agendas. Governments are using AI to solve the skills mismatch. The Massar Al Ghurair platform, launched in the UAE in 2025, uses AI algorithms to match Emirati youth with career paths and upskilling opportunities. By automating career counselling and recruitment, the region aims to replace low-skilled expatriate labour with high-skilled local talent.
Looking Ahead to 2026
As we look toward 2026, the focus will shift from adoption to governance and integration. Gartner forecasts that IT spending in the MENA region will reach $169 billion in 2026, an 8.9% increase mainly driven by AI infrastructure.
We can expect the realisation of “Cognitive Cities.” In Saudi Arabia, NEOM is moving from earthworks to deploying a cognitive operating system that predicts resident needs. Meanwhile, Dubai’s Cashless Strategy aims to have 90% of all transactions be digital by 2026, creating a data-rich environment for further autonomous innovation.
The year 2025 was the year the machines started to think. The year 2026 will be the year we learn to live and work alongside them.
Dr Ryad Soobhany, Deputy Academic Head of School of Mathematical & Computer Sciences, Heriot-Watt University Dubai
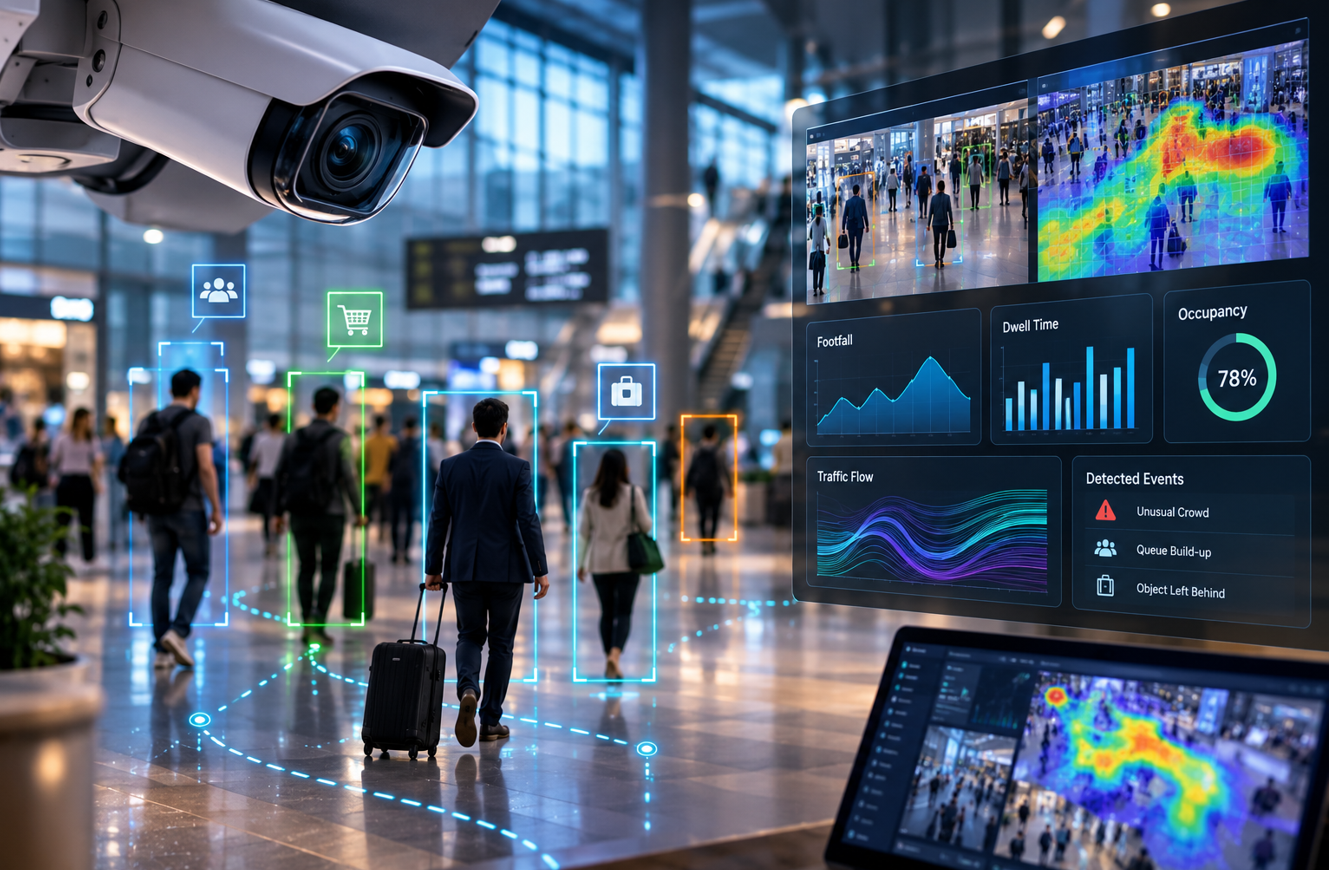
Camera systems, such as CCTV, are mainly used for video surveillance within organisations. Passive video surveillance has been part of the security ecosystem for years, providing organisations with the ability to monitor different areas simultaneously, while recorded footage can be inspected after an event occurs.
The evolution of computer chips and increased processing power has led to improved image quality, including better performance in low-light conditions, particularly at night. The advent of edge computing, with processing performed on edge devices within a network, has made object and scene recognition more readily accessible. This evolution has led to more active video surveillance through video analytics, where events can be identified and addressed in real time. Examples include number plate recognition systems and facial recognition for access control.
With the combination of AI and video data, computer vision can be integrated with business analytics to transform video surveillance from a security infrastructure into a business intelligence tool. Video surveillance is moving from passively recording events to sensing what is happening in the environment. This helps to answer questions such as which areas are congested, how customers are moving, how long they dwell in particular areas, and whether unusual events are occurring. Businesses can use this data to optimise their operations, such as improving the customer checkout process, monitoring asset or staff movement, and managing crowds or traffic flows. Organisations can also incorporate contextual business information to enhance the analytics by combining behavioural data with CRM or IoT data, providing additional context and insights for decision-making and improving the customer or visitor experience.
Video surveillance can be used to optimise operations, improve customer experiences, and support strategic decision-making across industries. Video itself does not create business intelligence; rather, its value increases when visual information is combined with other operational and contextual data, while computer vision is used to understand and enhance business operations. The pipeline from video to business intelligence can be represented as obtaining data from video sources such as fixed cameras, IoT-enabled cameras, or robots. Computer vision is then applied to the video to detect or track people, objects of interest, or activities. Behavioural data are taken into account, such as customer dwell time in particular product areas, occupancy of rooms or halls, movement of people across a building, and anomalies in behaviour. At this stage, operational data are also considered. The final stage is the business intelligence stage, where trends are identified and insights are inferred. At this stage, data visualisation plays an important role, with dashboards and data storytelling displaying correlations, predictions, and infographics that provide more than simple visual summaries of surveillance data. The camera becomes an operational sensor for the organisation. The important transformation occurs when visual data are combined with business data, such as sales, operational, and IoT data, to convert visual observations into business knowledge that informs operational, tactical, and strategic decision-making within an organisation.
The levels of business intelligence can be viewed as three analytical capabilities: descriptive intelligence, diagnostic intelligence, and combined predictive and prescriptive intelligence. Descriptive intelligence usually addresses what is happening. Visual analytics can identify footfall, occupancy, queue length, waiting time, dwell time, traffic flow, movement patterns, and detected events. Visualisation dashboards can present these indicators in real time or over historical periods, allowing managers to understand the current state of an operation. For example, a museum dashboard can show heat maps of visitor numbers, dwell time, and movement across different exhibition areas, while analysing visitor behaviour and providing insights into the optimal placement of exhibitions. An airport dashboard could display passenger volumes and queue lengths across terminals.
By Julio de Salvo, Chief Solution Officer for MENA & APAC at Globant
For decades, the financial industry has managed to replace banknotes and coins with “invisible” assets through different technological implementations. However, innovation in the sector has generally moved at a slow pace when dealing with something as sensitive as people’s finances. In 2026, the black swan is beginning to emerge: the first steps of AI agents that will redefine the industry (as they will many others). The financial black swan is not a crisis: it is a huge change. Across the Middle East and Africa, where a convergence of government-backed modernization agendas, digitally native consumers, and institutional ambition is accelerating the timeline for transformation.
The first step has been the use of Gen AI without the customer perceiving it. Coding, fraud prevention, phishing detection, and credit assessment are some of its tasks. But it is now beginning to become a tool for managing users’ finances. In the MENA region, this shift is already visible at the institutional level. Across the 25 MEA banks benchmarked by the Evident AI Index (June 2026), the established leaders are no longer running pilots, they are directing investment toward high-friction processes where AI can materially reshape productivity, scalability, and competitiveness. UAE-based banks and fintechs are already validating agent-initiated transaction pipelines in production environments. These are some of the examples, but there are more.
In July 2026, the revealing Mills Review, published by the FCA (Financial Conduct Authority), the UK’s official financial regulator, pointed out that AI agents will become the new financial interface. Essentially, an AI assistant will manage budgets, answer queries, generate reports on demand, and move money between accounts. How much was spent on a vacation in total, how a stock portfolio performed over the past month, or canceling an annual subscription will be as easy as making a query to ChatGPT today. For MENA consumers, who have in many cases leapfrogged legacy banking behaviors entirely, this vision is the baseline expectation.
The Mills Review also argues that Open Banking will evolve toward a model in which AI agents will have access to a broader range of financial products to enable intelligent decisions across different areas, and highlighted that this will lead to an evolution in regulation. In the GCC, this evolution is being actively shaped by regulators and governments alike, with initiatives such as Dubai’s target of 90%+ digital transactions by 2026 signaling not just ambition, but structural commitment to a cashless, AI-enabled financial ecosystem.
The agentic AI opportunity in the region is real, but it remains underexploited. According to EY-Parthenon’s 2025 Generative AI in Banking Survey, 99% of respondents are familiar with agentic AI, yet only 31% have pursued implementation, with a further 46% expressing interest. Awareness, in other words, has raced ahead of execution. This gap between recognition and production-grade deployment is precisely where the competitive battle will be won or lost.
This represents a major shift in the industry, where historically the leading banks have, for the most part, remained the same. Differentiation can now change everything, and it would not be surprising if new players manage to break into the ranks of the world’s most important financial institutions. In the Middle East, the region’s financial landscape already includes a new generation of digital-first challengers sitting alongside heritage institutions, all of which are now actively exploring or deploying agentic capabilities. The reason sounds obvious when explained: if the experience with an AI assistant can manage customers’ money better, it will prevail. This is not an exaggeration: just four years ago, nobody knew ChatGPT, and now we have become so accustomed to it that we all ask ourselves: why shouldn’t I manage my assets with a chatbot that can provide reports and recommendations? A study by JPMorgan found that half of Gen Z wanted to use them to manage their finances.
The infrastructure for agentic commerce is also being built in real time across the GCC. Mastercard has conducted regional pilots in partnership with Majid Al Futtaim, enabling consumers to search, select, and purchase VOX Cinema tickets programmatically through an integrated AI assistant. In May 2026, Visa launched its global Agentic Ready program in the UAE, with early adopters including ADCB, ADIB, Emirates NBD, Mashreq, Tabby, Wio, and Ziina already validating agent-initiated transaction pipelines in production.
We are living in a time of change. In its 2026 report on the financial sector, the World Economic Forum urged organizations to move with “urgency” and “discipline”. The greatest benefits, it stated, will go to those working on a holistic redesign of workflows and technology architecture. In the MENA region, the conditions for genuine transformation are already in place: strong institutional will, government-aligned modernization agendas, and a consumer base that has leapfrogged legacy behaviors entirely.
One of the major questions is why, if the financial sector has such a strong technological tradition, the emergence of AI Agents represents a black swan. There are several reasons. First, historically, customers used banks to execute transactions; therefore, in the executive conversations avoiding risk was prioritized over innovation. This is changing with the emergence of digital banks, which are generally more inclined toward disruption, and shifts in consumer habits. In the GCC specifically, consumers who bypassed branch banking and moved directly to mobile-first financial services are now primed to embrace AI-managed financial experiences with little friction. The challenge of the future is not to provide a tool, but to redesign experiences to address this transition comprehensively. AI has the potential to resolve the technological debt involved in migrating traditional banks, which have historically struggled the most with this transition.
The second reason is the technical debt banks have demonstrated in dealing with change. This has also occurred in other industries, but the idea of paying for a premium license for every employee and expecting immediate returns only leads to frustration. There is significant resistance when it becomes clear that certain tasks and workflows will inevitably be different from what has been established. In the Middle East, where several national banks have invested heavily in core banking modernization programs over the past decade, the foundations are more favorable than in many Western markets, but the final leap from modernized infrastructure to genuinely agentic deployment still requires focused capability and deliberate execution.
The third reason is regulation. Technology companies, banks, and authorities will need to maintain an ongoing dialogue to ensure that innovation and integrations do not affect users’ personal data or security, while ensuring that restrictions do not become a barrier to progress. One of the most valuable lessons from the banking sector’s legacy is the importance of being extremely careful when dealing with something as sensitive as people’s money.
For many years, the impact of AI was often explained as something that belonged to a distant future. In the financial sector, it is already a reality: it is part of multiple tasks and is beginning to become an asset in the customer proposition. With AI Agents, innovation can no longer, and should no longer, go unnoticed. New habits require the redesign of customer journeys, and this could represent a revolution for the sector. For Middle East banks, the opportunity is particularly compelling: a region where government will, consumer readiness, regulatory pragmatism, and institutional investment have aligned at the same moment. What is required now is the execution capability to convert that alignment into production-grade deployment. What is at stake is no small matter: the management of millions of people’s money and a battle for the competitiveness of banks on a scale rarely seen before. For those that move with urgency and discipline, the financial black swan is a transformation to be led.
By: Debo Zhang, CEO at HONOR GCC
In the hyper-competitive consumer technology sector, the launch of a flagship device is often treated as the finish line. However, true brand leadership is forged not in the showroom, but in the months and years that follow. At HONOR, we view the point of purchase not as a conclusion, but as day one of a long-term partnership with our users.
As we aggressively push the boundaries of intelligent hardware—from integrating Agentic OS to setting new benchmarks in physical durability and battery density—we recognize that advanced specifications represent only half of the premium equation. The other half is an unyielding commitment to the customer’s lifecycle experience. If a brand fails to support its users when they need it most, the underlying technological advancements lose their meaning.
Operationalizing Community Care
Our commitment to giving back to the GCC community dictates our operational investments. We do not just build resilient devices; we build resilient support networks designed to remove the friction of long-term ownership. Our recurring monthly Service Days are not promotional events—they are structural community investments.
By deliberately absorbing operational costs—such as completely waiving labor fees for expert repairs and offering complimentary professional device cleaning and disinfection—we ensure that maintaining a premium device remains accessible. We view ongoing device care, including free system upgrades and screen film replacements, as a fundamental responsibility rather than a secondary revenue stream.
Respecting the User’s Time and Individuality
True leadership in customer service also requires a profound respect for the user’s time and individuality. Recognizing that our customers’ lives are deeply integrated with their technology, we have designed our after-sales operations to adapt to the user, rather than forcing the user to adapt to us. Offering complimentary return shipping for repairs and providing complimentary gifts when repair timelines are extended are direct measures to eliminate inconvenience.
Furthermore, we understand that a smart device is a highly personal extension of the user. Incorporating free laser engraving and custom art back films into our regular service offerings transforms a standard maintenance visit into an opportunity for users to refresh and personalize their technology.
As the Middle East accelerates its digital transformation, consumers are demanding more than just innovation; they demand reliability, accountability, and respect. HONOR’s rapid growth across the region proves a fundamental business truth: when a technology brand prioritizes post-purchase empowerment and community care over short-term transactional gains, sustainable market leadership naturally follows.

U by Emaar and Visa Announce 10-Year Partnership to Elevate Lifestyle Rewards
THE LAST HARVEST – Using precious little olive oil from Gaza to preserve hope for the next harvest.

LOONA Introduces Interactive La Fortuna Ravioli Dining Concept


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR10 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai