 Have a question? +971 56 404 0503

Financial
National Bank of Fujairah (NBF) partners with Intellect for its eMACH.ai Cloud for Wholesale Banking on Microsoft Azure


Intellect Global Transaction Banking (iGTB), the transaction banking business unit from Intellect Design Arena Ltd is proud to announce its partnership with National Bank of Fujairah (NBF) to enhance its digital capabilities. This deal marks the first Microsoft Azure-managed service for Intellect’s eMACH.ai Cloud for Wholesale Banking in the Middle East.
NBF currently serves corporates and SMEs through its network in the UAE, providing financial services to optimise commercial opportunities and achieve sustainable growth for their clients. With the eMach.ai Digital Transaction Banking solution, NBF can offer their clients a suite of comprehensive solutions backed by:
- Innovative decision-making and enhanced digital capabilities: For improved information visibility and innovation, ensuring quick decision-making and a seamless user experience for corporate and SME clients.
- Cloud-powered excellence: iGTB, with Microsoft Azure, will provide a fully managed cloud service, freeing NBF to focus on business development and client service.
Commenting upon the partnership, Adnan Anwar, CEO, National Bank of Fujairah said, “NBF as part of its customer experience and digitalisation strategy is adopting full-fledged cloud solutions for mission-critical applications in the wholesale banking space. Through this partnership with iGTB and Microsoft, implementing their comprehensive DTB solution on Azure Cloud will position us to revolutionise our digital banking capabilities, delivering unparalleled experience and security to our clients. “
He added, “NBF is establishing a robust foundation for the integration of the latest emerging technologies, including AI, ensuring a future-ready organisation. As the UAE’s bank of choice for over 40 years, this partnership highlights NBF’s dedication to innovation and customer-centricity, as we continue to lead advancements that empower our clients and drive growth in the digital age.”
Manish Maakan, CEO of iGTB commented, “By selecting Intellect Global Transaction Banking, NBF has chosen a strategic technology partner that offers scalability, operational efficiency, and the ability to grow alongside its wholesale business. NBF’s commitment to advancing its transaction banking infrastructure reflects the critical role of technology to drive growth and innovation in wholesale banking.”
He added, “This is our first deal to be hosted on eMACH.ai cloud for wholesale banking on Microsoft Azure in the Middle East, and is a significant step in the region’s digital banking landscape. Today, over 60% of the world’s best wholesale banks #winwithiGTB, and this deal signifies a pivotal step in cementing iGTB’s leadership position within the UAE & GCC market, underscoring our dedication to offering leading-edge digital banking solutions.”
Patrice Amann, EMEA Regional Business Lead – WW Financial Services, Microsoft said, “iGTB Cash Management on Azure provides a robust platform for banks to streamline and modernise their transaction banking business in the cloud. We look forward to working with Intellect Design Arena to help accelerate National Bank of Fujairah’s digital transformation journey on Azure.”






By Arash Jalali | Venture Builder | Revona
Most people hear the word “debt” and think of stress, bankruptcy and sleepless nights. It is the villain of personal-finance books and the scapegoat of every economic crisis. But after years of building ventures and, at Revona, structuring financing for developers and corporates every day, I have come to see debt very differently.
Debt is not merely a burden to be minimised. It is one of the most elegant, powerful and, yes, contradictory ideas humanity has ever invented.
That distinction matters especially now. Higher rates have made the cost of debt more visible, while a wall of maturities is turning yesterday’s cheap money into tomorrow’s refinancing decision. The response should not be to romanticise leverage. It should be to become more exacting about the work debt is asked to do.
Debt Is Older Than Money Itself
Long before coins and banknotes, communities ran on credit: promises recorded on clay tablets and in shared memory. Debt is, at its core, a technology for moving value through time. It lets tomorrow’s income fund today’s ambition. When a developer borrows to build a tower, or a founder raises venture debt to extend runway, they are pulling the future forward. That is not recklessness; it is one mechanism through which economies compound.
But the debt debate often starts in the wrong place. There is no magic ratio at which prudent borrowing becomes recklessness. A debt ratio is a snapshot; the real story is what the money is financing, whether cash flow can carry it and whether the borrower has time to adapt when conditions change. That is why the quality of the investment, the maturity profile and the resilience of the balance sheet matter more than the headline number alone.
In the architecture of the modern economy, debt does something even more subtle. It reduces the cost of financial oversight, helps create money through the banking system and smooths the path of economic growth. Every mortgage, every credit facility and every bond issue is a small act of coordinated trust between strangers. Trust, priced and packaged, is what capital markets actually trade.
The Debt That Never Dies
The numbers tell a more precise story than the usual rhetoric. Global debt reached a record nearly $353 trillion by the end of March 2026, according to the Institute of International Finance. That figure covers public, corporate and household debt. At the same time, the global debt-to-GDP ratio stood at about 305%, broadly stable since 2023. A record stock of debt, in other words, does not by itself tell us whether borrowers can carry it; the relationship between liabilities, income, assets and refinancing capacity does.
Nor should a stable global aggregate be mistaken for an all-clear. The IIF reported that debt in mature markets edged lower in the first quarter, while debt in emerging markets excluding China rose to a record $36.8 trillion. Debt is never one homogeneous thing. Its burden depends on who owes it, in what currency, at what rate, for how long, and against which cash flows.
The immediate market test is refinancing. The OECD expects governments and companies to borrow $29 trillion from bond markets in 2026 — 17% more than in 2024 and roughly double the amount ten years ago. Much of that activity is not fresh expansion; it is the constant work of renewing obligations. The OECD estimates that 78% of OECD government borrowing in 2026 will refinance existing debt. That is why the calendar can matter as much as the headline debt total.
The U.S. Lesson: Borrowing Can Stabilise Growth
The United States makes the point in unusually stark terms. The Office of Management and Budget’s fiscal-year-end measure of federal debt held by the public — the debt outside federal government accounts — rose from 25.2% of GDP in FY1981 to 99.5% in FY2025.
That is a profound change, but it was not a straight line and it cannot be explained by one White House. The ratio fell from 46.8% in FY1992 to 33.7% in FY2000, then rose through the financial crisis and jumped during the pandemic. The chart shows presidential terms as chronology, not as a scorecard: a fiscal year spans two calendar years, and debt reflects Congress, inherited commitments, recessions, interest costs and emergencies as well as executive choices.
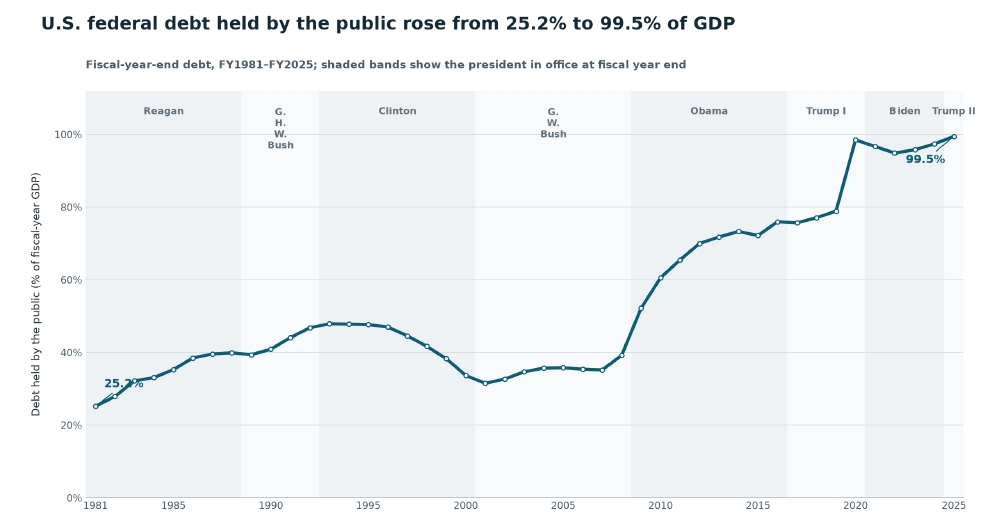
Figure 1. U.S. federal debt held by the public as a share of fiscal-year GDP. Source: Office of Management and Budget, Historical Tables, Table 7.1 (FY2027 release). Debt is measured at fiscal-year end. Administration bands identify the president in office on that date; they do not attribute causation.
The more useful lesson is not that a larger debt stock automatically produces prosperity. It is that, when private demand collapses, borrowing can prevent a deeper contraction. The Congressional Budget Office estimated that the major pandemic laws enacted in 2020 increased real GDP by 4.7% in 2020 and 3.1% in 2021, relative to an implied no-legislation baseline.
That is a concrete example of debt financing acting as a bridge: preserving household income, business liquidity and state and local services at a moment when the alternative was a sharper fall in economic activity.
But bridges must lead somewhere. CBO also projected that the additional debt would raise borrowing costs and reduce output and national income over the longer term. The point is not to celebrate the size of the U.S. debt pile. It is to recognise that borrowing can be a positive driver of growth when it is targeted at a productive investment or a defined emergency — and that its value erodes when cash flows, repayment capacity and the economic return are treated as afterthoughts.
The Beautiful Contradiction
Debt is a paradox, and that is precisely what makes it beautiful. It is simultaneously:
| Debt as… | For whom |
|---|---|
| An asset | The lender, bondholder or pension fund earning a contractual return. |
| A liability | The borrower who must service and ultimately repay it. |
| An engine of growth | The developer, founder or economy that applies it to a productive opportunity. |
| A source of crisis | Anyone who mistakes leverage for a substitute for fundamentals. |
The same instrument that funds a hospital can sink a household. The same leverage that lets a developer sell units before completion can, if mispriced, freeze an entire market. Debt does not care about intentions; it amplifies what is already there. Good projects can become great. Weak projects can fail faster. That amplification is the whole point.
The Revona Angle: Debt as Craft, Not Gamble
This is exactly where Revona operates, and why I find this space so compelling as a builder. If debt is a powerful but indifferent amplifier, the real value lies not in whether a client borrows, but in how the debt is engineered: the rate, the loan-to-value, the tenor, the covenants and the match between an asset’s cash flows and the facility that finances it.
Those are not cosmetic details. A lower headline rate can be a poor bargain if it comes with a refinancing date that arrives before the asset can reliably generate cash. A high loan-to-value ratio may look efficient until a change in valuations removes the borrower’s room for error. A fixed rate can buy time, but it does not eliminate the economics of refinancing.
That final distinction is becoming more important. The Federal Reserve reported in 2025 that long-term, fixed-rate liabilities had softened the initial pass-through of higher rates for large public companies. Yet about 15% of investment-grade bonds and 27% of high-yield bonds were due to mature within one to three years. The protection was real; it was also time-limited.
The OECD has similarly warned that, as higher long-term rates lead borrowers to issue at shorter maturities, near-term interest costs may fall while near-term refinancing risk rises.
At Revona, we treat financing as a craft. We map a client’s full balance sheet, identify untapped equity and structural inefficiencies, and match their profile against the lending criteria of more than sixty banks and institutions to find the optimal structure, not simply the fastest “yes.”
For developers, well-structured off-plan financing can mean buyers are pre-approved during construction, sales accelerate and project cash flow improves. Debt, structured properly, stops being merely a cost of doing business and becomes a competitive advantage.
The failures we associate with debt — the crashes, defaults and horror stories — are more often failures of structure and underwriting than evidence that debt is inherently flawed. They arise when there is too much leverage against too little cash flow; when short-term money funds long-term assets; when currency, revenue and debt-service obligations do not match; or when no one has stress-tested the downside.
The instrument gets blamed for the craftsmanship.
The Takeaway
Debt is usually framed as financial pressure and bankruptcy risk, but its role in the modern economy runs far deeper. It is a centuries-old technology for turning trust into growth, a nearly $353 trillion river of contractual claims, and a mirror that reflects the discipline — or indiscipline — of whoever wields it.
The world’s most sophisticated companies and governments do not avoid debt. They engineer it. As builders and investors, that should be our posture too: respect the contradiction, master the structure and let leverage do what it was invented to do — move the future forward.
AJ is a venture builder. Revona is a financing partner and portfolio manager providing institutional-grade credit and debt financing solutions for developers and corporates.
Financial
PATRIZIA appoints Hassan Awada as Senior Executive Officer to lead and accelerate Middle East expansion
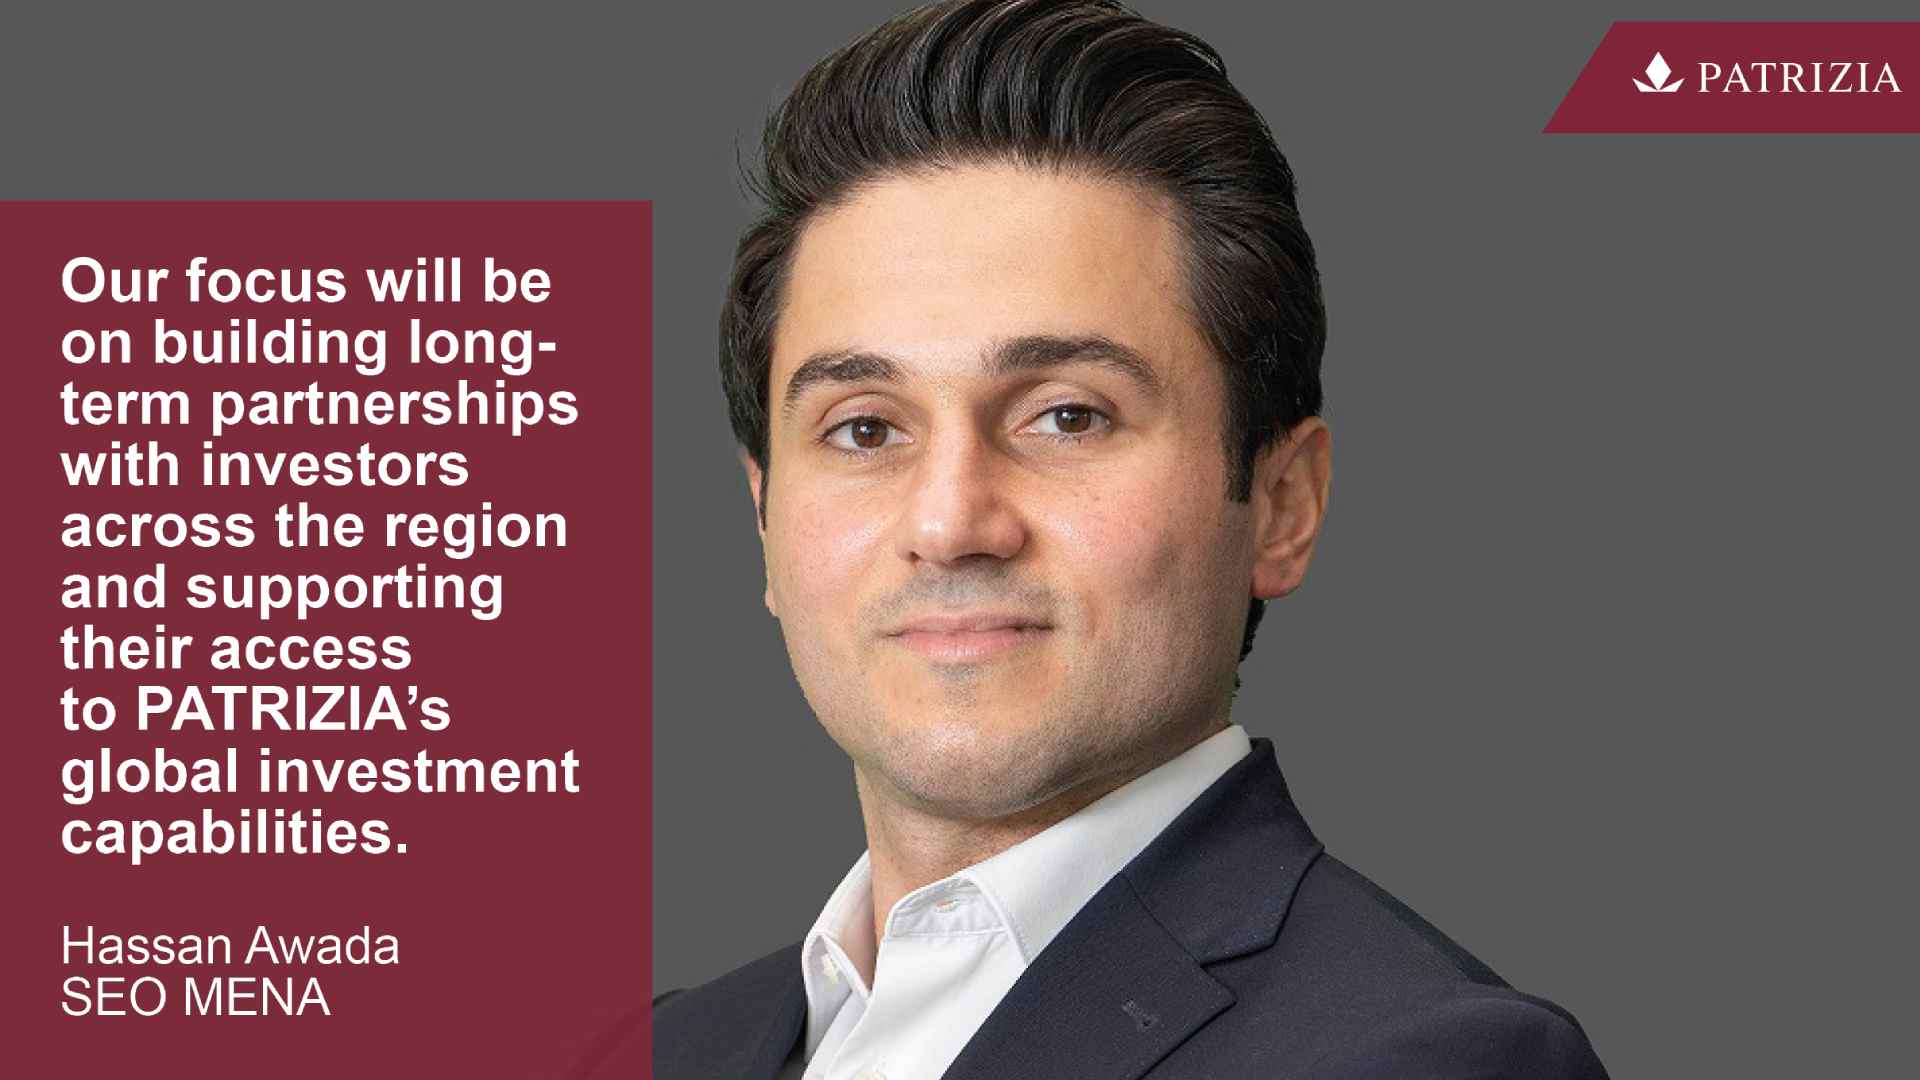
PATRIZIA, a global investment manager in real assets, has announced the appointment Hassan Awada as Senior Executive Officer (SEO), MENA. Based in ADGM, the international financial centre of the UAE’s capital, Abu Dhabi, Awada will lead the continued growth of PATRIZIA’s business across the MENA region, with a focus on deepening relationships with institutional investors and strategic partners and providing access to PATRIZIA’s international real assets investment platform.
Awada brings over 20 years of experience advising institutional investors across the full investment lifecycle, including origination, structuring, execution and asset management. Prior to joining PATRIZIA, he held senior roles at Kroll, Cornerstone Capital, Gleacher Shacklock, PwC and EY.
Konrad Finkenzeller, Head of Client Division at PATRIZIA, commented: “The Middle East is a key strategic region for PATRIZIA, and we continue to see strong demand from investors for direct exposure to high-quality real estate and infrastructure opportunities globally. Hassan’s appointment strengthens our presence on the ground and enhances our ability to deepen relationships with regional investors and connect them with PATRIZIA’s global investment platform.”
Hassan Awada, SEO MENA at PATRIZIA, added: “Real assets have long underpinned Middle Eastern economies and will continue to play a central role in the region’s growth. Meeting increasingly sophisticated investor needs requires tailored, strategic solutions. With its global platform and 42-year track record, PATRIZIA is well positioned to deliver. Our focus will be on building long-term partnerships with investors across the region and supporting their access to PATRIZIA’s global investment capabilities, aligned with their strategic priorities and long-term objectives.”
Arvind Ramamurthy, Chief Market Development Officer, ADGM, said: “This appointment reflects the firm’s strong growth trajectory in the Middle East and its commitment to expanding from Abu Dhabi. It also underscores ADGM’s role as a leading international financial centre, enabling firms to establish and scale their regional presence from the capital.”
With EUR 17.5 billion in Living assets under management, PATRIZIA is one of Europe’s largest residential investment managers and continues to grow its platform across major urban markets. The firm is currently delivering new housing across a number of European markets, including Germany, UK & Ireland, Spain and Belgium, reflecting the scale of its European platform. Alongside Living, PATRIZIA is expanding its infrastructure platform across energy, digital and smart city assets, supporting the transition to low-carbon and connected economies while delivering long-term, resilient returns for investors.
Financial
Fimple adds five GCC financial institutions in first year, targets doubling regional customer base
Fimple, an AI-native, API-first, composable financial platform, has signed five financial institutions across the GCC within its first year in the region and plans to double its regional customer base.
Fimple established its Dubai presence in October 2025 and has grown from zero to five GCC customers in 12 months. The region now accounts for close to a fifth of its global customer base of more than 35 financial institutions across 10 countries, making it the company’s fastest-growing region.
The company has also opened an office in Riyadh and plans to expand its customer and delivery presence across the GCC, serving institutions with teams based within the region.
Fimple’s regional growth comes as the UAE continues to advance its ambitions across Islamic finance and financial technology. Under the UAE Strategy for Islamic Finance and Halal Industry, the country aims to increase local Islamic bank assets from AED 986 billion to AED 2.56 trillion by 2031. (Source: UAECabinet.ae)
Dubai is also advancing its ambitions in AI-enabled financial services, with the Dubai International Financial Centre (DIFC) announcing plans in 2026 to become the world’s first AI-native financial centre. (Source: Dubai Media Office/DIFC)
“The UAE is an important market for Fimple because financial institutions here are moving quickly on both Islamic finance and new technology,” said Amr Kandel, GCC Country Manager and Product Director at Fimple. “Banks want to launch products faster, respond to local market needs and modernise without having to change everything at once. The growth we’ve seen in our first year shows there is real appetite for that.”
Islamic finance is a key driver of Fimple’s growth in the GCC. The platform enables financial institutions to run conventional and Islamic finance within the same system, with a range of Sharia-compliant financing and investment structures built into its product engine.
Fimple’s regional customers include Mawarid Finance, a UAE Islamic finance provider that entered into a strategic agreement with Fimple in June 2026.
As banks look to move AI from pilot projects into wider use, Fimple says the underlying core banking infrastructure is becoming increasingly important.
“Banks are already experimenting with AI, but the systems underneath need to be ready for it,” Kandel said. “If the core can’t provide the right data or connect easily with new technology, AI can get stuck at the pilot stage. That’s why the core matters.”
Fimple has built three banking AI agents covering independent audit report processing, customer intelligence from official notices and risk screening across official sources. The agents operate on the Fimple platform with human approval required for each action and full traceability. Further agents are planned as part of the company’s 2026–2027 roadmap.
According to Fimple, it implements a full working core in three to six months on average. Its composable architecture also enables financial institutions to connect selected modules to existing systems rather than replacing their entire core infrastructure at once.
“The GCC has become our fastest-growing region in just one year, and we expect to double our customer base here,” said Mücahit Gündebahar, CEO and Co-founder of Fimple. “We are growing our team and presence in the region so we can support customers locally as we expand across the GCC.”
Fimple will participate as a Gold Sponsor of Seamless Middle East 2026, taking place from Sept. 22–24 at Dubai World Trade Centre. The company will exhibit at stand G64, with Kandel delivering the session “Beyond the AI Hype: Why the Future of Banking Depends on an AI-Ready Core” on Sept. 23 at Stage 1, Fintech Forum.

Datadobi Adds Data Access Governance to StorageMAP, Enabling Enterprises to Answer the Critical Question: “Who Has Access to What?”

Why Debt, Despite All Its Contradictions, Is One of the Most Beautiful Ideas in Finance

Turkish Airlines Finalizes Order for up to 150 Boeing 737 MAX Aircraft


-
News11 years ago
SENDQUICK (TALARIAX) INTRODUCES SQOOPE – THE BREAKTHROUGH IN MOBILE MESSAGING
-
 Trending11 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR1 year ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-
 Tech News2 years ago
Toshiba Announces MG10-D Series of Enterprise HDDs with Capacities up to 10TB
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai