 Have a question? +971 56 404 0503

Financial
FOUR DISCIPLINES UAE BOARDS NEED BEFORE E-INVOICING GOES LIVE

Amit Dua, President, SunTec Business Solutions
E-invoicing in the UAE is no longer a distant policy idea; it is a dated commitment. From July 2026, the Federal Tax Authority (FTA) will begin the first mandatory phase of a national e-invoicing regime, with larger taxpayers required to comply from January 2027 and smaller businesses following later that year. Penalties of up to AED 5,000 per violation have already been announced for non-compliance.
This is happening against the backdrop of a fast-expanding non-oil economy. At the same time, artificial intelligence is projected to contribute close to 14 percent of UAE GDP by 2030, the highest relative impact in the region.
In such an environment, e-invoicing is not a narrow tax exercise. It is a test of whether companies can manage real-time regulatory obligations while improving the speed, integrity, and usefulness of their financial data. Firms that treat it as another compliance chore will scramble to catch up. Those that approach it as a strategic capability will emerge with cleaner processes, faster cash conversion, and better insight into how their businesses actually work.
Four disciplines, in particular, will separate the merely compliant from the genuinely prepared.
1. Start by really understanding the new rulebook
The first discipline sounds obvious but is frequently ignored: know the rules in detail. Under the UAE framework, an invoice will no longer be a PDF attachment travelling quietly from seller to buyer. It will be a structured data packet, typically in XML, and in some cases JSON, that must be generated by the supplier’s systems, routed through an accredited service provider operating on the Peppol five-corner model, and delivered simultaneously to the buyer and to the FTA.
This architecture is deliberately more complex than the old email-and-attachment world. Each invoice must pass schema checks, integrity checks, and business-rule validations before it is accepted as a tax-compliant document. The FTA will then use the incoming data stream to pre-populate returns, reconcile declarations with actual invoice flows, and flag discrepancies almost in real time.
There is also a long tail of procedural obligations. Businesses must understand which transactions fall within scope in each phase, how credit notes and cancellations will be handled, how to deal with cross-border supplies, and which exemptions, if any, apply to their sector. Beneath all of this sits a familiar but often neglected requirement: record-keeping. UAE tax law already obliges businesses to retain accounting records, including tax invoices, for at least five years after the end of the relevant tax period, with longer periods for certain assets and real estate. E-invoicing will not replace this obligation; it will tighten it, because the Authority will have its own copy of every invoice.
Companies that only half-understand this rulebook will find themselves constantly reacting to surprises. The ones that invest early in a precise, shared understanding, across finance, tax, IT and operations, will be able to design systems and processes that meet the requirements without strangling the business.
2. Redesign the systems, not just patch them
The second discipline is technical, but it cannot be delegated entirely to IT. Large and mid-sized UAE businesses typically run a patchwork of ERPs, billing engines, and industry-specific platforms. Many were built for a world where an “invoice” was whatever the system could print. They were not designed to produce standardized, structured e-invoices or to connect to a Peppol-based network in which every document is validated by an external access point before it counts.
Trying to bolt e-invoicing on to this kind of landscape in the last quarter of 2026 would be professionally reckless. Boards must insist on a hard-headed mapping of how invoices are currently created, routed, approved, and stored.
The UAE framework gives firms some architectural freedom. They can consolidate invoice generation in a central “hub” that talks to multiple access points, or they can adopt a more decentralized model with business-unit-specific systems feeding into a common provider. But there are hard deadlines. Large taxpayers with annual revenues above AED 50 million must appoint an accredited service provider by 31 July 2026 and go live with e-invoicing by 1 January 2027; smaller taxpayers follow six months later, with their own appointment and go-live dates in 2027.
Accredited service providers themselves face strict requirements on uptime, performance, and information security. Many must demonstrate ISO/IEC 27001-level controls and keep pace with evolving FTA specifications. Choosing one in a hurry, without proper due diligence on their scalability and roadmap, will store up trouble. The more disciplined approach is to treat system redesign as a staged program: clean up master data, rationalize templates, decide which systems are sources of truth and which are consumers, and only then build or buy the integration layer that connects to the Peppol network.
3. Train the organization for real-time tax
The third discipline is organizational. E-invoicing looks, at first glance, like a back-office affair. In reality, it will touch sales, procurement, operations, customer service, and even treasury. Every group that raises, approves, disputes or chases an invoice will have to change behavior.
In markets that have already implemented similar regimes, many of the worst early-stage problems had little to do with software. They arose from people trying to work around the new rules. Sales teams promised bespoke formats or unusual discount structures that the system could not express in a valid e-invoice. Shared service centers reverted to spreadsheets when confronted with a new edge case. Managers asked IT to “override” rejections to recognize revenue faster, undermining both controls and audit trails.
The UAE will not be an exception. Training cannot be limited to a single webinar or a set of user manuals. Front-line staff need to understand what makes an invoice “real” in the new world, which fields are non-negotiable, and what to do when an invoice fails validation. Middle managers need to know how to interpret new exception reports and how to balance commercial pressures with compliance obligations. Senior leadership needs a clear view of key metrics such as rejection rates, average time from issue to acceptance, and the volume of manual interventions as leading indicators of whether the new regime is bedding in or beginning to buckle.
The most effective organizations are already running “shadow” or pilot cycles, issuing e-invoices alongside traditional ones and using the results to refine processes ahead of the legal deadlines. That kind of rehearsal requires coordination, and coordination requires visible sponsorship. When the CEO, CFO and CIO jointly own e-invoicing, it becomes a transformation initiative. When it is dumped quietly into the IT work queue, it becomes an expensive troubleshooting exercise.
4. Treat data, security, and retention as strategic infrastructure
The fourth discipline goes beyond the launch date. E-invoicing will generate one of the richest, most sensitive data streams in a business. Each invoice reveals who is paying whom, on what terms, for what goods or services, and under what tax treatment. In the UAE’s Peppol-based five-corner model, this data will flow more widely than before, passing through access points and central systems on its way to the FTA.
Regulators have attempted to pre-empt security concerns. Accredited providers must meet rigorous information-security standards, and the technical specifications call for encryption, digital signatures and auditable logs. But no external standard can compensate for weak internal governance. Boards must be asking very basic questions now: who can change tax codes or customer master data; how access rights are granted and revoked; what happens if an access point is compromised or goes offline; and how quickly the company can detect unusual patterns, such as repeated rejections for a particular counterparty.
Record-keeping deserves similar attention. Existing VAT rules already require businesses to retain tax records, including invoices, for at least five years after the end of the relevant tax period, with longer retention periods for some categories. E-invoicing will make it easier to store these records in a structured way, but it also raises the bar. If the Authority holds a copy of every invoice, gaps or inconsistencies in a company’s own archive will be harder to explain.
If managed well, this new data environment is an asset. Structured e-invoice data can give leadership teams a real-time view of receivables, payables, pricing, and discount patterns across business units and geographies.
From four steps to one mindset
The UAE’s e-invoicing mandate will not dominate headlines in the way that new trade agreements or record non-oil trade figures do. Yet, quietly, it will shape how companies in the country bill, collect, report and plan. It is tempting for boards to think of it as a discrete project with a defined end date. In reality, it marks a shift to a more transparent, data-intensive relationship between business and state, one that will continue to evolve as tax rules, digital infrastructure, and trade flows change.
The four disciplines outlined here, understanding the rulebook, redesigning systems, training the organization, and treating data and security as strategic infrastructure, are not an exhaustive checklist. They are, however, a good proxy for mindset. Companies that embrace them are likely to find that e-invoicing improves the quality of their numbers, the speed of their decisions and the robustness of their controls. Those that do not, may meet the letter of the law but miss the larger opportunity.
In a country positioning itself as a global hub for trade and AI-driven digital commerce, e-invoicing is part of the plumbing. As every good engineer knows, the quality of the plumbing determines how much pressure the system can take.
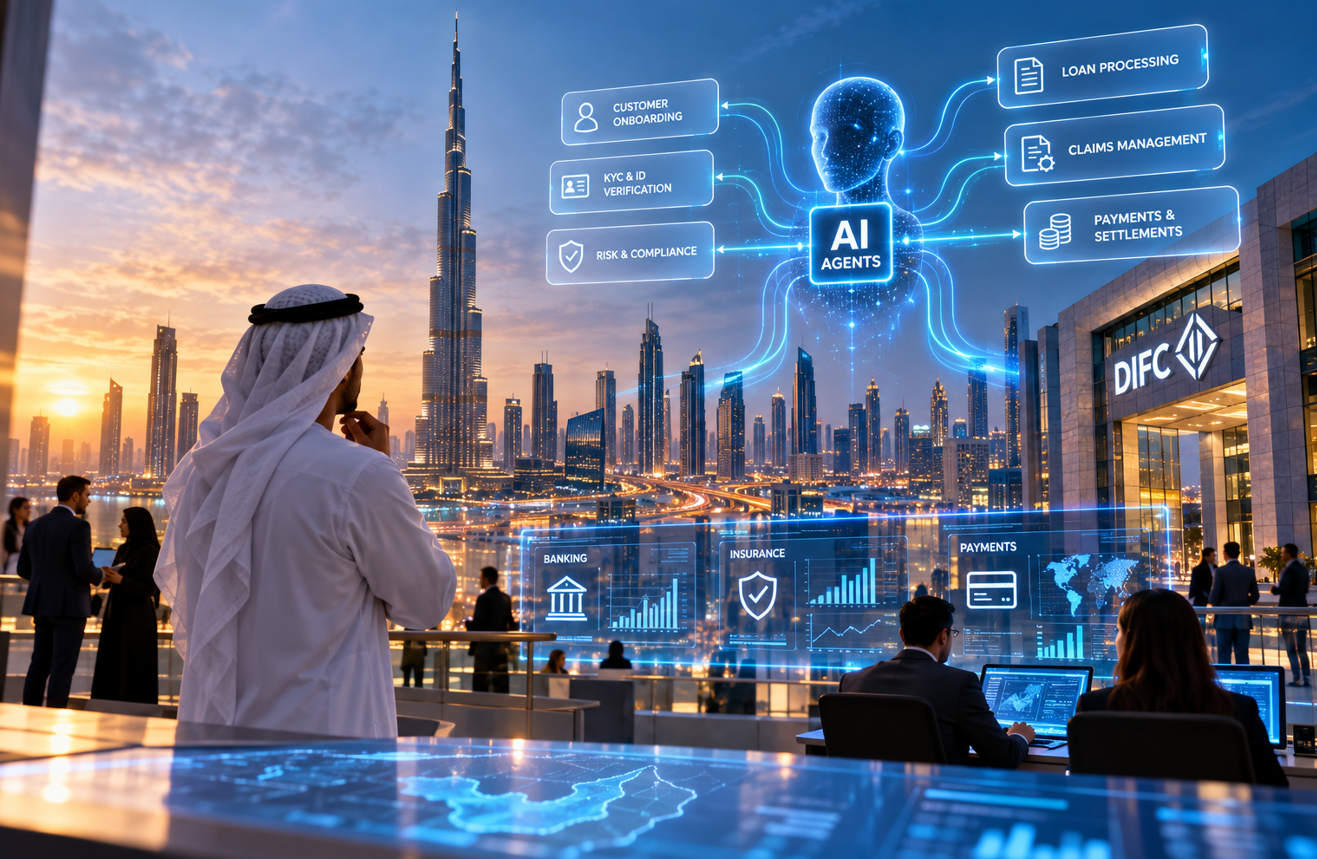
With Dubai fast-tracking agentic AI and AI use among DIFC financial firms rising sharply, Samir Akel, Regional Vice President, Emerging Markets at Nintex, sets out how orchestration turns agentic AI into results for UAE banks and insurers.
This week, much of the region’s technology community has gathered in Abu Dhabi for AI Everything, and the question on the show floor has moved on. A year ago, banks and insurers asked whether to deploy AI agents; today they want to know how to make those agents deliver results across an entire customer journey.
Government is setting the pace. On 5 October, the Dubai Future Foundation launched an agentic AI accelerator covering 33 government entities and more than 300 public-facing use cases, building on the federal target to run half of government services and operations on agentic AI within two years. Few countries have put a number and a deadline on agentic AI. The UAE has done both.
Finance is keeping up. The Dubai Financial Services Authority’s survey of 661 DIFC firms found that 52% now use AI, up from 33% a year earlier, while generative AI use rose by 166%; the regulator also noted that, for many firms, adoption is still at an early stage. UAE finance has AI in many places. The value comes when those pieces work together.
Work in financial services is fragmented
Follow a corporate account opening at a typical UAE bank. The application lands in a portal or a relationship manager’s inbox; documents and identity are checked, sanctions screening runs in a separate tool, a risk team reviews the file, a committee signs it off and operations sets up the account in core banking. That’s six steps, six systems and one waiting customer.
AI agents speed up individual steps: an agent can extract a trade licence in seconds or draft a risk summary in minutes. Then the file sits in a queue for a reviewer who has no idea it is ready. The task gets faster, while the journey stays as slow as its slowest handoff.
That gap is the coordination tax, made up of the hours lost chasing approvals, re-keying data and fielding “where is my application?” calls. In banking, insurance and payments, where one journey can cross half a dozen teams, it is often the largest cost nobody actually measures.
Process is the foundation
Institutions that turn AI into outcomes start by understanding how work actually runs, and regulated firms have a head start here because they already document their processes for supervisors. The task is to map those processes as they really operate (workarounds and exceptions included) and give each step to the right worker.
Steps that must run identically every time, such as sanctions checks and payment releases, suit rules-based workflow. Reading documents and reasoning over unusual cases suit AI agents. Judgement belongs to people. With the Central Bank’s AI guidance for the sector placing clear emphasis on human oversight, deciding where people sit in a process is now part of designing it.
Orchestration makes AI operational
Once the process is clear, orchestration connects it. It coordinates people, systems, data and agents across a whole journey, deciding who or what acts next and routing exceptions to the right person before they become delays.
Think of an airport, where more aircraft add capacity only when air traffic control sequences them. AI agents work in the same way.
For a bank or insurer, orchestration brings one view of every application, claim or payment. Core banking and policy platforms keep their role while work flows between them, and each orchestrated journey becomes a template for the next, so the tenth deployment goes live faster than the first.
A 90-day starting point
Finance can borrow the government’s 90-day rhythm. Pick one journey that crosses at least three systems and two departments, such as SME lending or a motor claim, and map it as it runs today. Count the handoffs and measure the time lost between them; that figure is your coordination tax. Then assign each step to a rule, an agent or a person, orchestrate the whole journey and track time to decision. Reuse what works.
The orchestrators will lead
At the accelerator launch, Digital Dubai’s Director General said the future of digital government depends on an integrated ecosystem that brings expertise, data and capabilities together. The same holds inside every bank.
Over the next year, the number of AI agent use cases across UAE banking and government will grow rapidly. The institutions that pull ahead will be those with a platform to orchestrate and govern those agents, taking them from pilot to production at scale, while keeping people in control. In the AI era, operational advantage belongs to the orchestrators.
Henry Dannell, a specialist cross-border credit adviser, has announced its expansion into the Middle East with the opening of a representative office in Dubai International Financial Centre (DIFC), marking a significant milestone in the firm’s international growth strategy.
The move reflects rising demand for specialist advice among internationally mobile individuals whose financial interests increasingly span multiple jurisdictions, asset classes, and lending structures. As Dubai continues to strengthen its position as a global wealth and investment hub, attracting entrepreneurs, family offices, investors, and high-net-worth individuals from around the world, the complexity of managing wealth across borders has increased significantly. Many of these individuals now live, work, invest, and hold assets internationally, creating borrowing requirements that often extend beyond conventional lending frameworks.
Henry Dannell’s expansion into Dubai is designed to bring the firm’s specialist expertise closer to the region’s growing network of wealth advisers, family offices, tax specialists, legal professionals, and internationally connected clients.
Founded in 2019, Henry Dannell has built a reputation for delivering bespoke credit and lending solutions for clients with highly sophisticated financial circumstances. The firm’s advisers support a broad spectrum of clients, from business owners and entrepreneurs to ultra-high-net-worth individuals, helping them navigate complex borrowing scenarios that frequently involve multiple jurisdictions, unconventional income structures, and international assets. Unlike traditional mortgage providers, Henry Dannell operates as a specialist advisory business focused on structuring tailored credit solutions and working alongside trusted professional advisers to address complex financing requirements.
The establishment of the DIFC representative office represents the first phase of the company’s broader regional growth ambitions and will serve as a hub for relationship-building, market engagement, and collaboration with professional advisory communities across the Middle East.
Kem Kemal, CEO and Co-Founder of Henry Dannell, said: “Over the last decade, we have seen a fundamental shift in how wealth is created, managed, and deployed. Successful individuals are increasingly global in their outlook. They may operate businesses in one country, hold investments in another, and seek opportunities across several markets simultaneously. Yet lending has not always evolved at the same pace.”
He explained that too often, highly accomplished individuals with substantial assets and strong financial positions encounter challenges because their circumstances fall outside conventional frameworks. “Our role is to understand the complete picture and design bespoke solutions that reflect the realities of modern international wealth.”
“Dubai has become one of the most important centers for global capital, entrepreneurship and wealth advisory services,” he added. “Establishing a presence within DIFC allows us to be closer to the professional advisers and internationally connected clients we serve, while strengthening relationships across a region that continues to play an increasingly influential role in global finance.”
With over 165 years of combined industry experience across its advisory team, Henry Dannell has developed specialist expertise across residential, commercial, and specialist lending transactions. Through its Dubai presence, Henry Dannell aims to deepen engagement with the region’s professional advisory ecosystem while contributing to discussions around international wealth, investment, and cross-border financial planning.
Financial
The UAE’s Net Wealth Reaches $3.6 Trillion in 2025 and is Expected to Approach $6 Trillion by 2030, BCG Report Finds

The UAE’s net wealth grew by 12.7% between 2024 and 2025, rising from $3.2 trillion to $3.6 trillion, according to Boston Consulting Group’s (BCG) Global Wealth Report 2026: The Great Reordering. Total Net wealth is forecast to reach $6 trillion by 2030, with a CAGR of 10.6%. This represents an increase of more than $2.3 trillion over the next five years. The projected growth points to the UAE’s long-term wealth creation potential.
Financial wealth, including both investable and non-investable wealth, grew by 12.3% between 2024 and 2025, rising from $1.2 trillion to $1.4 trillion and is set to rise to $2.1 trillion by 2030 at a CAGR of 8.7%. Real assets reached $2.4 trillion in 2025 from $2.2 trillion in 2024, with projected growth to $4.2 trillion by 2030.
The findings show the resilience of the UAE wealth market amid a volatile global environment and heightened geopolitical uncertainty. “The ongoing conflict has introduced short-term volatility across Middle Eastern markets, with investor sentiment shaped by geopolitical uncertainty and oil-price movements,” said Lukasz Rey, Managing Director and Partner at BCG. “However, the region’s wealth development story remains structurally resilient over the five-year projection horizon. While we anticipate slightly lower growth over the next one to two years, a rebound is expected toward the latter part of the decade, supported by sovereign wealth strength, economic diversification agendas, family-business liquidity events, and continued private capital activity. We expect wealth managers to remain cautious in the near term; however, the long-term wealth opportunity in the Middle East remains intact.”
The report identifies a broader reordering underway across the global wealth-management industry, spanning geographic shifts, emerging-market wealth creation, intergenerational succession, and AI-driven operating model transformation.
Shifting Wealth Concentration Across UAE Population Segments
According to the report, the UAE’s financial wealth remains concentrated among high-net-worth individuals, with the composition of wealth expected to evolve by 2030 as more wealth accumulates within the lower high-net-worth segment. There are approximately 500 ultra-high-net-worth (UHNW) individuals, those with more than US$100 million in assets, in 2025, and they are expected to increase to around 800 by 2030, while their share of total financial wealth rises marginally from 26.3% to 26.5%. The upper high-net-worth segment (US$20–100 million) is forecasted to grow from approximately 2.7K to 4.2K individuals, with its share of wealth broadly stable at 7.4% in 2025 to 7.6% in 2030.
In contrast, the lower high-net-worth segment (US$1–20 million), which comprises approximately 200K individuals, is expected to increase its share of financial wealth from 29.3% in 2025 to 31.5% in 2030. The affluent segment (US$0.25–1 million) is expected to expand from approximately 500K to 600K individuals in 2030, while its share of wealth declines from 15.5% to 14.6% as wealth disperses across a larger base. The mass segment (below US$0.25 million) remains the largest by population, growing from roughly 8.6M to 9M individuals, but its share of financial wealth decreases from 21.5% to 19.8%.
The key UAE findings of BCG’s proprietary analysis are:
- Financial wealth reaches $1.4 trillion in 2025, with strong projected growth to $2.1 trillion by 2030 (CAGR: 8.7%)
- Real assets rose to $2.4 trillion in 2025 and are expected to hit $4.2 trillion by 2030 (CAGR: 11.5%)
- Liabilities climbed to $220 billion in 2025 from $210 billion in 2024, with projections indicating $340 billion by 2030 (CAGR: 8.9%)
- Cross-border financial wealth belonging to UAE residents and booked outside the UAE surged by 9.4% between 2024 and 2025 in the UAE, reaching $468.4 billion. It is forecasted to grow to $678.2 billion by 2030 with a CAGR of 7.7%.
- Separately, the UAE continues to strengthen its position as a global wealth booking center, with cross-border wealth belonging to international clients and booked in the country reaching $721 billion in 2025, up 11.1% year-on-year.
- Currency & Deposits, valued at $471.8 billion in 2025, is projected to grow to $778.9 billion by 2030, with a CAGR of 10.5%
- Bonds are expected to reach $27.8 billion by 2030 from $15.9 billion in 2025, with a CAGR of 11.8%
- Equities, valued at $419.4 billion in 2025, are expected to reach $591.9 billion by 2030 at a CAGR of 7.1%
- Life Insurance & Pensions are valued at $26.6 billion in 2025 and projected to grow to $48.4 billion by 2030 (CAGR: 12.7%)
AI Is Reshaping the Economics of Wealth Management
BCG’s report finds that AI is beginning to reshape wealth-management economics and operating models. AI-powered tools are already drafting financial plans, automating compliance documentation, generating portfolio rationales, and predicting client churn. According to BCG analysis, AI-first wealth managers could unlock 25%–30% capacity gains across key workflows while increasing revenue per advisor by 15%–20%. The report argues that the industry is approaching a structural divide between firms redesigning workflows around AI agents and those layering AI tools onto legacy processes.
“The UAE’s wealth pool is set to grow by more than $2 trillion over the next five years, and the constraint on capturing that growth is advisor capacity rather than client demand,” said Mohammad Khan, Managing Director and Partner at BCG. “Firms that are redesigning their workflows around AI agents are creating the headroom to serve a larger client base without diluting the quality of advice. Those layering AI onto legacy processes are paying for the technology without changing their economics, and that gap widens the longer it is left.”
Wealth managers face a choice between adapting incrementally and committing to an AI-first future, with the report identifying the latter as the more sustainable approach. Key priorities include:
- Map value chain exposure: Identify rules-based, templatized processes most vulnerable to automation. Distinguish truly bespoke, relationship-dependent work from structured, repeatable tasks to guide investment decisions.
- Attack high-cost workflows: Scale AI now in financial planning, portfolio management, and compliance, automated drafting, AI-generated rationales, knowledge assistants.
- Rebuild the advisor experience around AI: Integrate next-best-action prompts, retention alerts, automated documentation, and personalized outreach into a unified system.
- Encode institutional knowledge into agents: Pair top practitioners with engineers to build and refine AI agents. Embed advisor judgment into today’s agents, without centralized ownership and outcome-based evaluation, differentiation erodes.
- Prepare the tech stack for agents. Introduce a decoupled data layer separating operational systems from data consumption, delivering real-time, API-accessible data while maintaining deterministic control through transaction systems and rules engines.

The Connected Home Is Evolving into an Intelligent Ecosystem

New Partnership Connects Residential Wellbeing With Preventive Healthcare

Dubai Ride-Hailing App Zed Strengthens Leadership with Appointment of Shobhit Singhal to Shape Its Future


-
 Trending12 months ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-

 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
 VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-
 VAR10 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai