 Have a question? +971 56 404 0503

Financial
Regulation and Fintech Innovation: A Delicate Balance Shaping the Future of Finance


By Tim Popplewell, CEO, Scintilla
Fintech innovation and regulatory oversight share a complex and often uneasy correlation. Together, their relationship resembles a dance—a tango—where one leads while the other follows, each attempting to set the rhythm. Yet, the key to success lies in balance. The goal of innovation is to build products and services that solve problems, and the goal for regulators is to ensure that all stakeholders are protected, without hindering the process of innovation. Recent events, such as the $3 billion fine imposed on TD Bank for anti-money laundering (AML) failures, demonstrate this intricate interplay. For emerging fintechs, the lesson from this is clear: compliance isn’t merely a regulatory obligation—it’s a business imperative, innovating an approach to AML and compliance practices early on so fintechs can avoid costly pitfalls while simultaneously driving development forward.
The evolving dynamic between regulation and innovation underscores a broader reality: regulation serves not to stifle fintech but to align its rapid advancements with the interests of consumers, economies, and the broader financial landscape, while protecting all stakeholders in the sector. This alignment is not without challenges. Regulators must perform a delicate balancing act, weighing opportunity against risk and ensuring that fintech’s disruptive potential is harnessed for the greater good. This tango is a continuous negotiation, where each step must be carefully calibrated to ensure progress without missteps.
Innovation creates risk, regulators keep them in check
At its core, fintech innovation arises from necessity—businesses identifying gaps in the market and responding to shifting consumer demands. Whether it’s the rise of digital wallets, peer-to-peer lending platforms, or blockchain-based solutions, fintech pioneers have consistently disrupted traditional financial models to deliver faster, cheaper, and more accessible services. But this industry cycle also produces a side-effect in which risks need to be taken, when changes are being made, and regulators need to ensure that consumers, and the general public are not harmed when these risks are being taken.
Yet, while fintech moves at the speed of innovation, regulators are motivated by a broader set of priorities. Their focus extends beyond market gaps to encompass systemic stability, consumer protection, and economic opportunity.
Regulators are tasked with safeguarding the integrity of financial systems, ensuring fair competition, and mitigating risks to global and local economies. This comprehensive approach often finds itself lagging behind innovation, understandably leaving them in a reactive position. This is not necessarily a flaw but a necessity. By observing the impact of fintech innovations in real time, regulators can craft policies that address emerging challenges without stifling creativity. The result is a regulatory framework that not only protects stakeholders but also creates an environment where fintech can thrive sustainably.
Regulation’s role in creating opportunity
While fintech is often seen as the primary driver of transformation, the real power to shape the financial landscape, in fact, lies with regulators. Their policies establish the standards and frameworks that determine how, and to what extent, innovations are adopted at scale. Far from being mere gatekeepers, regulators can act as catalysts for growth by creating conditions that encourage experimentation while minimizing risk.
Switzerland’s Crypto Valley serves as a prime example of how regulatory foresight can unlock opportunity. The Swiss Financial Market Supervisory Authority (FINMA) has worked to establish clear guidelines for blockchain and cryptocurrency projects. These frameworks have not only attracted major players like JPMorgan but have also provided smaller startups with the clarity and confidence needed to innovate. By defining the rules of engagement, FINMA has fostered a productive environment where incumbents and challengers alike can experiment with new technologies without fear of regulatory ambiguity.
The regulatory environment, when designed thoughtfully, offers a dual benefit. It paves the way for mass adoption by providing consumers and businesses with the trust and security needed to embrace new solutions. Simultaneously, it fosters competition and collaboration, encouraging fintechs to build on established innovations to create even more advanced offerings.
The regulatory objective to protecting the consumer
Amid the excitement of fintech innovation, it’s easy to overlook the most critical stakeholder: the consumer. For all its potential, fintech must ultimately serve the needs of the people who use its products and services. This imperative is central to regulatory agendas, which prioritize consumer safety and trust above all else.
The rapid evolution of digital finance—from the rise of credit and digital banking to the advent of cryptocurrencies and tokenized assets—has created both opportunities and risks for consumers. While fintechs race to capitalize on shifting demands, regulators work to ensure that consumers are not left vulnerable to exploitation or harm.
This focus has driven the development of compliance standards such as AML and know-your-customer (KYC) requirements, which hold financial institutions accountable for safeguarding consumer interests. However, these regulations do more than just protect consumers—they also spur innovation. Fintech companies are increasingly leveraging artificial intelligence (AI) and blockchain technology to streamline compliance processes, demonstrating how regulation can serve as a springboard for technological advancement.
For instance, AI-powered KYC solutions are reducing onboarding times while enhancing accuracy, and blockchain-based systems are creating tamper-proof records that bolster trust in tokenized assets. By prioritizing consumer safety, regulators not only mitigate risk but also create opportunities for fintechs to differentiate themselves through innovation.
The need to manage risk to economies and markets
While consumers are a primary concern, regulators must also consider the broader economic implications of fintech innovation. There’s a reason many new fintech companies are called ‘disruptors’; disruption is inherent to fintech’s DNA, but unchecked disruption can pose significant risks to local and global markets.
Take, for example, the rise of cryptocurrency and blockchain-based finance. By enabling near-instantaneous cross-border transactions, crypto has the potential to upend traditional banking systems. Yet, this same capability has also raised concerns about money laundering and illicit activities, prompting regulators to take a cautious approach.
In Dubai, the Virtual Assets Regulatory Authority (VARA) has established a rigorous compliance regime, not just for cross-border transactions but for fintech companies more widely and the license to operate in this region rests with these requirements.
While the high cost of obtaining a VARA license has limited market entry for smaller players, it has incentivized collaboration within the industry. For example, Scintilla Network, a leader in tokenized real-world assets, has extended its broker-dealer license to partners, creating a collaborative ecosystem where smaller firms can innovate without bearing the full burden of regulatory compliance.
Such examples highlight a crucial dynamic: regulation may introduce challenges, but it also drives solutions. By encouraging collaboration and resource-sharing, regulatory frameworks can encourage an environment where innovation thrives despite—or perhaps because of—the constraints imposed.
Ensuring a level playing field
As fintech matures, regulators face a growing challenge: maintaining fairness in an increasingly competitive landscape. While collaboration has been a boon for the industry, the looming threat of market monopolies is a significant raison d’être for regulators who serve to cultivate equal opportunities for businesses.
Major players are rapidly consolidating their positions, leveraging their scale and resources to dominate emerging markets. But where newcomers and new entrants to the industry may have once held the upper hand with niche offerings and never-seen before USPs, the big dogs are quickly catching up, offering the same if not better services, products and user experiences to its already significant share of the market.
Are we seeing a monopolized market in the making? Perhaps. The competitive landscape is not just an economic issue—it’s an innovation issue. Smaller fintechs are often the source of groundbreaking ideas that challenge the status quo. It will be up to regulators to re-level the playing field for smaller institutions to maintain access to its piece of the growing, global, digital asset pie.
Finding balance in the future of fintech
As fintech and regulation continue their intricate dance, the path forward will require careful coordination. Innovation must be encouraged, but not at the expense of stability or fairness. Regulation must adapt, but without stifling the creative spirit that defines fintech. This balance is not easy to achieve, but it is essential for ensuring that the benefits of fintech are shared widely and sustainably.
Regulation provides the structure, ensuring that each step is deliberate and aligned with the broader interests of society. Together, they navigate the complexities of the financial landscape, charting a course that is both dynamic and secure.
The $3 billion fine levied against TD Bank serves as a stark reminder of the stakes involved. For fintechs, the message is clear: robust compliance is not optional—it is a prerequisite for sustainable growth. By embracing regulation as a partner rather than an adversary, fintech companies can not only avoid costly missteps but also unlock new opportunities for innovation.
In the end, the relationship between fintech and regulation is not a battle but a partnership—a dance that, when executed with care, can lead to a future where innovation and stability coexist.





MidChains FZE, a digital asset platform licensed by the Virtual Assets Regulatory Authority (VARA) to provide broker-dealer services to retail, institutional and qualified investors, today announced a strategic banking partnership with Standard Chartered.
Under the partnership, Standard Chartered will support MidChains with a range of banking services, including fiat settlement capabilities, segregated client money accounts, and correspondent banking. These services will power MidChains’ day-to-day operations and enable efficient settlement.
Rola Abu Manneh, Chief Executive Officer, UAE, Middle East and Pakistan, Standard Chartered, said: “The UAE has established itself as one of the world’s leading regulatory environments for digital assets and a global centre for financial activity. That creates a strong setting for regulated digital asset firms and established financial institutions to work together. Our partnership with MidChains puts that opportunity into practice, with Standard Chartered providing the banking services that support its institutional activity, including fiat settlement, segregated client money accounts and correspondent banking.”
Basil Al Askari, Chief Executive Officer, MidChains, added: “Institutional capital moves continuously between traditional and digital markets, and the infrastructure supporting that activity must keep pace. For institutional investors, digital asset services need to connect with the banking system that supports their wider activity. Our partnership with Standard Chartered brings that connection to MidChains’ institutional services, supporting clients as capital moves between traditional and digital markets.”
By bringing a VARA-licensed digital asset platform together with an established international bank, the partnership connects institutional digital asset activity with the banking infrastructure behind fiat settlement. It is a practical example of how the UAE’s regulated financial ecosystem can link innovation with established banking capabilities to support international business.
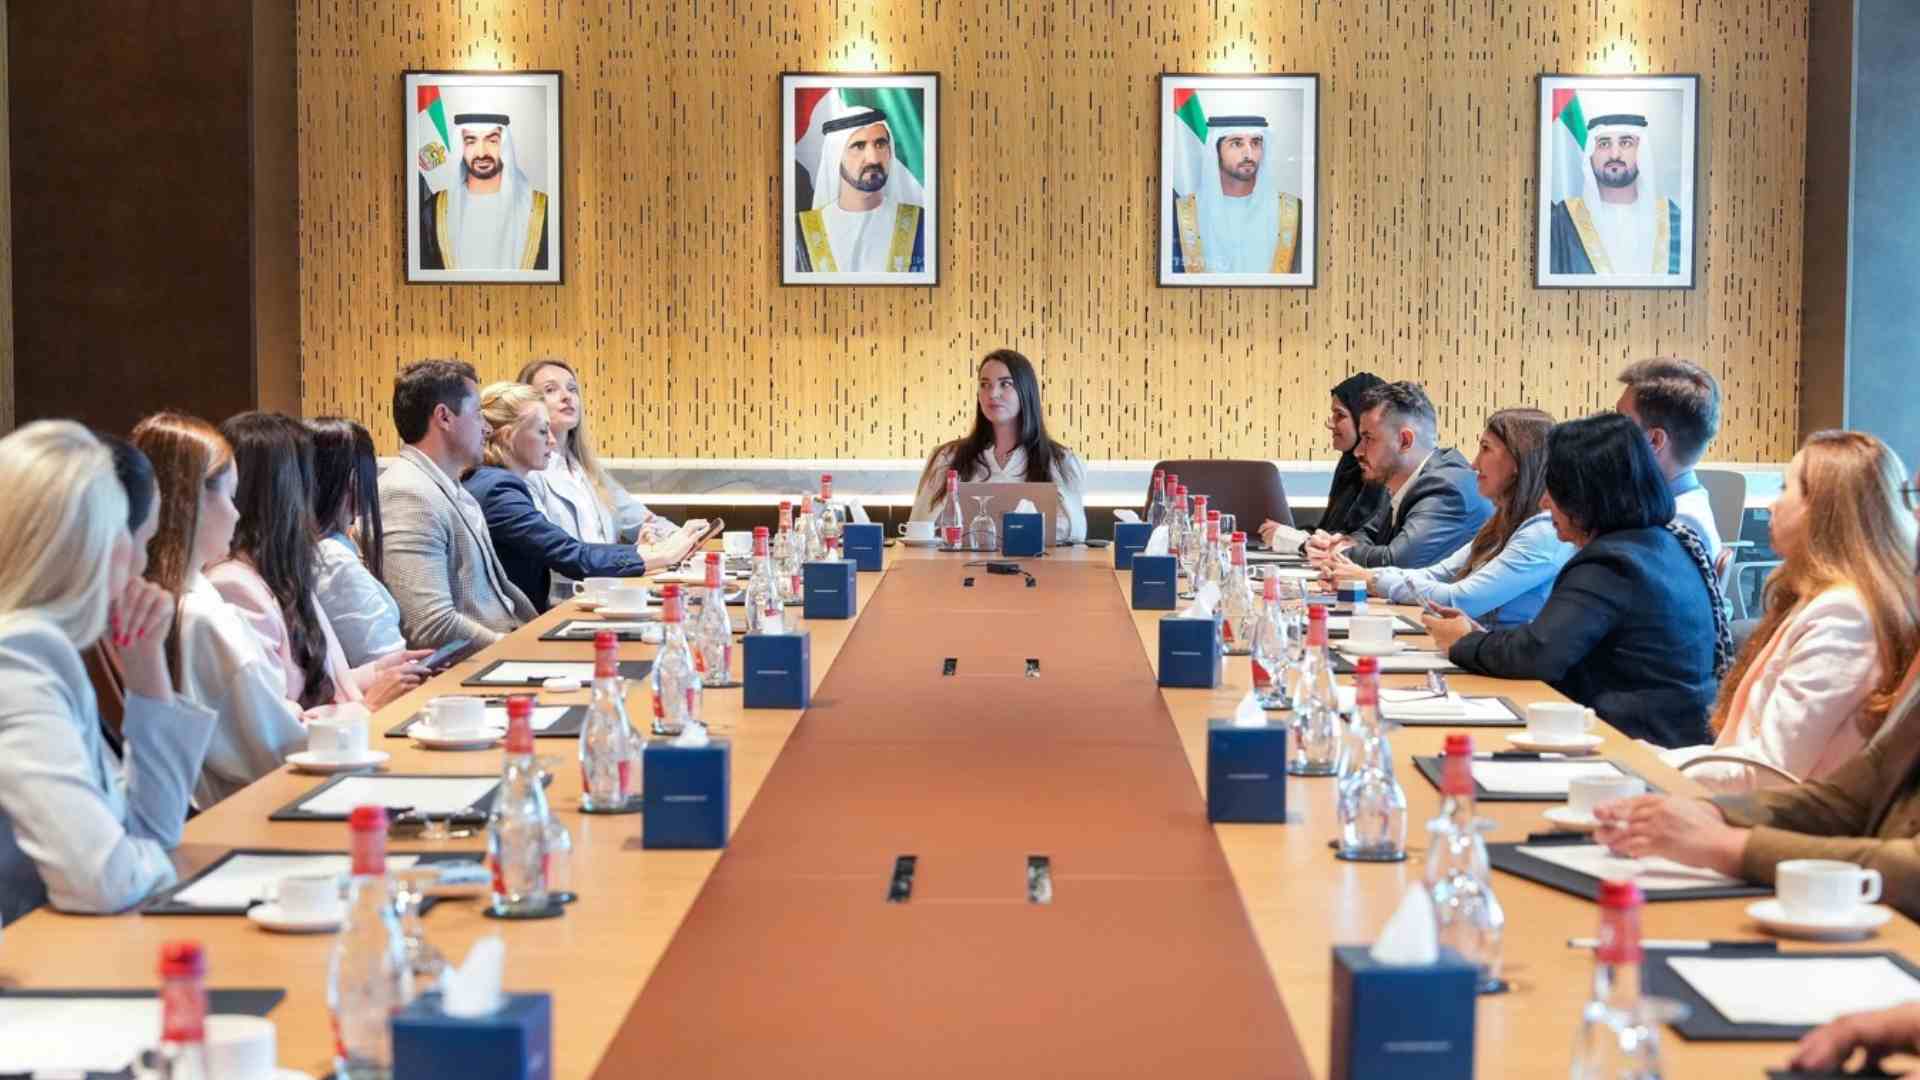
The Ukrainian Business Council in the UAE (UBC) elected a new Board at its General Assembly at Dubai Chamber, where members also approved a 2026–2028 strategy to strengthen trade and investment between the two countries.
Over the next three years, the Council plans to extend its trade delegation programme to new markets, deepen ties with international business councils and launch structured investment dialogues to connect UAE investors with opportunities in Ukraine. The UAE–Ukraine Comprehensive Economic Partnership Agreement (CEPA), Ukraine’s first agreement of its kind with a Gulf state, came into force in July 2026 and removes or reduces customs duties on most goods traded between the two countries.
“Ukrainian companies are achieving real results in the UAE, and we see significant untapped potential for Emirati business and investment in Ukraine. Our role is to build on this momentum: to connect the right partners, support companies at every stage of their growth and help investment flow with confidence in both directions.” commented Olena Shyrokova, President, Ukrainian Business Council in the UAE.
In 2025 and 2026, UBC led business delegations to Vienna, Qatar, Ras Al Khaimah, Fujairah, Oman and the Seychelles. It also ran webinars on UAE market entry for Ukrainian companies and business associations and supported the Ukrainian IT delegation at GITEX. Since its founding in 2016, the Council has established a dialogue with the Federation of UAE Chambers and chambers of commerce across the Emirates.
Under the new strategy, UBC will work with international business councils to give Ukrainian companies access to wider business networks in the Emirates and use the UAE as a base for trade missions to the Gulf, Asia and Africa. The Council will help Ukrainian companies in the UAE with registration, investment and expansion. It also plans to help Ukrainian investors find opportunities in the Emirates, attract Emirati investment to support Ukraine’s recovery and develop arbitration and investor protection mechanisms to build confidence in cross-border agreements.
The Council sees the strongest potential in sectors where Ukrainian strengths meet Emirati priorities: agri-food and food security, IT and digital services, renewable energy, logistics and port infrastructure, and post-war reconstruction. These are also the areas both governments have highlighted for future cooperation.
UBC works closely with the Embassy of Ukraine in the UAE and with H.E. Dr Oleksandr Balanutsa, Ambassador Extraordinary and Plenipotentiary of Ukraine to the UAE. The Council took part in the Cities Unite: Cultural and Business Exchange between the UAE and Ukraine dialogue at Expo City Dubai, initiated by H.E. Reem bint Ebrahim Al Hashimy, UAE Minister of State for International Cooperation, and the Embassy of Ukraine.
The Council will continue to support Ukrainian businesses and the wider community, helping companies expand into the UAE and encouraging UAE investment in Ukraine. Businesses, investors and potential partners interested in working with the Council can get in touch by reaching out to info@ukrainianbc.org.
The UAE has built one of the world’s most successful models for attracting foreign direct investment (FDI) and is now positioned to convert that capital into lasting innovation and skill development, according to a white paper from White Paper Media Consulting (WPM), a UAE-based strategic research house that is shaping business and policy conversations in the region using credible datasets and analytical tools.
Beyond the Numbers: The Transformative Intangible Impact of FDI argues that the real returns on FDI now lie in the intangible value it embeds within host economies, with the UAE a defining case study. The paper contends that the next phase will go beyond investment volumes, number of projects, and job creation and be measured also in patents generated, skills transferred, data ecosystems built, and clean technologies commercialized, among other things.
Official data shows that the UAE attracted more than $48.3 billion in FDI inflows in 2025, capturing 3.1% of global flows. Greenfield FDI reflected both volume and capital depth, with 1,562 projects announced for a combined $34.1 billion in capex, or 1.8% of the global total.
The country’s ability to attract investment reflects its competitiveness as a hub for operational efficiency, supply chain integration, and regional headquarters functions. The UAE has deliberately repositioned its FDI strategy toward knowledge-intensive and future-oriented sectors, recognizing that long-term competitiveness is increasingly driven by innovation, digital capabilities, and human capital. This approach aligns closely with the OECD FDI Qualities framework, with tangible examples across each dimension: including the innovation and competitiveness, digitalization and technology adoption, sustainability and clean energy investments for climate targets, and human capital and local expertise.
Drawing on the OECD framework and benchmarks from Ireland, Singapore, Israel, Costa Rica, and Malaysia, the report documents how leading economies have shifted focus from the volume of capital they attract to the long-term value it creates. In the context of UAE, this is visible in the shift in the country’s policies across phases that begin with the Foundation Phase from 1985 to 2005 of Market Liberalization and Infrastructure Creation, culminating in the current positioning as Global Capital and Technology Hub.
The shift to value in the UAE has made a huge difference to the job-creation intensity of FDI. Approximately 2,816 jobs were created in the UAE for every billion dollars received in greenfield FDI in the five years from 2019 to 2023, compared to 2,265 in the previous five years. This is higher than the OECD average of 2,318 and 1,880 respectively.
The paper identifies seven ongoing policy shifts that deepen the qualitative impact of FDI in the UAE, including extending spillovers from free zones into the mainland economy, prioritizing R&D-intensive investment, embedding skills transfer requirements in major projects, and positioning the country as a global leader in IP creation and data governance.
Yazad Darasha, co-founder and director, WPM, said: “As trusted partners of public and private sector clients, we have tracked the UAE’s investment story for years, and the pattern is unmistakable. The country has positioned itself at the front of the race for capital. What we set out to map in this paper is the harder, more valuable contest: converting investment into skills, technology, and economic velocity. It reflects what we do at White Paper Media, turning complex evidence into decisions leaders can act on.”
Dr. Joachim Arnold, CEO of OCO Global, which advises governments and businesses on attracting FDI, building competitiveness, and strengthening economic resilience, and contributed to the study, said: “The UAE’s infrastructure, free zones, and business-friendly environment helped attract companies and drive growth. The National Investment Strategy 2031 signals a more deliberate focus on investment that raises productivity and embeds benefits into the wider economy. The question is no longer only how to attract capital, but how investment creates lasting value, strengthens existing companies, and helps domestic businesses upgrade their capabilities.”
The paper highlights live examples of this transition already underway, among them the Space42 and ICEYE joint venture building satellites on UAE soil, Microsoft’s $15.2 billion investment plan with a commitment to skill one million people, and the UAE’s $30 billion pledge to the Alterra climate fund.
PEAQ Brings a New Era of Social Wellness to Dubai

2026 in Review: Is AI Becoming More of a Management Problem Than a Technology Problem?

MidChains and Standard Chartered establish strategic banking partnership

OPPO A6 Pro 5G Review: Reliable Daily Driver

Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer

Microsoft Launches New Surface Copilot+ PCs for Business
2026 in Review: Is AI Becoming More of a Management Problem Than a Technology Problem?

Inside XPENG Brand Night: AI Mobility Lands Centre Stage in Dubai

Chinese Cars Are Reshaping the GCC Market, but Resale Value Could Be the Next Battleground
-
 Trending1 year ago
OPPO A6 Pro 5G Review: Reliable Daily Driver
-
 Tech News2 years ago
Denodo Bolsters Executive Team by Hiring Christophe Culine as its Chief Revenue Officer
-
VAR2 years ago
Microsoft Launches New Surface Copilot+ PCs for Business
-
 Automotive2 years ago
AGMC Launches the RIDDARA RD6 High Performance Fully Electric 4×4 Pickup
-
 VAR11 months ago
Huawei Nova 14 Pro Review: Where Camera Excellence Meets Ecosystem Evolution
-
Tech Interviews3 years ago
Navigating the Cybersecurity Landscape in Hybrid Work Environments
-

 Hospitality2 years ago
Gulfood 2025 30th Edition Kicks Off Today, Setting New Benchmarks in F&B Growth and Innovation
-

 Tech News1 year ago
Nothing Launches flagship Nothing Phone (3) and Headphone (1) in theme with the Iconic Museum of the Future in Dubai